Newsletter
Keep yourself update with our current news for Juwai IQI
Global Economic Outlook October 2026: Markets Face Renewed Inflation and Higher Capital Costs
Markets Reprice as Commodities Stay VolatileGlobal financial markets are undergoing a major repricing as investors balance resilient growth against renewed inflation risks.Precious metals have seen sharp swings. Gold surged to a record US$5,600 in January, fell below US$4,000 by June and now trades near US$4,350. Silver has also retreated significantly from its January peak of US$121, although it remains more than 50% higher year-on-year. GEO, October 2026Meanwhile, copper has retained gains of more than 40%, supported by stockpiling and mine-supply disruptions. Energy markets have been equally volatile, with Brent crude moving from the low US$60s in February to above US$120 in April, before returning above US$104 as geopolitical tensions intensified. European gas prices have risen by more than 130%. GEO, October 2026Despite these pressures, the S&P 500 remains roughly 13% higher for the year and has recorded 27 record closes, highlighting continued confidence in corporate earnings and AI-led growth. GEO, October 2026Higher Rates Challenge Market OptimismInflation pressures are rebuilding the global risk premium just as major central banks shift away from easing. Futures markets imply an 86%–90% probability of a Federal Reserve rate increase, marking a sharp reversal from the previous easing cycle. GEO, October 2026At the same time, the US 10-year Treasury yield is near 5%, while the 30-year yield has moved above 5.35%, raising the cost of capital across global markets. GEO, October 2026OutlookThe global economy remains resilient, but inflation is proving persistent. Investors will need to balance growth opportunities against higher financing costs, commodity volatility and renewed policy tightening. The key question is whether markets can sustain strong valuations while absorbing a structurally higher cost of capital. GEO, October 2026Download to see insights from other country marketsDownload
5 October
Dubai Property Ownership October 2026: Trusts vs DIFC Foundations for Family Succession
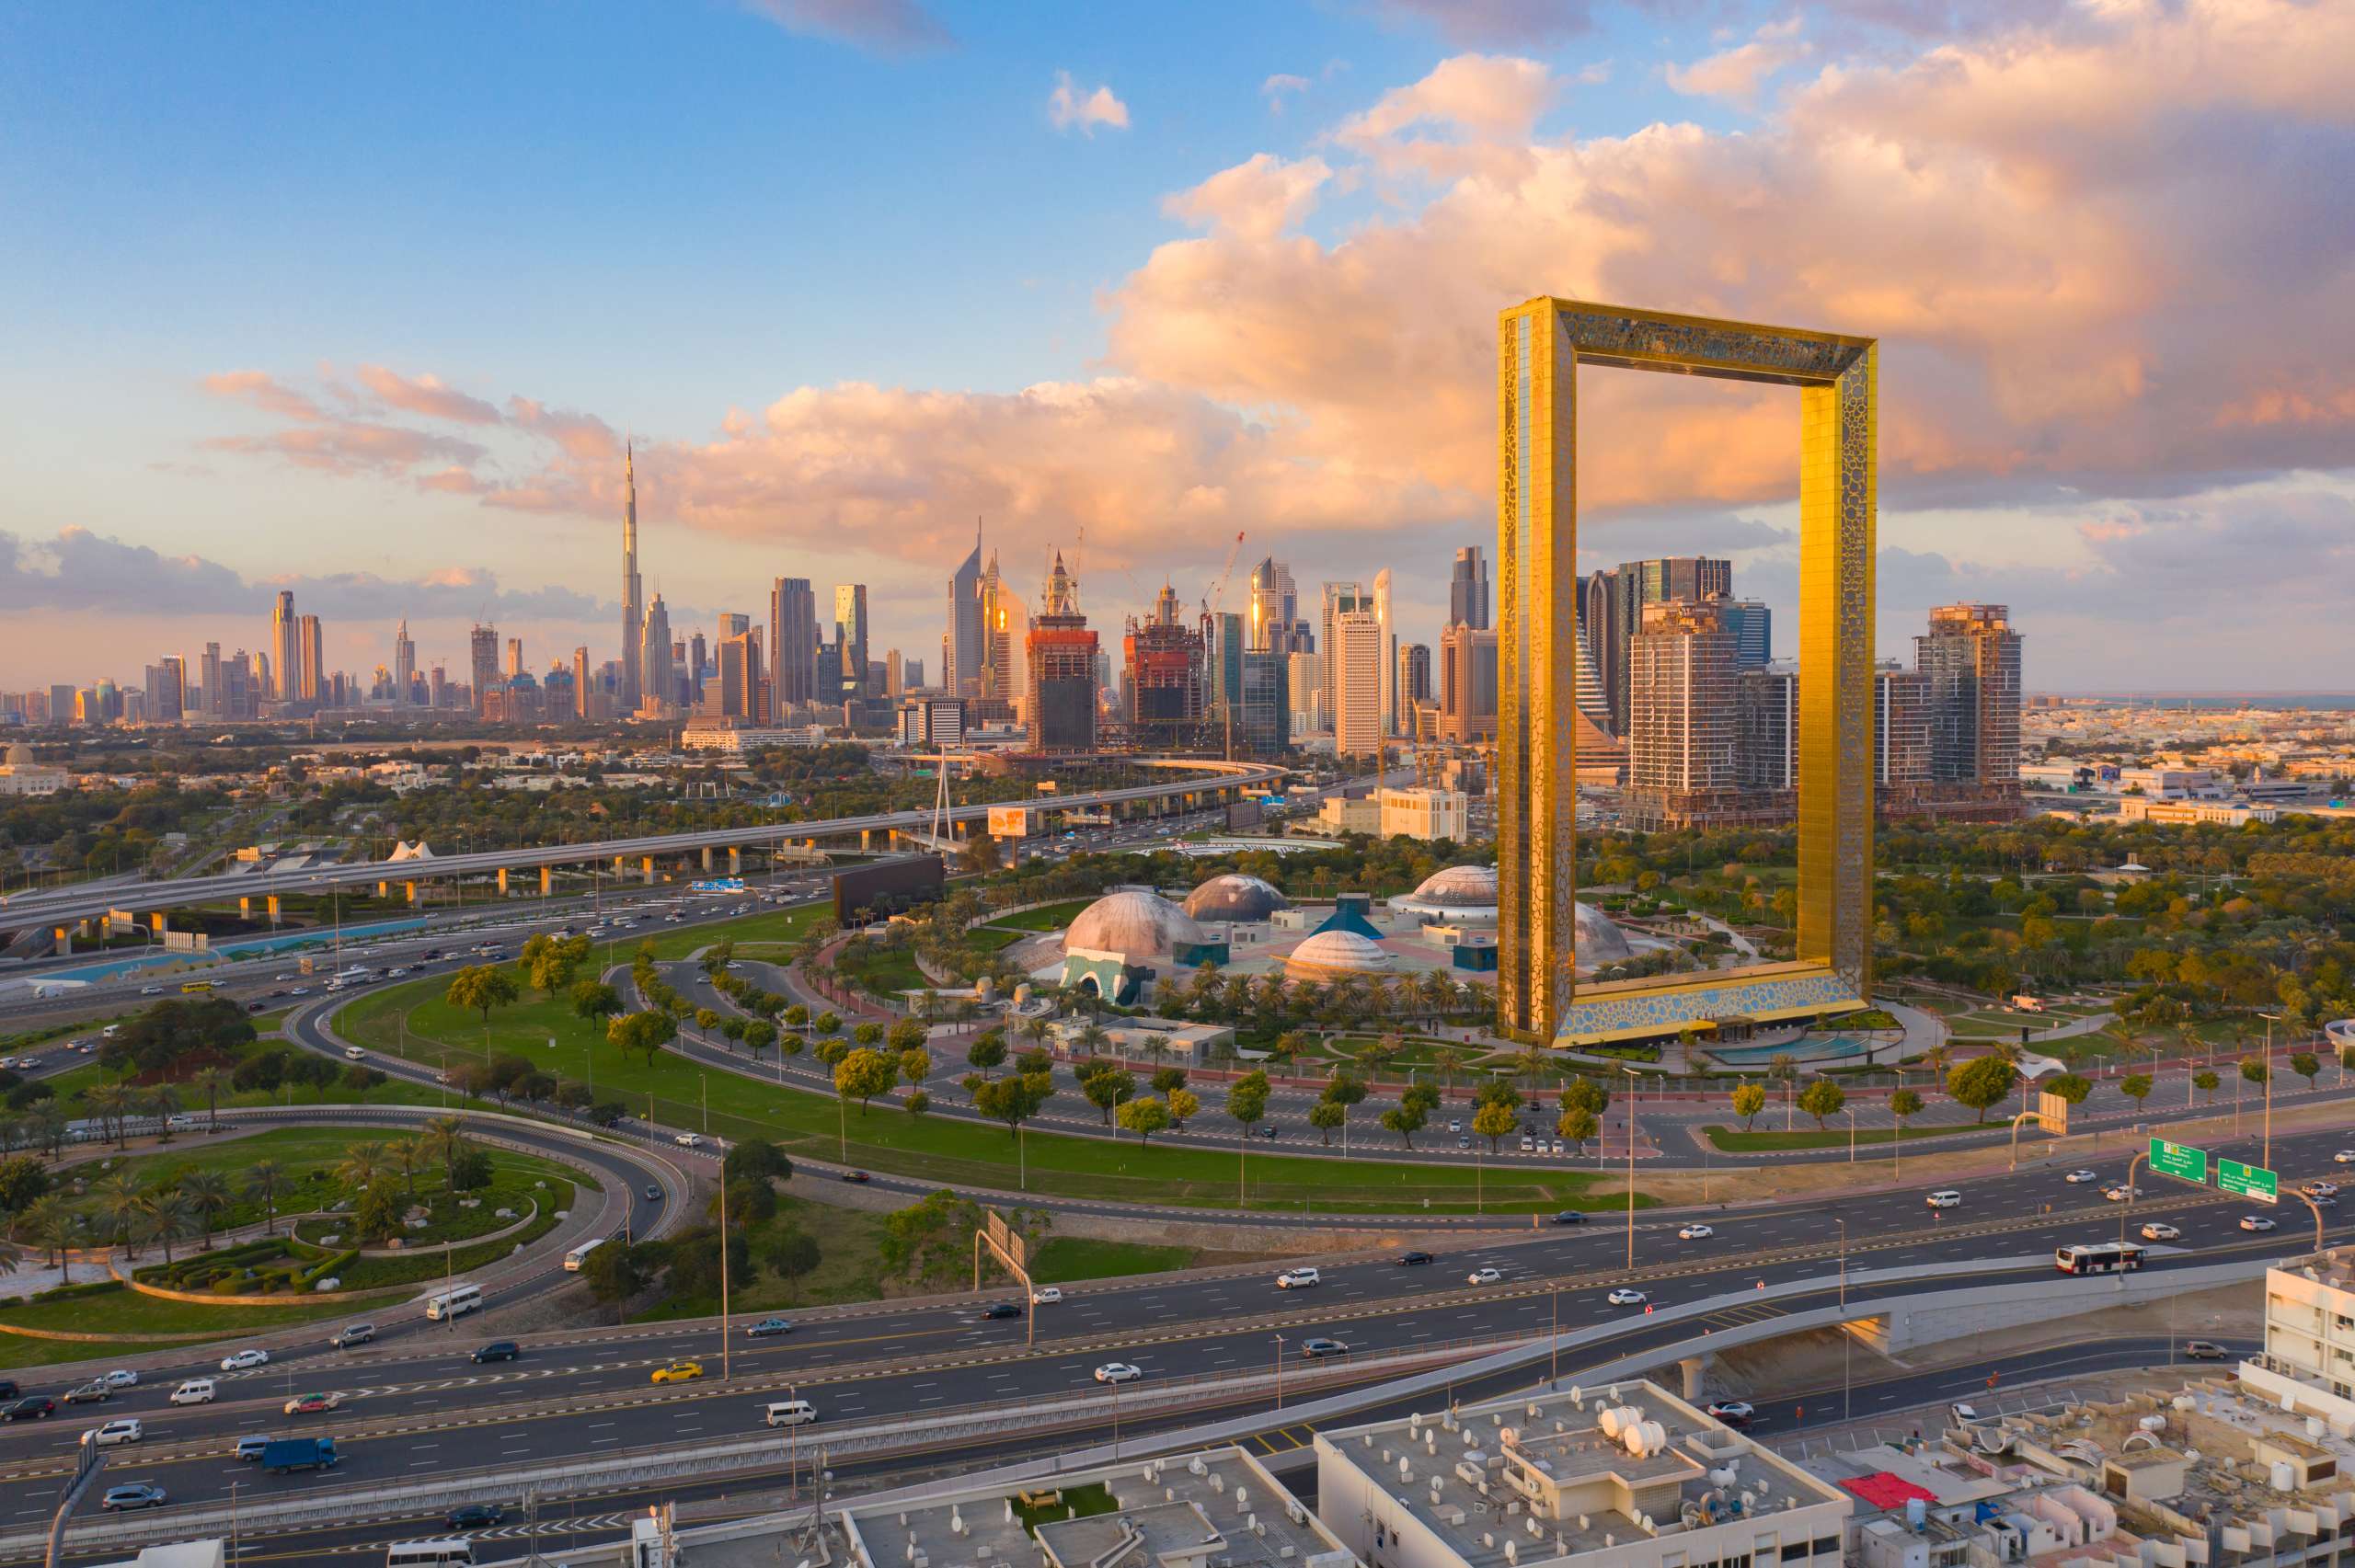
Choosing the Right Structure for Dubai PropertyFor families holding real estate in Dubai, trusts and DIFC Foundations can both separate day-to-day asset ownership from personal succession, but they operate in different ways.A trust is a legal relationship in which trustees hold and manage assets for beneficiaries. By contrast, a DIFC Foundation is a separate legal person that owns assets in its own name and is governed by a Council under its Charter and By-laws. Dubai, October 2026For Dubai real estate, direct ownership through a trust may be less straightforward and often involves an SPV. A DIFC Foundation can hold eligible Dubai property, subject to Dubai Land Department acceptance, registration and applicable fees. Dubai, October 2026Succession and Family ContinuityA key advantage of a Foundation is the ability to establish clear rules around ownership, income, distributions, voting, control and succession. This can be particularly useful where several properties or family businesses need to remain under one ownership structure. Dubai, October 2026If property remains personally owned at death, it may enter probate, become divided among heirs or create co-ownership and potential delays. Where relevant, Sharia inheritance principles may also apply. Transferring property into a valid Foundation during the owner’s lifetime may help preserve continuity because the Foundation remains the legal owner after death. Dubai, October 2026However, a Foundation is not an automatic way to override heirs’ rights. Its effectiveness depends on factors including domicile, religion, transfer timing, local property law, creditor claims and conflict-of-laws rules. Dubai, October 2026OutlookFor property-owning families, succession planning is becoming an increasingly important part of long-term real estate strategy. DIFC Foundations may be especially suitable for complex family ownership structures, but each arrangement should be reviewed carefully with coordinated DIFC, DLD, succession, Sharia and tax advice before any transfer takes place. Download to see insights from other country marketsDownload
5 October
Canada Housing Market October 2026: Softer Prices and Early Signs of Stabilisation
National Market Remains Under PressureCanada’s housing market remained subdued in August 2026, with national home prices down 3.3% year-on-year. High borrowing costs, economic uncertainty and weaker buyer demand continued to weigh on activity, although sales showed some early signs of stabilisation. Canada, October 2026In the Greater Toronto Area, new listings fell 14.1% year-on-year, while sales declined 2.1%. The reduction in available homes is limiting buyer choice and increasing competition in selected areas. The average selling price stood at $993,410, down 2.7%, while the benchmark price declined 4.5%. Canada, October 2026Despite weaker prices, tightening inventory and improving economic conditions could provide support for the Toronto market, with price growth potentially returning if demand strengthens in the coming months. Canada, October 2026Vancouver Faces Ample Supply and Softer DemandMetro Vancouver also remained soft, with sales falling 4.6% year-on-year and sitting 20.7% below the 10-year seasonal average. New listings declined 3%, although overall inventory remained 26.2% above the 10-year average, giving buyers relatively broad choice. Canada, October 2026Slower sales continued to pressure values, with the benchmark home price declining 5.6% year-on-year to $1.082 million. Detached homes and apartments experienced sharper price declines, while townhouse sales showed slightly stronger resilience. Canada, October 2026OutlookCanada’s housing market is likely to remain selective and price-sensitive in the near term. Toronto’s tightening inventory may support gradual stabilisation, while Vancouver continues to favour buyers through higher inventory and softer pricing. A broader recovery will depend on improved affordability, stronger confidence and a sustained improvement in housing demand.Download to see insights from other country marketsDownload
5 October
Cambodia Property Market October 2026: Selective Stabilisation and Infrastructure-Led Growth
Recovery Remains SelectiveCambodia’s real estate market continued to show gradual but uneven stabilisation in August 2026. Residential demand is becoming more selective, with the Borey segment remaining one of the more active residential categories, while condominium recovery is increasingly dependent on location. Cambodia, October 2026The National Bank of Cambodia’s residential property price index declined 3.67% year-on-year in January 2026, while Phnom Penh fell 4.52%, indicating that the market has yet to enter a broad-based recovery. Cambodia, October 2026Prime condominium locations are showing stronger resilience. Indicative 2026 pricing in BKK1 stands at around US$2,800–3,500 per sqm, compared with approximately US$1,400–1,800 per sqm in Chroy Changvar. The July groundbreaking of the 67-storey G.A.T.O. Tower in BKK1 also signals continued developer confidence in selected prime areas. Cambodia, October 2026Infrastructure Shapes Long-Term OpportunityInfrastructure remains one of the strongest drivers of Cambodia’s property outlook. Ring Road 3, the new Techo International Airport, and the southern and western expansion of Phnom Penh are strengthening the investment case for well-connected residential projects and land. Cambodia, October 2026For buyers and investors, current conditions favour realistic pricing, quality development, title security and infrastructure connectivity over broad speculative purchases. Cambodia, October 2026OutlookCambodia’s recovery is likely to remain selective rather than broad-based. The strongest long-term opportunities are expected in affordable landed housing and well-connected growth corridors, particularly where infrastructure development and real economic activity can support sustainable demand. Download to see insights from other country marketsDownload
5 October
Bali & Lombok Property Market October 2026: Selective Growth and Emerging Investment Opportunities
Bali Remains Strong but More SelectiveBali continues to benefit from strong tourism fundamentals, a growing lifestyle economy and sustained interest from international investors, developers and lifestyle buyers. Established areas including Canggu, Uluwatu, Seminyak and Pererenan remain among the island’s most active property locations. Bali and Lombok, October 2026However, rising land prices and increasing competition are making investment decisions more selective. Buyers are placing greater emphasis on location, product quality and operating potential, rather than relying on broad market growth alone. Bali and Lombok, October 2026Bali’s lifestyle and hospitality sector is also continuing to expand. New international concepts such as Taco and Livare expected to begin operations in mid-October, reflecting the island’s increasing appeal as a platform for global hospitality brands and lifestyle experiences. Bali and Lombok, October 2026Lombok Builds Long-Term Investment PotentialLombok is developing from a different stage of the market cycle. The Mandalika area and surrounding infrastructure are supporting the island’s transformation into a more recognised tourism destination. Compared with Bali, Lombok still offers a relatively lower entry point in many areas, while maintaining meaningful future development potential. Bali and Lombok, October 2026For investors, the distinction between the two islands is becoming clearer. Bali offers a mature tourism ecosystem and established international demand, while Lombok provides opportunities linked to infrastructure growth and future tourism expansion. Bali and Lombok, October 2026OutlookThe next phase of growth across Bali and Lombok is expected to become increasingly selective rather than volume-driven. Projects combining strong locations, sound legal structures, quality development and sustainable demandare likely to be better positioned as investors focus more closely on long-term fundamentals. Download to see insights from other country marketsDownload
5 October
Australia Housing Market October 2026: Downturn Deepens as Buyers Gain Leverage
Housing Weakness Spreads Across Capital CitiesAustralia’s housing slowdown intensified through winter, with home values declining across 93% of capital-city suburbs, more than double the 45.8% recorded during autumn. Darwin was the only capital city to avoid a decline over the three-month period. Australia, October 2026Cotality’s national Home Value Index fell 0.9% in August, marking the fifth consecutive monthly decline. National home values are now 3.6% below the March market peak. Sydney remained the weakest capital-city market, falling 1.4% in August and sitting 7.1% below its February peak. Australia, October 2026Melbourne and Canberra each declined 1.1%, while Brisbane fell 1.0%. Adelaide and Perth both recorded a 0.8% decrease, highlighting the increasingly broad nature of the downturn. Australia, October 2026Slower Sales Strengthen Buyer ConditionsHigh borrowing costs, tighter lending conditions and affordability pressures continue to weigh on demand. Quarterly home sales were 15.5% lower than a year earlier and 11.5% below the five-year average, with Brisbane, Perth and Sydney recording annual declines of more than 20%. Australia, October 2026At the same time, capital-city listings were 24% higher than a year ago. Longer selling periods, greater vendor discounts and softer auction-clearance rates are creating more buyer-favourable conditions, although weak confidence continues to limit transaction activity. Australia, October 2026OutlookAustralia’s housing market is likely to remain selective and buyer-driven in the near term. Elevated stock levels and softer demand may continue to pressure values, while buyers with strong financing positions could benefit from greater choice and improved negotiating power. For investors and homeowners, markets such as Perth may still present opportunities for those taking a long-term view.Download to see insights from other country marketsDownload
5 October
Juwai IQI October 2026: Global Property Markets, AI Innovation and New Growth Opportunities
Global Property Markets Turn More SelectiveGlobal real estate is entering a more selective phase, with opportunities increasingly supported by infrastructure, tourism, foreign investment and strong market fundamentals.In Vietnam, GDP grew 8.33% year-on-year in Q2 2026, while registered FDI reached US$40.63 billion in the first eight months of the year, up 55.4%. The Philippines also showed strong momentum, with Metro Manila office net take-up surging 765% year-on-year in Q1 2026, supported by traditional offices, flexible workspaces and the growing GCC sector.Hong Kong’s rental market continued to strengthen, with the Private Residential Rental Index reaching 205.8, around 18.5% above its 2023 trough. In Thailand, international demand remained important, with foreign buyers accounting for 32% of central Bangkok condominium purchases in H1 2026.Malaysia’s premium market also demonstrated resilience. Although total transaction volume declined 4.5%, transaction value increased 2.2%, indicating continued demand for selected higher-value properties.AI Innovation and Global RecognitionBeyond property markets, Juwai IQI continues to strengthen its technology capabilities. Its AI Hackathon brought together 30 teams to develop practical business tools, including an AI Call Simulator, Market Report Generator, Subsale Transaction System and Lead Management System.The month also marked a major milestone, with Juwai IQI named Agency of the Year at the 2026 Realtors’ Roundtable, recognising the strength and contribution of its global network.OutlookThe months ahead are likely to favour selective, fundamentals-driven opportunities. Markets supported by infrastructure, international capital, tourism and resilient demand should remain attractive, while practical AI adoption is set to play a growing role in improving productivity, decision-making and client engagement across the property sector.Discover More HereDownload
5 October
Where to Invest in Asia 2026: Five Property Markets to Watch Next
Asia’s Property Investment Map Is ChangingInternational property investors have traditionally focused on established markets in Europe and the Middle East, but Asia is increasingly moving onto the radar.Across the region, economic growth, infrastructure expansion, tourism and the development of new business hubs are creating fresh property opportunities.In Indonesia, Bali remains a major lifestyle market, while infrastructure investment, the development of Nusantara and new International Financial Centres are broadening the country’s investment story.Vietnam continues to strengthen its position as a manufacturing hub, supported by highways, metro systems and the new Long Thanh International Airport. This is creating potential opportunities beyond Ho Chi Minh City and Hanoi, particularly in areas benefiting from infrastructure and industrial growth. Where Else Should Investors Look?Thailand remains one of Southeast Asia’s most established international property markets. Phuket and Koh Samui are attracting second-home and lifestyle buyers, while Bangkok continues to offer scale and a mature luxury property segment.In Malaysia, Johor stands out. The Johor-Singapore Special Economic Zone and Forest City’s designation as a Special Financial Zone could support future business activity, employment and housing demand.The Philippines also presents selective opportunities. While parts of Metro Manila face significant condominium supply, regional markets such as Cebu and Clark may offer stronger potential where infrastructure, tourism, business activity and population growth align.OutlookThere is no single best market across Asia.The stronger opportunities are likely to be found by following infrastructure, business expansion, tourism and population growth, rather than simply investing at a country level.For investors, the key is selectivity. Indonesia, Vietnam, Thailand, Malaysia and the Philippines each offer different strengths, but the most compelling opportunities will depend on choosing the right location within each market and understanding what is driving future demand.The contents of this article were contributed by Taco Heidinga, Global Real Estate Strategist, Juwai IQI; Country Head, IQI Bali & Lombok; Founder, Homes in Asia.Download to see insights from other country marketsDownload
4 September

