Your Trusted
Real Estate Partner in
Philippines
IQI Philippines provides comprehensive real estate services and makes your real estate process easy with our professional team
Discover
Your one-stop property solution
Get the latest Property News
Expand your knowledge here!
List your property
Have an agent list my property
Global Market Insights
Get detailed property reports and insights across multiple countries
Manage My Deal
Follow up on my buying process
Mortgage Calculator
I want to calculate my budget
Register as a Real Estate Negotiator
I want to be a real estate negotiator in IQI
Philippines Market Insight
The Philippines enters 2026 with a property market defined by "measured opportunity." While a condominium oversupply persists in the capital, pricing has remained resilient, with IQI Global reporting a 6–8% year-on-year price increase in Metro Manila residential sectors. Regional hubs like Cebu and... The Philippines enters 2026 with a property market defined by "measured opportunity." While a condominium oversupply persists in the capital, pricing has remained resilient, with IQI Global reporting a 6–8% year-on-year price increase in Metro Manila residential sectors. Regional hubs like Cebu and Pampanga are outpacing the capital in industrial growth, while rental yields remain healthy, ranging from 5.23% to over 7% in prime districts. Infrastructure projects (Build Better More) and the BPO sector remain the twin engines of long-term value.
New Launches
Latest Listings

La Bella Lifestyle Homes
Tagaytay, Cavite
Starting from ₱ 1,900,000
Listed on September 7, 2021

La Bella Boutique Hotel (Condotel)
Barangay, Tagaytay, Cavite
Starting from ₱ 1,800,000
Listed on September 7, 2021

10 Acacia Place
10 21st Ave, Cubao, Quezon City, Metro Manila
Starting from ₱ 3,000,000
Listed on September 7, 2021

My Enso Lofts
Brgy, Sgt. Esguerra Ave. and, Timog Ave, District 4, Quezon City, Metro Manila
Starting from ₱ 4,500,000
Listed on September 7, 2021

Primehomes Capitol Hills
Zuzuarregui St, Matandang Balara, Quezon City, 1119 Metro Manila
Starting from ₱ 3,600,000
Listed on September 7, 2021

Southkey Place
Crescent Dr, Alabang, Muntinlupa, Metro Manila
Starting from ₱ 2,539,548
Listed on September 6, 2021

Casa de Sequoia
Diego Cera Ave, Las Pinas, Metro Manila
Starting from ₱ 2,295,473
Listed on September 6, 2021

Callisto Tower
Theater Drive corner West Gala Drive, Circuit, Makati, Metro Manila
Starting from ₱ 14,600,000
Listed on September 6, 2021

SYNC Towers
C5 Road, Brgy. BagongIlog, Pasig City
Starting from ₱ 4,291,579
Listed on September 3, 2021

Aruga Resort and Residences by Rockwell
5097 Punta Engaño Rd, Lapu-Lapu City, 6015 Cebu
Starting from ₱ 16,000,000
Listed on September 3, 2021

Amonsagana Residences in Balamban, Cebu
No. 1, Sagana Drive, Amonsagana Phase 1, Mandayao Hills, Barangay Pondol, Balamban 6041, Cebu
Starting from ₱ 15,500,000
Listed on September 3, 2021

Provence At Tagaytay Highlands
Provence, Tagaytay Midlands, Brgy . Aya , Talisay
Starting from ₱ 8,562,000
Listed on May 21, 2021
Our story
Award-winning PropTech Agency

IQI goes beyond conventional boundaries.
With offices in 30+ countries and 60,000+ real estate negotiators and growing, we have a unique perspective into international best practices in real estate, allowing our team to become global real estate entrepreneurs through cross border property investment and transactions.
Countries
Agents
Projects
AI-Powered App for Agents on the Go
Introducing IQI Atlas SuperApp and IQPilot. Your proprietary AI duo built to manage leads, sales, earnings and every step of your real estate journey, anytime, anywhere.
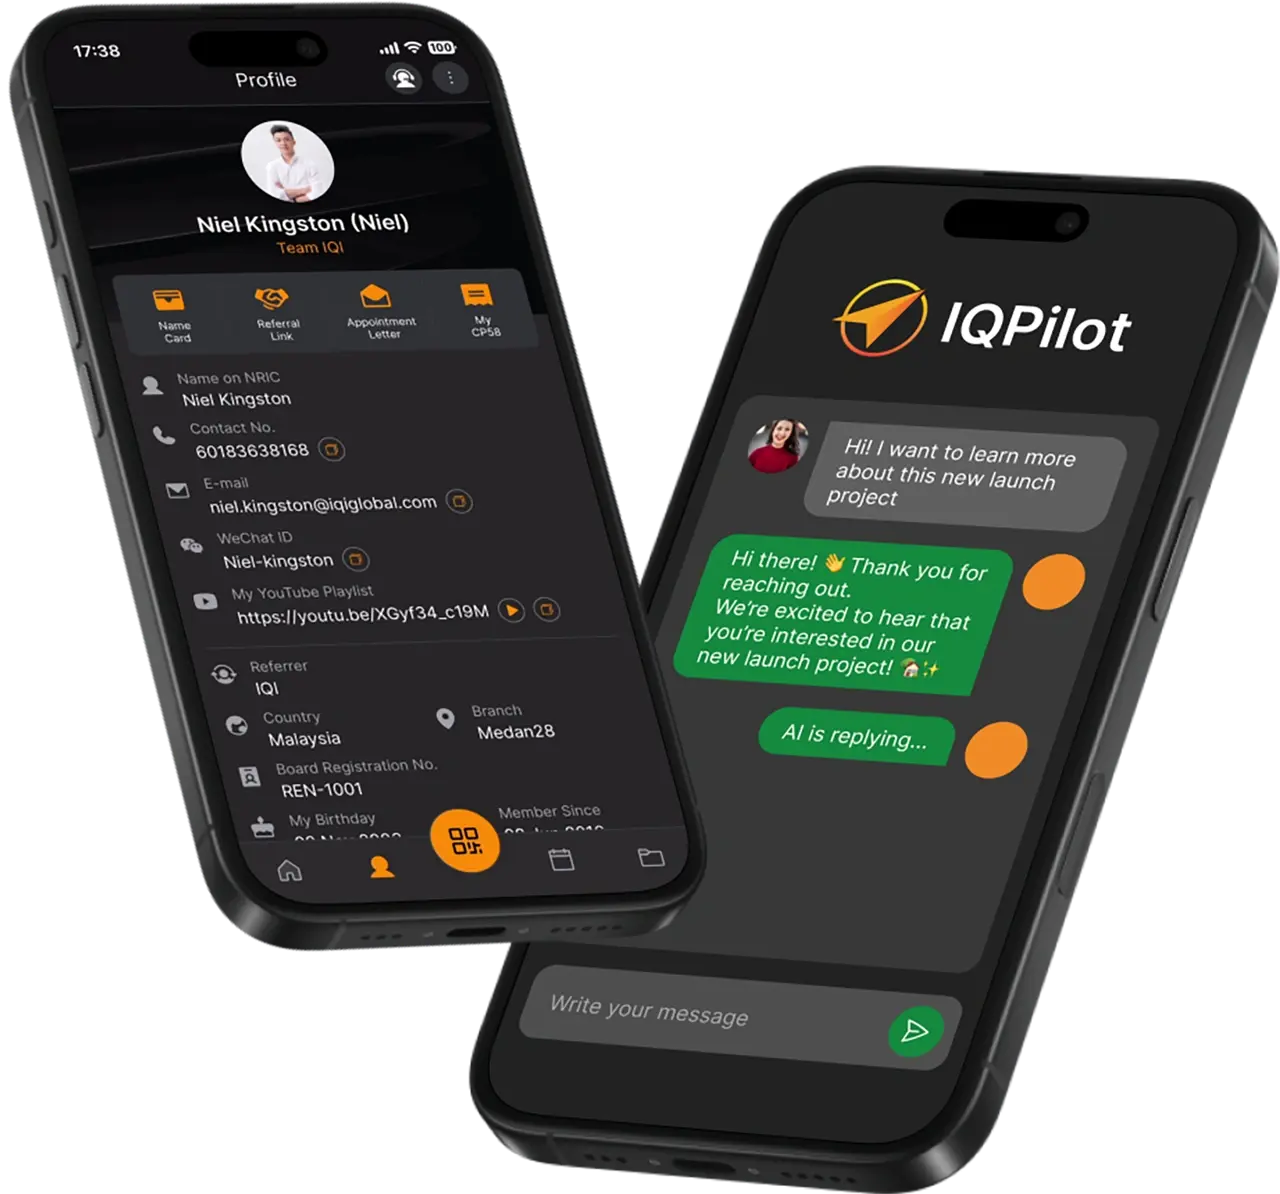
All-in-one
Connecting you globally
Invest with us
Invest on a platform with over 6 million global properties from more than 111 countries to empower yourself as a citizen of the world.
Advertise with us
Maximise advertising efficiency and lead conversion through our buyers using data.
Testimonials
Hear from our happy buyers
Learn
Tips and Guides
 Philippines Property Market October 2026: Recovery Strengthens Across Residential, Office and Industrial Sectors
Residential Recovery Moves Into Clearer View The Philippine property market is showing stronger signs of recovery, led by a sharp improvement in residential absorption. In Metro Manila, preselling net take-up surged 765% year-on-year in Q1 2026, driven mainly by the economic and affordable segments. As a result, remaining inventory life fell to 6.8 years, down from a peak of 13.4 years in mid-2025. Developers are now prioritising the clearance of ready-for-occupancy stock before launching new projects, while completions are expected to decline from 2027 onward. Vacancy is still projected to reach 25.6% by year-end, but this largely reflects earlier supply decisions rather than current demand conditions. Demand also remains healthy in well-priced fringe locations such as the C5 Corridor and Katipunan, reinforcing the importance of the right combination of product, location and pricing. Commercial and Industrial Demand Adds Depth The recovery is also being supported by stronger commercial demand. The Philippines is ranked as the world’s second-largest GCC delivery location, with the GCC workforce projected to reach around 289,000 professionals across approximately 200 centres in 2026. This is supporting demand for prime CBD offices and key provincial markets. Tourism has also improved, with 3.16 million international arrivals in H1 2026, up 5.4%, while hotel average daily rates rose 2.4%. Industrial remains another strong segment, supported by new logistics supply and PHP 81.4 billion in approved foreign manufacturing pledges. Outlook The Philippines appears to be entering a confirmed recovery phase, but opportunities remain selective. With buyer-friendly pricing gradually being absorbed and future supply becoming more constrained, well-located residential, office and industrial assets may benefit most as the market continues to improve. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Continue Reading
 Philippines Property Market 2026: Recovery Strengthens Across Key Sectors
Industrial and Commercial Recovery Gains Ground The Philippine property market entered the second half of 2026 with recovery strengthening across industrial, commercial and residential real estate. Industrial property remains the standout segment. First-half merchandise exports reached US$46.72 billion, the strongest performance since 1991, supported by electronics demand linked to the global AI supply chain. This momentum is feeding into a 1,200-hectare industrial land pipeline for 2026 to 2028, while industrial rents have increased 45% since 2019. New demand from EV and battery manufacturers is also supporting the sector. Metro Manila’s office vacancy remained stable at 19%, despite softer leasing volumes, while flexible workspace take-up doubled year-on-year. Retail vacancy is expected to fall below 10% by year-end, while around 3,100 new hotel rooms are scheduled for delivery in 2026. Residential Buyers Still Hold the Advantage The residential market remains firmly buyer-favourable. Inflation eased to 6.2% in July, marking a third consecutive month of improvement, while the BSP was expected to maintain its policy rate at 4.75%. Developers continue to compete for buyers through extended payment terms, rent-to-own structures and effective discounts of 3% to 12%. At the same time, future condominium supply is tightening sharply. Annual completions are expected to average around 3,600 units through 2028, down 72% from the 2017 to 2019 average. Outlook The Philippines is entering a potentially important transition period. Improving inflation, the prospect of lower borrowing costs and a shrinking condominium pipeline could support stronger residential absorption into 2027. Meanwhile, industrial assets remain the strongest structural growth story, supported by exports, manufacturing and infrastructure demand. For investors, the second half of 2026 offers an opportunity to focus on quality industrial assets, flexible commercial space and competitively priced residential properties before financing conditions improve further. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Continue Reading
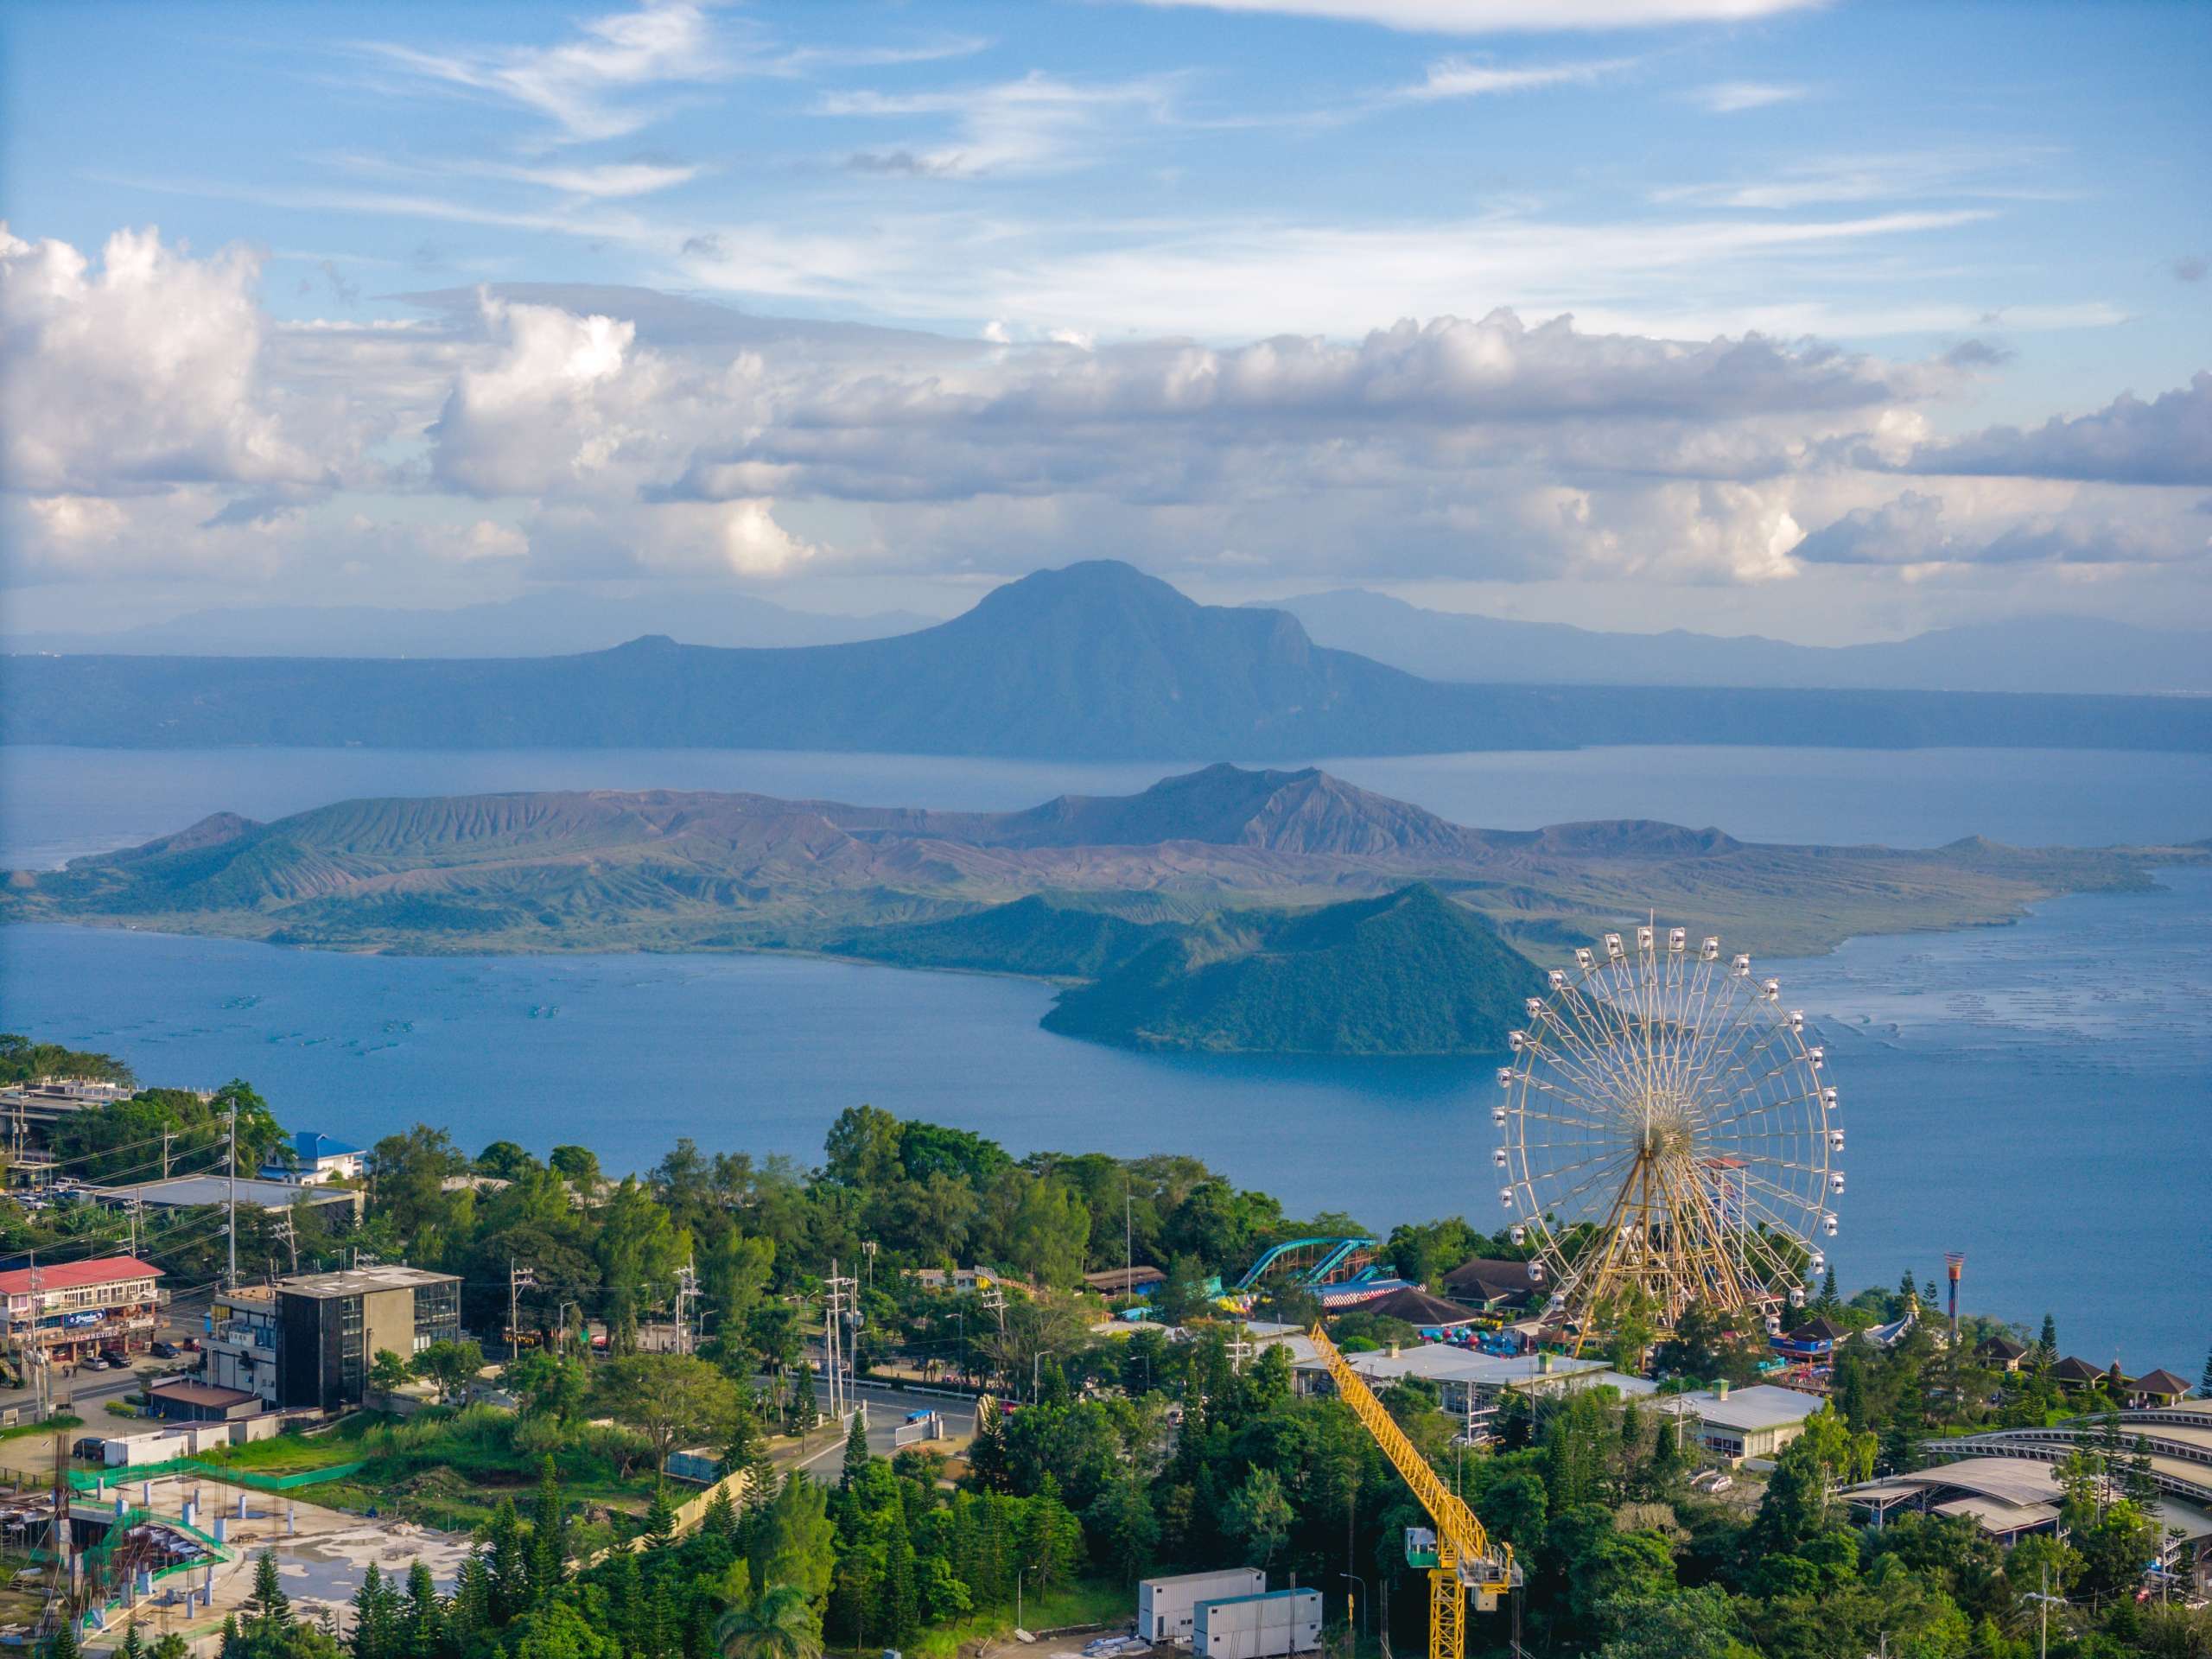 Philippines Property Market Outlook 2026: Industrial Assets Lead as Inflation Eases
Inflation Eases as Market Conditions Improve The Philippines property market entered the second half of 2026 with a gradually improving economic outlook. Inflation declined for a second consecutive month, falling from 7.2% in April to 6.4% in June. Lower fuel and transport costs supported the improvement, while monthly inflation recorded its first decline in a year at -0.3%. The Bangko Sentral ng Pilipinas raised its policy rate to 4.75%, but inflation is expected to ease further through 2028. Economic growth is also forecast to strengthen from 2.8% in Q1 2026 to 4.4% for the full year, supporting future consumption, investment and property demand. Industrial Property Offers the Strongest Prospects Metro Manila condominiums remain a buyer’s market, creating opportunities for buyers seeking discounted properties. New condominium completions are expected to average only 3,600 units annually from 2026 to 2028, significantly below the 13,000-unit annual average recorded between 2017 and 2019. This lower supply pipeline could gradually reduce excess inventory. Developer incentives, strong overseas Filipino worker remittances and projected national price appreciation of 25% to 35% by 2031 may support long-term residential demand. Metro Manila’s office vacancy rate improved to 19%, supported by limited new supply and demand beyond the business process outsourcing sector. Retail vacancy is also expected to fall below 10% as household spending recovers. Industrial property remains the strongest segment, led by Central Luzon and the Clark corridor. Rising rents, logistics improvements, e-commerce growth and demand for energy-resilient facilities continue to strengthen investment fundamentals. Outlook Industrial and Clark corridor assets offer the strongest risk-adjusted opportunities. Selected CBD offices, retail properties and discounted condominiums also present improving prospects. Investors should remain selective, prioritising quality assets, strong locations and longer holding periods while monitoring inflation, electricity costs and geopolitical risks. Juwai IQI Newsletter August 2026Download
Continue Reading
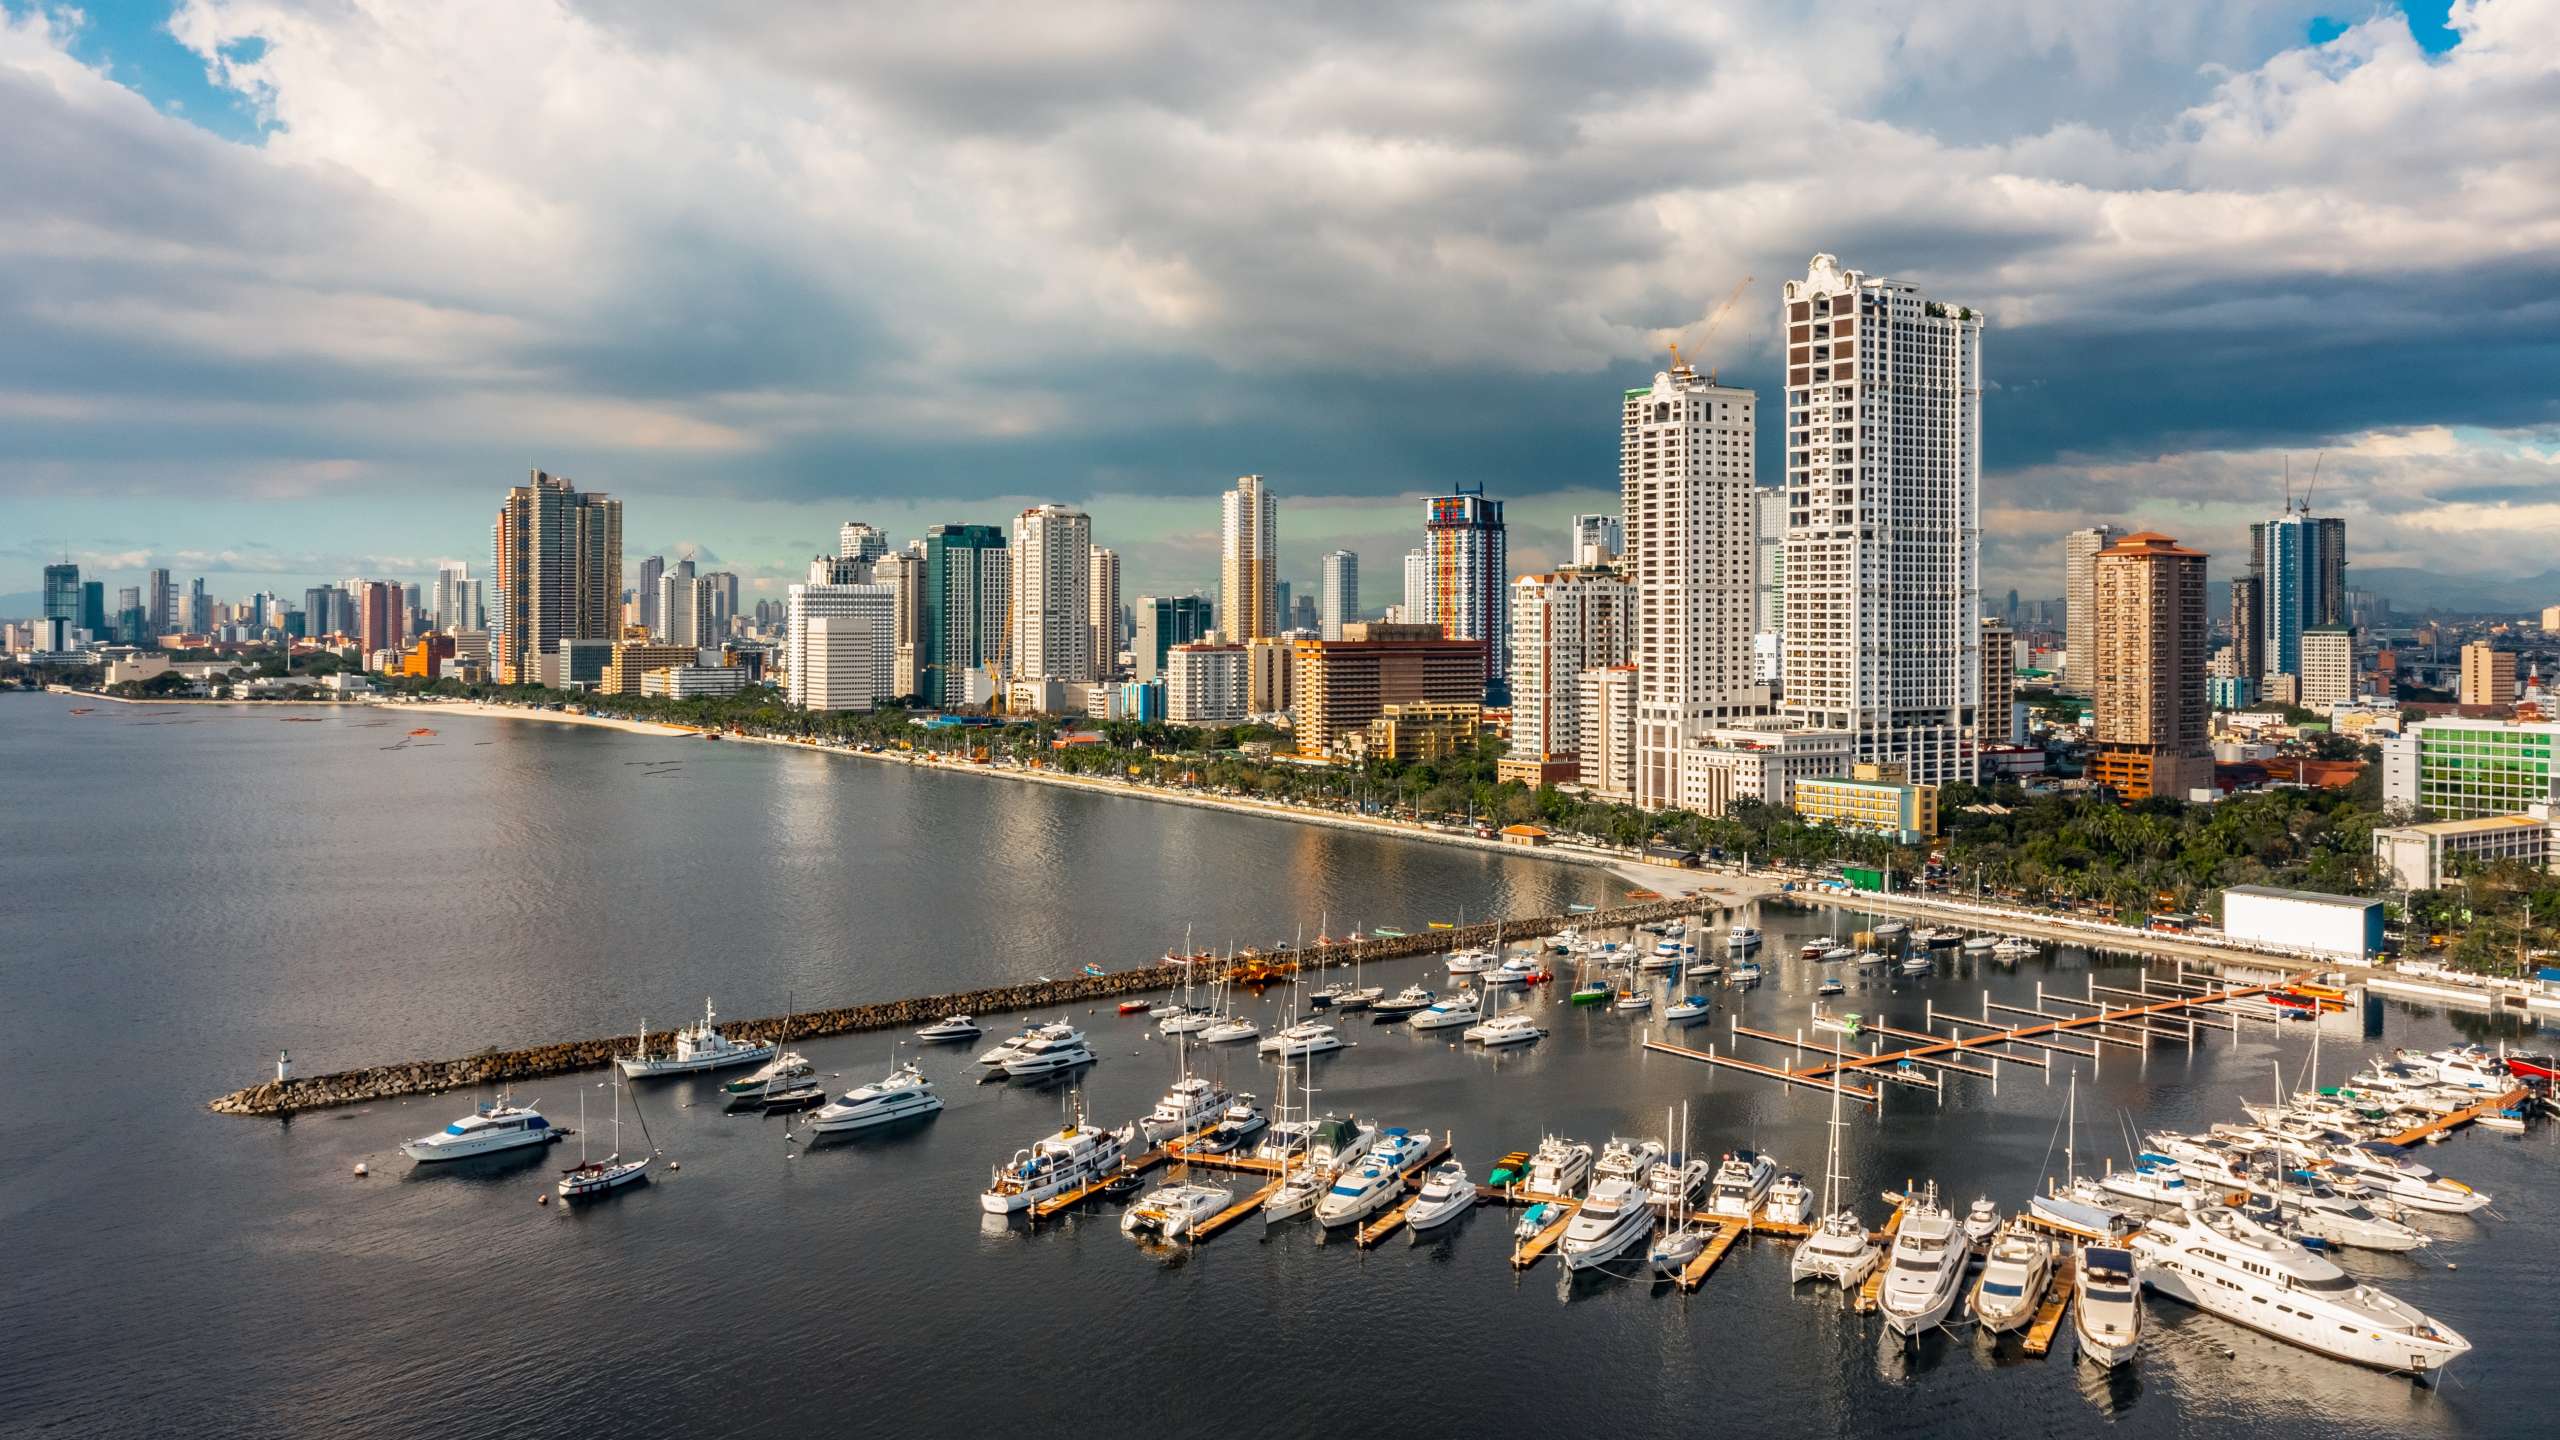 Philippines Property Market July 2026: Recovery Builds as Energy Pressure Eases
Philippines Real Estate Shows Stronger Recovery Signals The Philippines property market is entering the second half of 2026 with improving momentum. The US-Iran ceasefire and reopening of the Strait of Hormuz have helped stabilise global oil markets, leading to major fuel rollbacks in the Philippines. This is easing pressure on household budgets and business costs, while also supporting buyer confidence. At the same time, the proposed Japan-Philippines petroleum reserve partnership strengthens the country’s long-term energy security outlook. The residential market remains selective. Metro Manila condominiums are still a buyer’s market, with around 74,000 to 75,300 unsold units. However, developer discounts, rent-to-own schemes and longer payment terms are creating attractive entry opportunities. Supply is also expected to tighten, with only about 3,600 new condo units annually from 2026 to 2028, far below the previous peak average of 13,000 units. Regional markets such as Cavite, Laguna, Cebu, Iloilo and Davao remain stronger performers, with projected annual appreciation of 5% to 7%. Industrial and Commercial Segments Lead Growth Industrial and logistics remain the strongest investment theme. The New Clark City industrial hub is reinforcing the Clark-Pampanga corridor as a key manufacturing and logistics destination, while industrial rents have risen 45% since 2019. Commercial property is also improving. Office demand rose 70% year-on-year in Q1 2026, supported by BPO and IT-BPM expansion. Retail vacancy is expected to fall below 10% by end-2026, while hospitality is benefiting from flight surcharge cuts and route restoration. Outlook The Philippines market is not without challenges, but its fundamentals remain strong. With 115 million people, record OFW remittances, infrastructure expansion and improving energy stability, H2 2026 could mark a clearer recovery phase. Industrial assets, Clark-linked logistics, regional residential corridors and prime income-generating assets are likely to remain the best-positioned opportunities. Download to see insights from other country marketsDownload
Continue Reading
Be updated on new launches
Subscribe to our emails to find out about the latest property news, trends and launch dates.

 IQI Global
Philippines
+63 917 881 55525th Floor, Liberty Bldg, 835 Arnaiz Avenue, Makati City, Metro Manila, Philippines
Juwai.com, Juwai.asia, IQI, and Juwai IQI are trademarks of Juwai IQI group. All rights are reserved.
© IQI Global 2026
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
Your privacy matters!
We use cookies. See our Cookie Policy.
Got questions? 😊 I'm JIQI, happy to help!