

Negotiator ∙ Elite
Lim Kah Sin
REN38882
Negotiator ∙ Elite
Lim Kah Sin
REN38882
About Lim Kah Sin
Leveraging market knowledge and negotiation skills to deliver exceptional results. Your real estate success is my priority. Ready to make your real estate dreams a reality? Let's chat. Your dream home awaits.
6 years at IQI
75 transactions
23 properties on sale
Contact Lim Kah Sin
Lim Kah Sin Social Links
No social links available.
Lim Kah Sin's Service Locations
Lim Kah Sin's Service Locations
My Listings

Corner 3 Storey commercial Shop House
Jalan Abdul Rahman
₫ 12,713
Listed on October 25, 2024

INDERAPURA/ SG.SOI
JALAN KUANTAN -PEKAN
₫ 11,441,875,860
Listed on October 29, 2024

Double Storey Shop House
Lorong setali 112 ,Kuantan
₫ 5,085,278,160
Listed on December 5, 2019

Commercial Building, Kuantan Pahang
Jalan Tanjung Lumpur
₫ 19,070
Listed on October 28, 2024

Commercial Land Double Frontage :Main Road and Beach
Jalan Beserah Kuantan
₫ 34,961,287,350
Listed on December 9, 2019

Three Storey Terrace Shoplot
jalan Tanah Putih, Kuantan,Pahang
₫ 8,899,236,780
Listed on October 29, 2024

MH PLATINUM RESIDENCE, GOMBAK, SETAPAK
LEVEL 13 MH PLATINUM RESIDENCE, GOMBAK, SETAPAK.
₫ 3,496,128,735
Listed on November 18, 2024
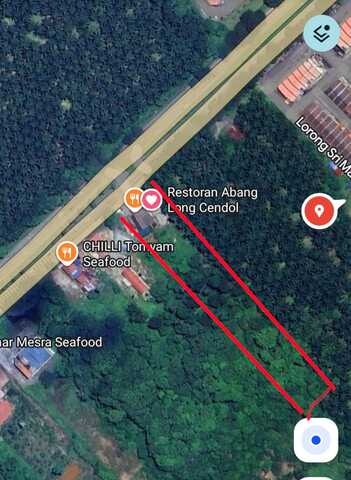
Agriculture Land
JALAN GAMBANG BATU 11 ,KUANTAN PAHANG.
₫ 10,806,216,090
Listed on August 9, 2026

Agricultural Land
Gebeng area
₫ 4,449,618,390
Listed on November 4, 2024

HOTEL
JALAN BUKIT UBI KUANTAN
₫ 69,922,574,700
Listed on October 19, 2019

TAMAN INDERAPURA KUANTAN
LORONG SERI INDERAPURA 8, TAMAN SERI INDERAPURA
₫ 1,906,979,310
Listed on October 25, 2024

Fock Wah apartment Kuantan
B315 2nd Floor Lorong Sekilau 22
₫ 1,589,149,425
Listed on October 28, 2024

INDERA MAHKOTA IM 14 DOUBLE STOREY SHOPLOT
LORONG IM14/31
₫ 4,131,788,505
Listed on October 29, 2024

DOUBLE STOREY SEMI-DETACHED HOUSE
JALAN KAMPUNG TENGAH kUANTAN
₫ 4,869,153,838
Listed on August 9, 2026

Sungai Karang Kuantan , Second lot from Main Road With Reserved Access Road.
Jalan Kuantan Bypass
₫ 16,844,983,905
Listed on October 28, 2024

SRI DAGANGAN BUISNESS CENTER
LRG.TUN ISMAIL 1
₫ 10,806,216,090
Listed on October 27, 2024
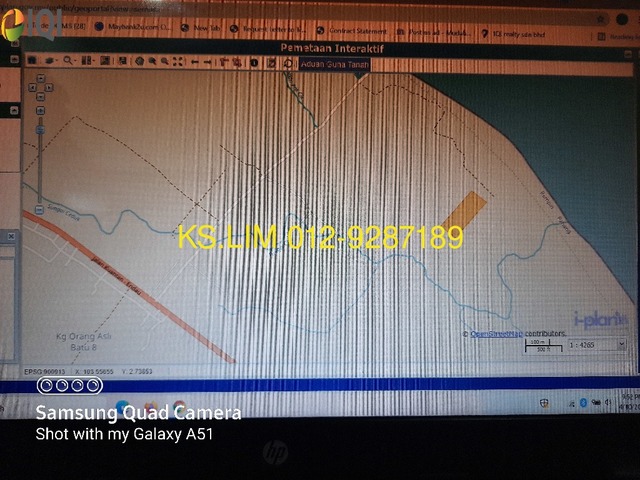
KUALA ROMPIN
BT.6 JALAN ROMPIN-ENDAU
₫ 3,305,430,804
Listed on October 29, 2024

Inderapura
Jalan Kuantan- Pekan
₫ 12,077,535,630
Listed on October 29, 2024

KOLEK COCONUT PLANTATION WITH A FEW DURIAN AND LEMON TREES
KOLEK PANCHING
₫ 6,356,597,700
Listed on October 28, 2024

J.DUPION CHERAS KUALA LUMPUR
1, JALAN SEMILANG TMN.TENAGA CHERAS KUALA LUMPUR
₫ 5,403,108,045
Listed on November 16, 2024

Industrial Land Gambang Kuantan ,Pahang
lot Jalan Gambang Kuantan, Pahang
₫ 14,620,174,710
Listed on November 4, 2024

Ground floor of 3 Storey Shop with Strata Title Kuantan Town Center.
Grd.floor Jalan Putra Square 2
₫ 3,813,958,620
Listed on November 30, 2019

Double Storey Corner Shoplot
jalan Gebeng 2/7
₫ 6,992,257,470
Listed on October 27, 2024
Our newly launched projects
Discover the real estate properties in and around Kuantan, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Large land area
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from ₫ 92,142,189,092
Listed on January 23, 2026
 Located in Bukit Minyak
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₫ 7,652,072,311
Listed on January 23, 2026
 Industrial project type
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₫ 31,878,337,466
Listed on January 23, 2026
 Spacious land area
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₫ 7,111,761,507
Listed on January 23, 2026
 Larger built-up area
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₫ 5,199,696,919
Listed on January 23, 2026
 Located in Nibong Tebal
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from ₫ 3,496,128,735
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
Hanoi Apartment Market Faces Resale Pressure Hanoi’s apartment market is entering a more cautious phase as resale pressure increases among investors who bought off-plan or during construction with short-term flipping strategies. After several years of strong price growth, market conditions have cooled. Capital gains are no longer guaranteed, while the end of mortgage grace periods is exposing some investors to higher floating interest rates and heavier repayment obligations. This is encouraging more owners to sell, with liquidity and debt reduction becoming a greater priority than maximising returns. According to market data cited in the report, asking prices at several Hanoi projects have already corrected from their previous peaks. Imperia Sola Park fell around 12.6%, Lumi Hanoi declined approximately 9.5%, while Kepler Land recorded an 8.6% correction. Market Shifts From Speculation to Liquidity The change marks an important shift in Vietnam’s residential market. Some leveraged investors are no longer holding properties in expectation of further short-term appreciation. Instead, they are looking to exit quickly, reduce debt exposure and, in some cases, accept losses. For genuine homebuyers and investors with stronger cash positions, this may create improved negotiating conditions in Hanoi’s secondary apartment market. Rather than competing in a rapidly rising market, buyers may now have greater scope to negotiate on properties where sellers are under financing pressure. Outlook Hanoi’s apartment market is likely to remain more selective and liquidity-driven in the near term. Resale pressure could continue to create opportunities for buyers who have sufficient cash and are willing to negotiate carefully. The key advantage is shifting towards financially prepared buyers, particularly those able to identify motivated sellers and acquire quality secondary-market units at prices below previous market peaks. The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
30 Jul, 2026
Vietnam Property Market Outlook 2026: Infrastructure Corridors Lead the Next Growth Cycle
Vietnam’s Housing Market Enters a Selective Reset Vietnam’s residential market entered August 2026 in a period of consolidation. Prices remain relatively firm, but transaction activity is slower as buyers become more selective and borrowing costs stay elevated. During Q2 2026, developers launched approximately 12,000 primary condominiums across the enlarged Ho Chi Minh City market and more than 4,000 units in Hanoi. However, luxury absorption remained below 30% in Ho Chi Minh City, while Hanoi’s take-up rate eased to around 20%. Inner-city primary prices reached approximately USD 5,400 to USD 9,500 per square metre. Pressure was more visible in the secondary market, where prices declined 5% to 8% in Ho Chi Minh City and by as much as 12% in parts of Hanoi. Floating mortgage rates of 13% to 16% are encouraging some owners to lower asking prices. However, the market has not experienced widespread distress, while the new land-price framework is helping maintain a floor under development costs and headline prices. Infrastructure Redirects Property Demand Vietnam has approximately 234 major infrastructure projects worth VND 3.4 quadrillion underway. These investments are shifting demand from crowded central districts towards better-connected suburban and regional corridors. In the south, growth is concentrating around the Ho Chi Minh City and Dong Nai corridor, supported by Long Thanh International Airport, new ring roads, expressways and Metro Line 1. Northern demand is moving towards Hanoi’s gateway districts and neighbouring Hung Yen and Bac Ninh. Da Nang is also showing stronger primary-market activity, supported by limited prime coastal supply. Outlook Vietnam’s next property cycle is expected to favour patience and careful asset selection rather than short-term speculation. With average gross rental yields near 3.85%, investment returns will depend increasingly on infrastructure-led capital appreciation. Legally clear projects with strong connectivity and genuine end-user demand should remain best positioned, particularly for buyers with sufficient holding power and a multi-year investment horizon. Download to see insights from other country marketsDownload
Vietnam Residential Market Enters a More Selective Cycle Vietnam’s residential market opened 2026 in a transition phase, with prices still rising but liquidity cooling. This suggests the market is moving away from easy speculative gains toward a more disciplined cycle. Residential prices rose around 12% year-on-year in Q1 2026, while liquidity fell nearly 40%. However, there was no sign of distress selling, pointing to a healthy reset rather than a sharp downturn. Primary condominium prices reached new highs across major cities. In Hanoi, average prices were around USD 3,950 per sqm, up 30% year-on-year. In post-merger Ho Chi Minh City, prices averaged around USD 3,900 per sqm, supported by new supply and limited premium stock. Supply also improved. Ho Chi Minh City recorded around 8,010 new condo launches, up 104% year-on-year. Yet affordability remains the key challenge, with much of the new supply priced above the level affordable to mass-market buyers. Strong Fundamentals, But Investors Are More Careful Vietnam’s underlying fundamentals remain supportive. The economy grew 8.02% in 2025, while real estate FDI reached USD 389.5 million in Q1 2026, representing around 7.2% of total inflows. However, investor behaviour is changing. Demand is now concentrating on projects with clear legal status, reliable construction progress and long-term value. Satellite locations such as Binh Duong and Ba Ria-Vung Tau are gaining attention as central city prices continue to stretch. Outlook Vietnam’s property market is expected to remain attractive, but more selective. With average gross rental yields at around 3.85%, the market is less of a pure income play and more of a capital appreciation and infrastructure-led growth story. Buyers with strong holding power, careful project selection and a long-term view are likely to be better positioned than short-term speculators. Download to see insights from other country marketsDownload
Vietnam's property market continues to present a mixed but encouraging picture in 2026. While Hanoi's retail property sector is undergoing a period of adjustment, Ho Chi Minh City's residential market remains resilient, supported by limited supply, strong demand, and improving infrastructure connectivity. The contrasting performance between the two cities highlights the importance of market selection as investors navigate Vietnam's evolving real estate landscape. Hanoi's Retail Market Faces Adjustment Hanoi's prime retail corridors continue experiencing pressure as changing consumer behaviour and the growth of e-commerce reshape demand for traditional street-front retail space. Vacancy levels have become more noticeable in several key commercial areas as landlords and tenants adjust to shifting market conditions. The correction has also impacted retail-linked residential assets, with demand softening compared to previous years. Rental rates for townhouses across several submarkets have declined from their recent peaks, reflecting a more cautious operating environment for retailers and property owners. Despite these short-term challenges, Hanoi remains an important commercial centre, and the current adjustment may create opportunities for well-capitalised investors focused on long-term value. Ho Chi Minh City Continues to Lead Residential Growth In contrast, Ho Chi Minh City's residential market remains one of Vietnam's strongest-performing sectors. Limited new supply, improving infrastructure, and sustained buyer demand continue supporting price growth across the city. Average apartment prices in central Ho Chi Minh City reached new highs during the first quarter of 2026, driven largely by high-end and luxury developments. The shortage of mid-market housing options has also contributed to upward pressure on prices. Growth is not limited to the city centre. Formerly independent areas such as Binh Duong and Ba Ria-Vung Tau continue benefiting from expanding infrastructure and stronger regional connectivity, supporting residential demand and investment activity throughout the wider metropolitan area. Infrastructure Continues to Support Long-Term Demand One of the strongest themes across Vietnam's property market remains infrastructure-led growth. Continued investment in transportation networks and urban expansion projects is improving accessibility between major economic centres and surrounding residential markets. As connectivity improves, suburban and emerging growth areas are becoming increasingly attractive to both homebuyers and investors seeking more affordable entry points and long-term appreciation potential. Outlook Vietnam's property market is expected to remain supported by urbanisation, infrastructure investment, and long-term housing demand. While Hanoi's retail sector may continue adjusting to changing consumer trends, Ho Chi Minh City's residential market is likely to remain resilient due to limited supply and strong buyer interest. For investors, opportunities increasingly lie in understanding the differing dynamics between cities and focusing on markets supported by strong economic and infrastructure fundamentals. Download to see insights from other country marketsDownload
Ready to get started?
Get in touch now.