

Team Leader ∙ Dreammakerz
Alan Tan
PEA3780
Team Leader ∙ Dreammakerz
Alan Tan
PEA3780
About Alan Tan
Leveraging market knowledge and negotiation skills to deliver exceptional results. Your real estate success is my priority. Ready to make your real estate dreams a reality? Let's chat. Your dream home awaits.
1 year at IQI
56 transactions
40 properties on sale
15 properties on rent
Contact Alan Tan
Alan Tan Social Links
Alan Tan's Service Locations
Alan Tan's Service Locations
My Listings
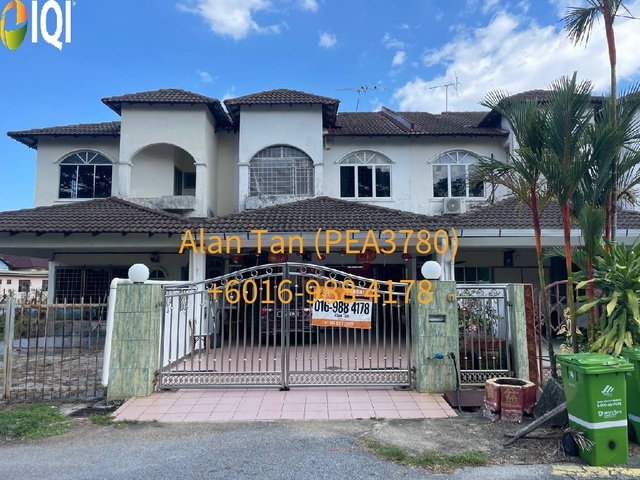
BUKIT SETONGKOL JAYA
BUKIT SETONGKOL JAYA
₱ 8,156,700
Listed on May 18, 2026

Kota Rawson
Lorong IM 21
₱ 7,156,350
Listed on November 20, 2024
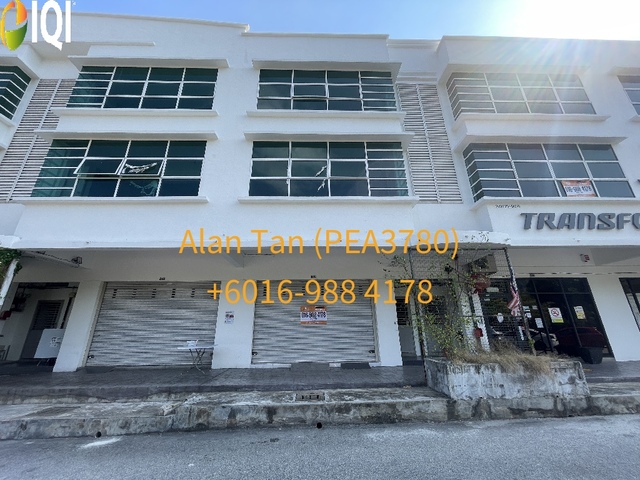
AIR PUTIH, KUANTAN (Opposite Andorra Peak)
AIR PUTIH, KUANTAN (Opposite Andorra Peak)
₱ 46,170 /month
Listed on April 2, 2026

Sungai Karang Darat
Sungai Karang, Kuantan
₱ 5,386,500
Listed on February 3, 2025
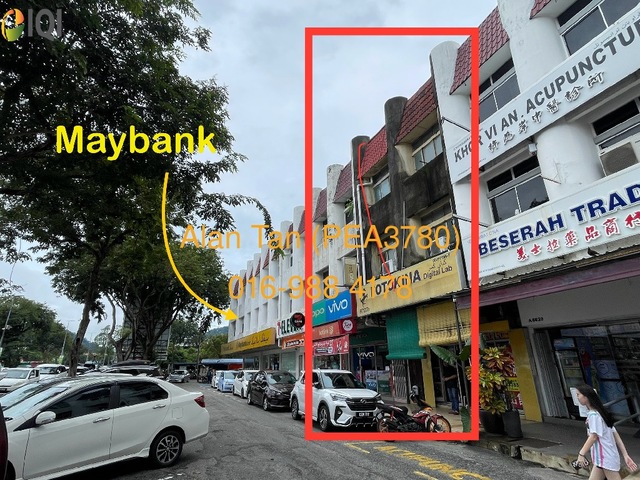
Jalan Beserah (same row with Maybank / KK Mart/ Guardian)
Jalan Beserah, Kuantan (same row with Maybank / KK Mart/ Guardian)
₱ 18,160,200
Listed on December 8, 2024
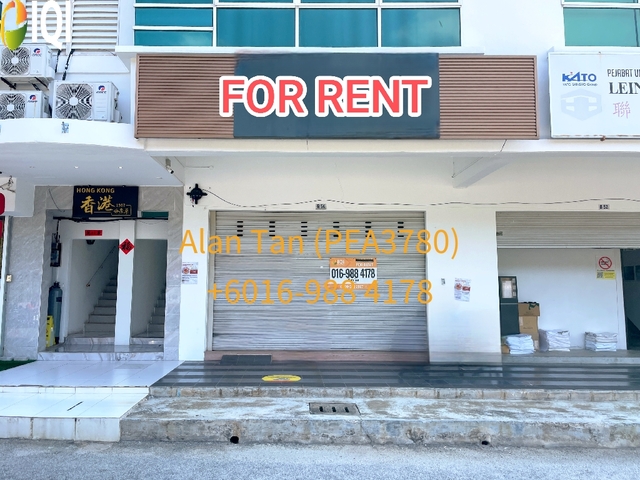
AIR PUTIH, KUANTAN (Opposite Andorra Peak)
AIR PUTIH, KUANTAN (Opposite Andorra Peak)
₱ 46,170 /month
Listed on April 2, 2026
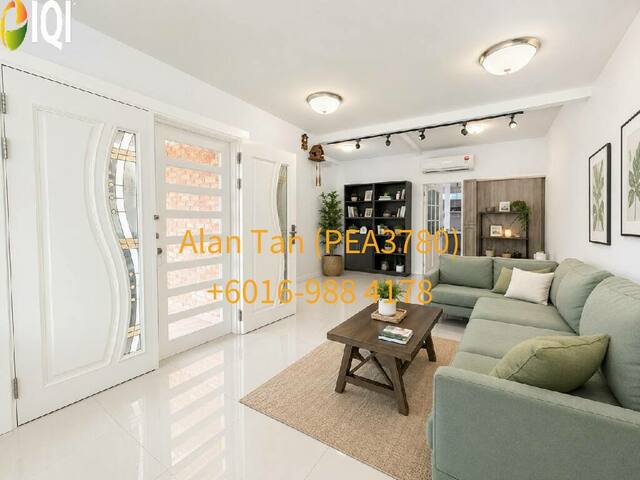
KUBANG BUAYA
KUBANG BUAYA
₱ 11,080,800
Listed on July 10, 2026
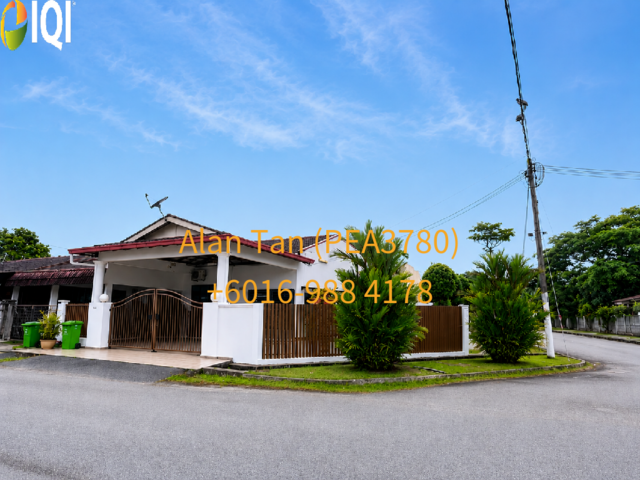
BUKIT SETONGKOL JAYA
BUKIT SETONGKOL JAYA
₱ 7,387,200
Listed on May 23, 2026
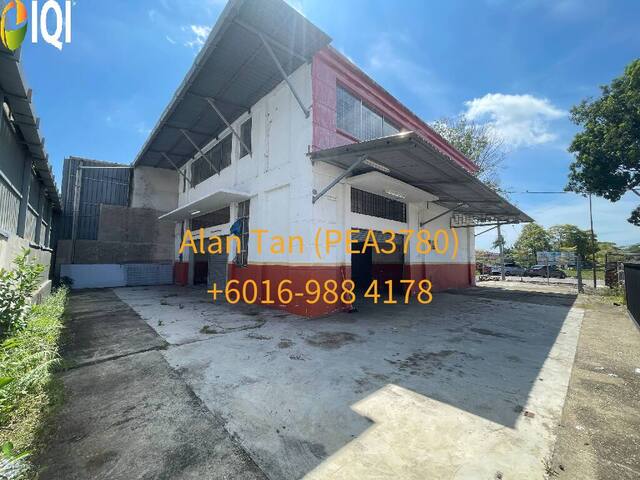
INDERA MAHKOTA 3, KUANTAN
INDERA MAHKOTA 3
₱ 100,035 /month
Listed on August 14, 2026
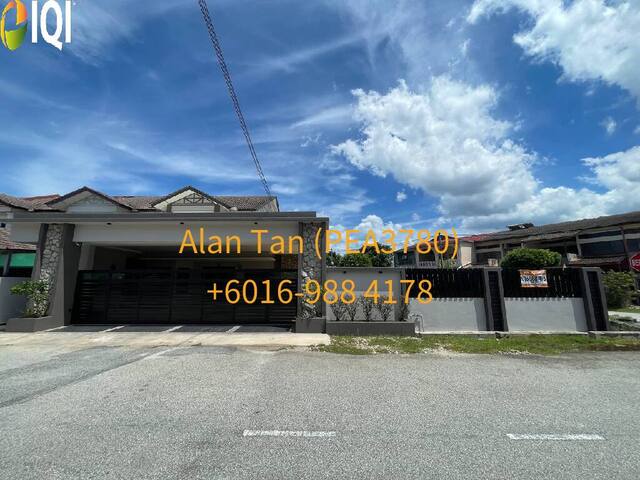
ALOR AKAR (Renovated Big Corner House)
ALOR AKAR
₱ 18,160,200
Listed on August 28, 2026
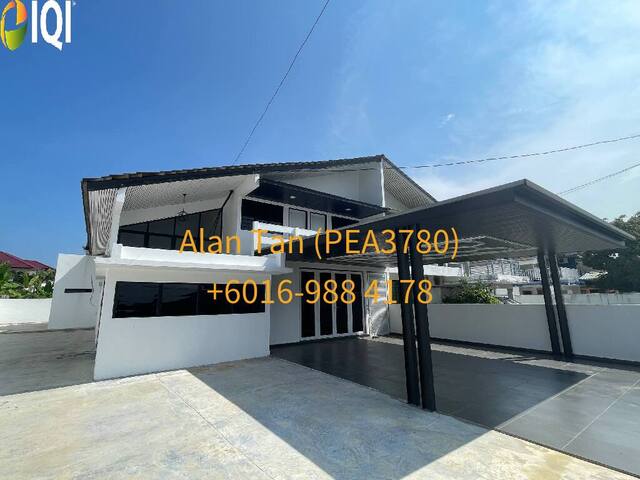
TOK SIRA, KUANTAN
TOK SIRA, KUANTAN
₱ 19,699,200
Listed on August 12, 2026
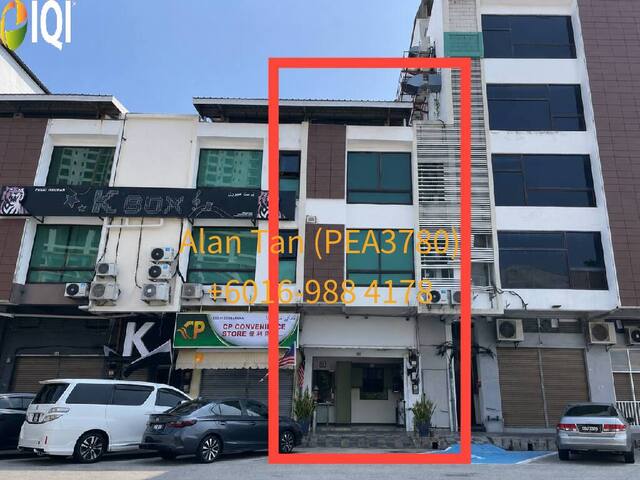
JALAN GAMBUT @ KUANTAN
JALAN GAMBUT
₱ 21,546,000
Listed on September 2, 2026
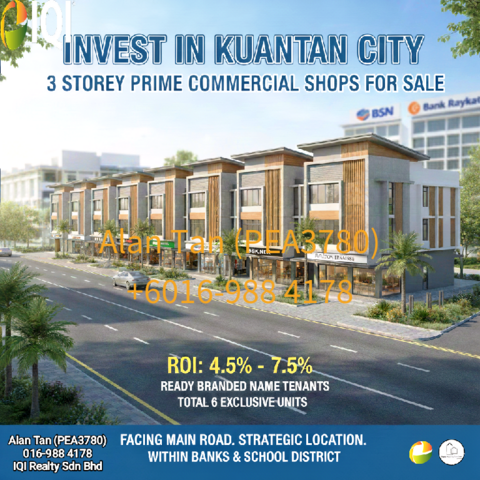
Indera Mahkota
Great ROI Investment! WITH READY TENANT! Kuantan city
₱ 13,235,400
Listed on December 6, 2025
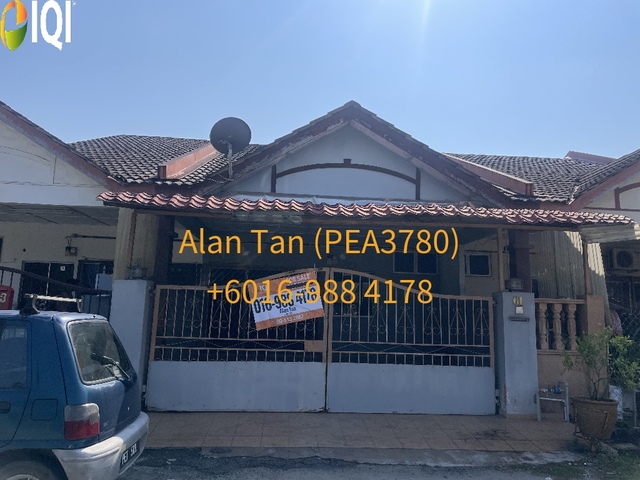
KAMPUNG CHENGAL LEMPONG
CHENGAL LEMPONG BARU, KUANTAN
₱ 4,232,250
Listed on August 3, 2025
Indera Mahkota
INDERA MAHKOTA
₱ 30,780 /month
Listed on May 6, 2026
BUKIT UBI, BANDAR KUANTAN
BUKIT UBI - BANDAR KUANTAN
₱ 27,702 /month
Listed on April 29, 2026
INDERA MAHKOTA 5
INDERA MAHKOTA 5
₱ 10,003,500
Listed on July 9, 2026
INDERA MAHKOTA 8
INDERA MAHKOTA 8
₱ 8,464,500
Listed on September 1, 2026
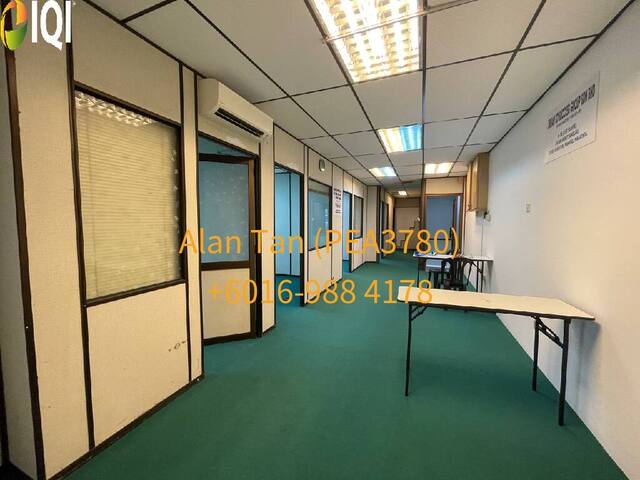
BUKIT SEKILAU
BUKIT SEKILAU (FACING MAIN ROAD)
₱ 15,390 /month
Listed on August 18, 2026
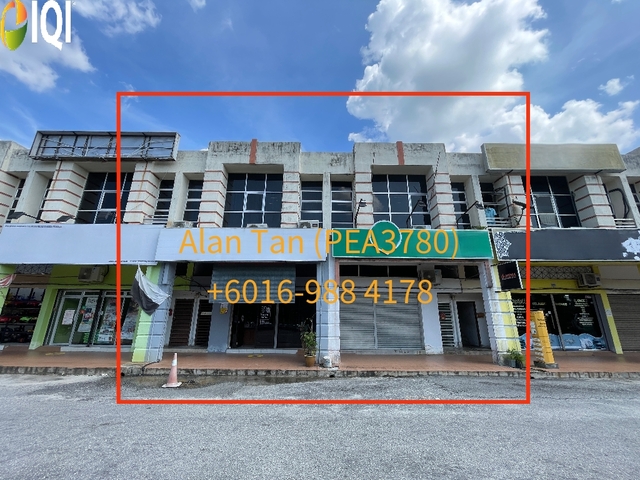
Indera Mahkota
Indera Mahkota 8 (IM 8) @ Kuantan
₱ 11,542,500
Listed on November 4, 2025
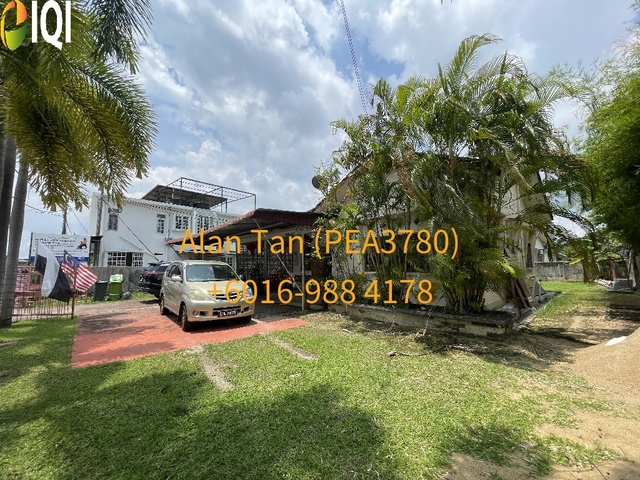
ALOR AKAR
Alor Akar / Kuantan Garden @ Kuantan
₱ 10,003,500
Listed on September 23, 2025
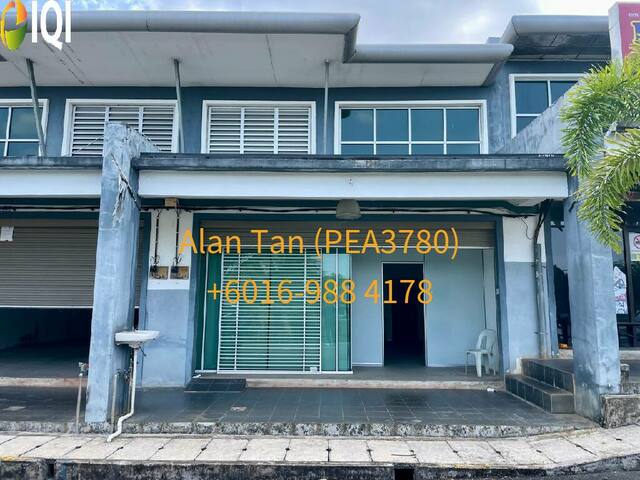
Indera Mahkota
INDERA MAHKOTA
₱ 30,780 /month
Listed on May 6, 2026
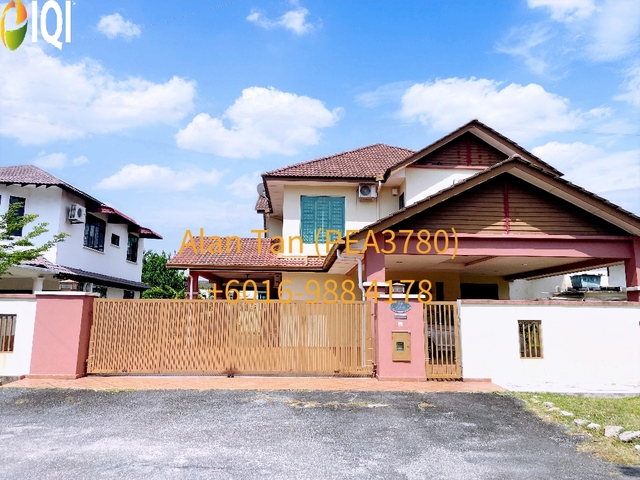
ALOR AKAR, KUANTAN
ALOR AKAR, KUANTAN
₱ 15,390,000
Listed on April 29, 2026
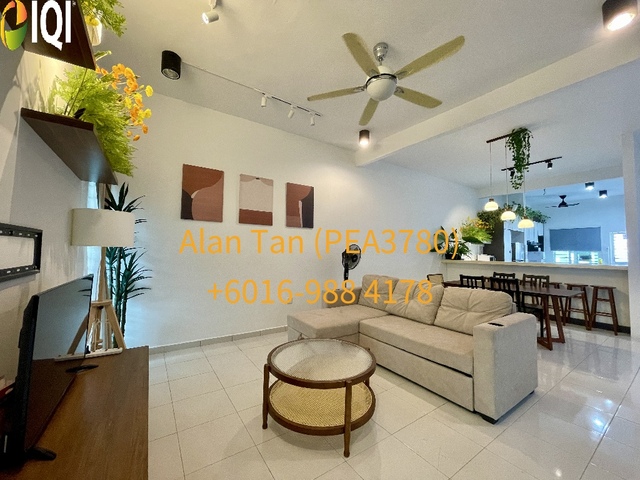
Bandar Putra Kuantan
Bandar Putra, Kuantan
₱ 8,002,800
Listed on January 20, 2026
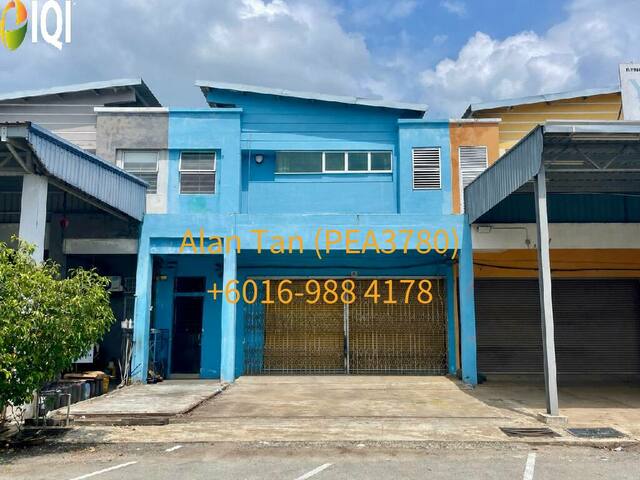
TANAH PUTIH (BATU 3, KUANTAN)
TANAH PUTIH (BATU 3, KUANTAN)
₱ 11,234,700
Listed on June 18, 2026
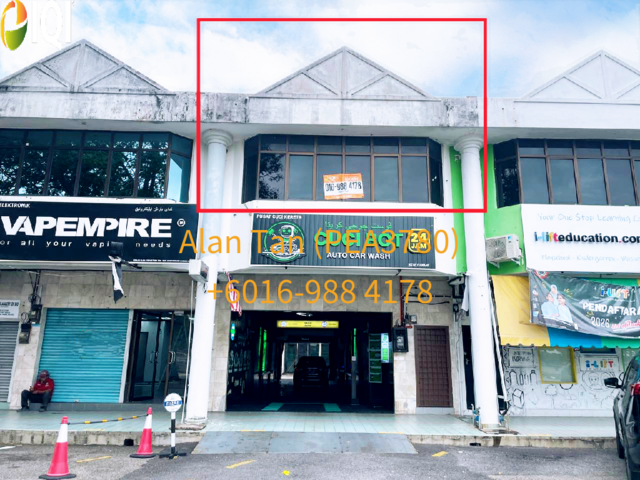
Bukit Sekilau
Bukit Sekilau, Kuantan
₱ 18,468 /month
Listed on March 3, 2026

GALING
Air Putih / Galing (Near Petronas & Old Town cafe)
₱ 11,542,500
Listed on November 24, 2024

Galing / Air Putih, Kuantan (NEW HOUSE)
Galing / Air Putih @ Kuantan
₱ 10,465,200
Listed on February 13, 2025
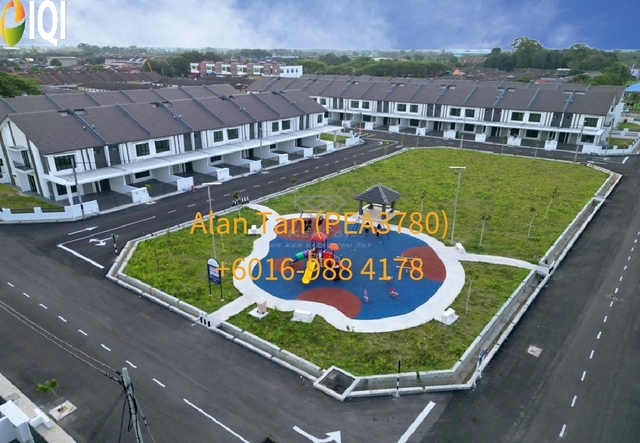
Taman Tas Perdana
Taman Tas Perdana (NEW HOUSES!!)
₱ 6,600,463
Listed on March 24, 2026

Bukit Setongkol, Kuantan
Bukit Setongkol, Kuantan
₱ 4,847,850
Listed on February 11, 2025
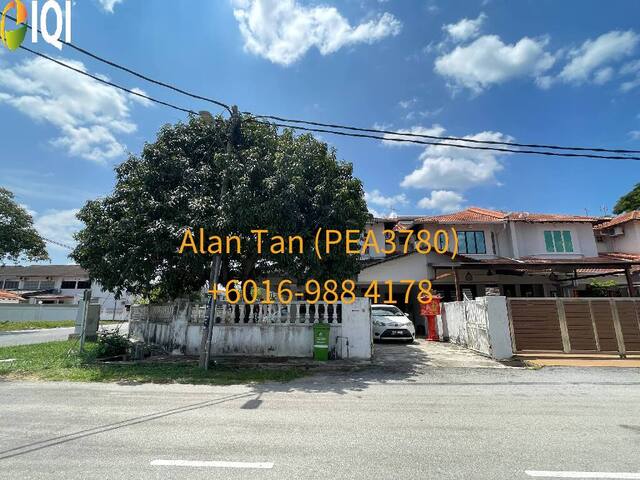
KUBANG BUAYA, KUANTAN
KUBANG BUAYA, KUANTAN
₱ 11,080,800
Listed on August 5, 2026
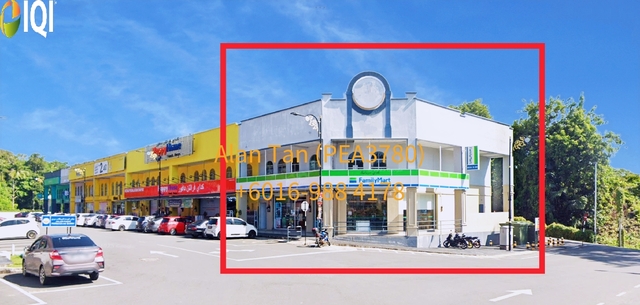
KUALA LIPIS, PAHANG
PUSAT PERNIAGAAN BARRY
₱ 30,780,000
Listed on March 6, 2026
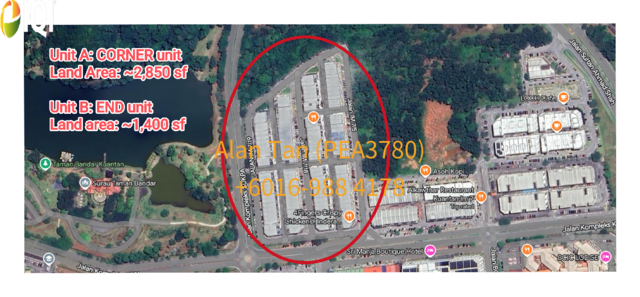
Indera Mahkota 7
Indera Mahkota 7, Kuantan
₱ 56,943 /month
Listed on July 11, 2025
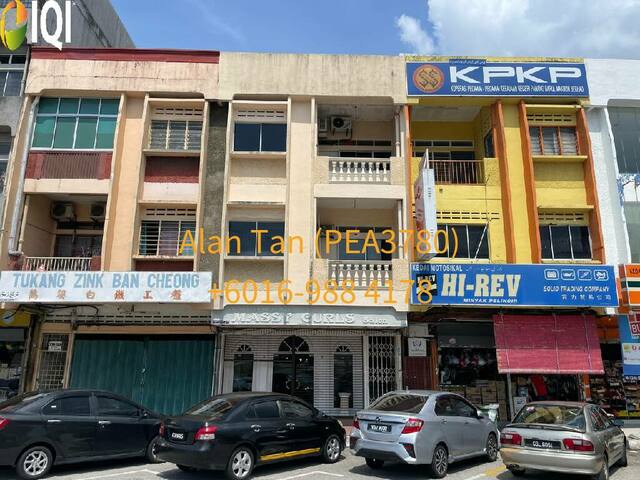
Kuantan City Centre
Jalan Penjara, Kuantan
₱ 13,543,200
Listed on May 7, 2026
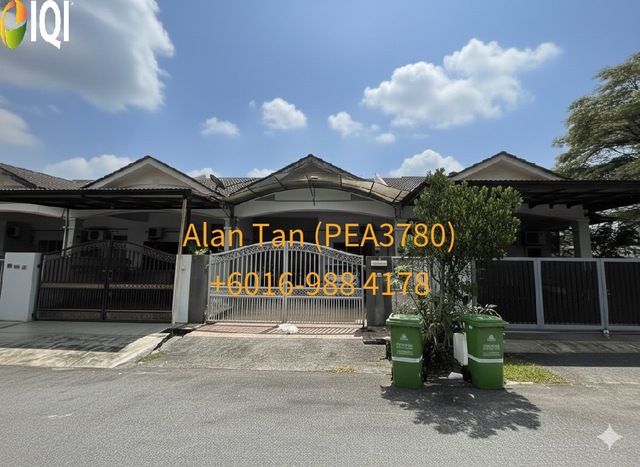
AIR PUTIH
Air Putih / Galing, Kuantan
₱ 5,463,450
Listed on December 6, 2025
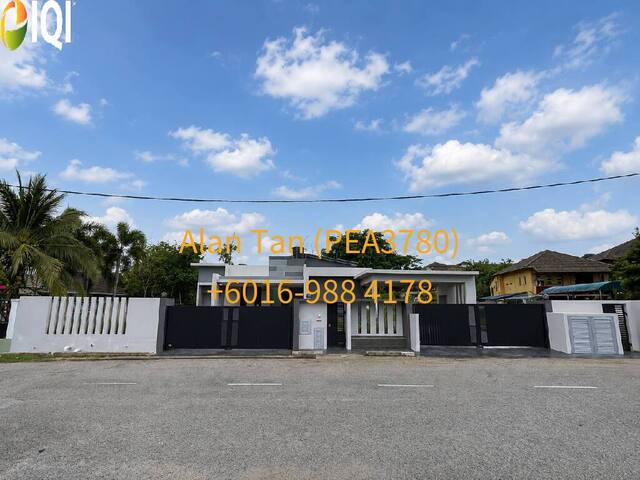
INDERA MAHKOTA 5
INDERA MAHKOTA 5
₱ 35,397 /month
Listed on July 17, 2026
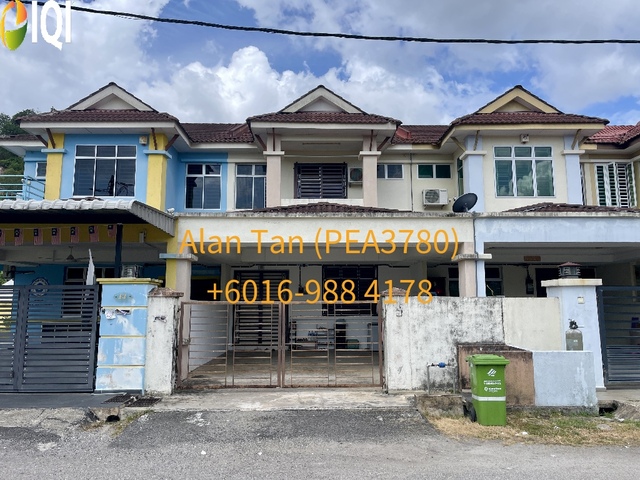
Taman Shahzan
Shahzan IM 3, Kuantan
₱ 6,540,750
Listed on January 28, 2026
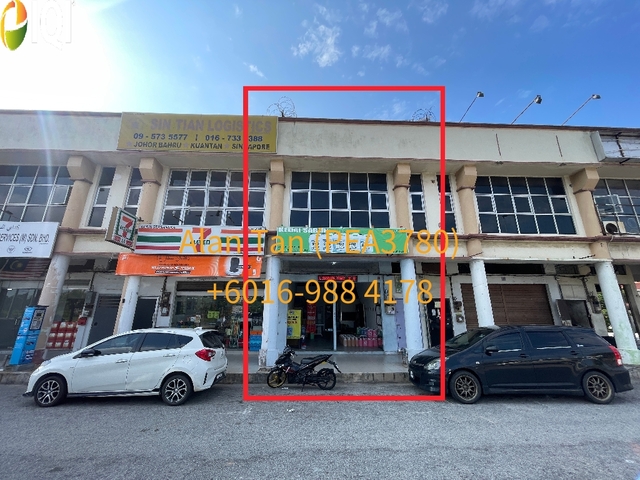
Indera Mahkota 16 / Kuantan By-pass
Indera Mahkota 16 / Kuantan By-pass
₱ 9,541,800
Listed on March 2, 2026
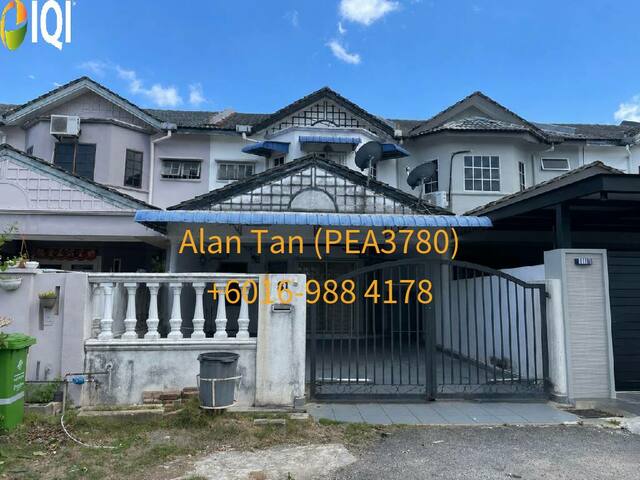
AIR PUTIH, KUANTAN
AIR PUTIH, KUANTAN
₱ 6,156,000
Listed on June 27, 2026
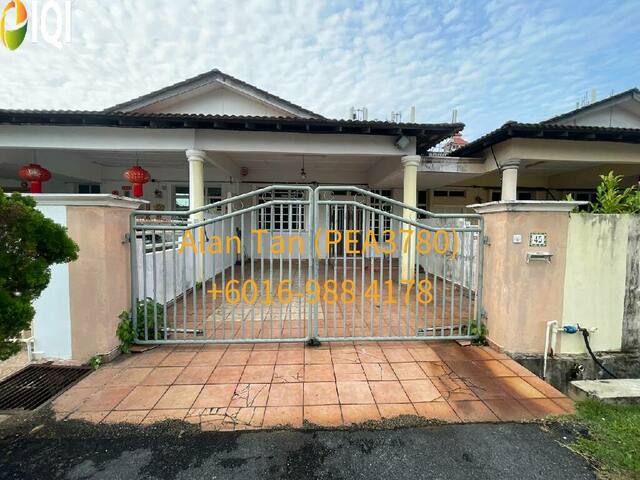
BUKIT SEKILAU (KUANTAN CITY CENTRE)
BUKIT SEKILAU (KUANTAN CITY CENTRE)
₱ 5,540,400
Listed on June 18, 2026
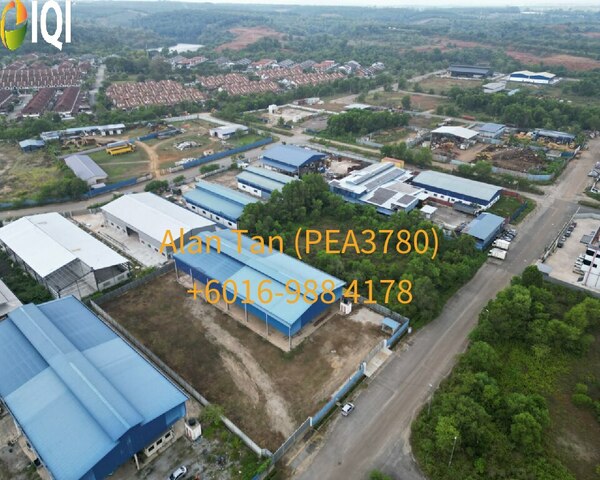
KAWASAN PERINDUSTRIAN SEMAMBU
KAWASAN PERINDUSTRIAN SEMAMBU
₱ 230,850 /month
Listed on March 30, 2026
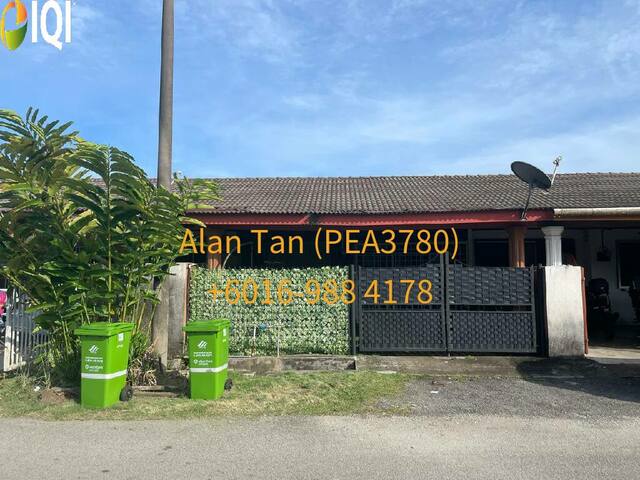
KAMPUNG PADANG
KAMPUNG PADANG
₱ 3,047,220
Listed on July 9, 2026
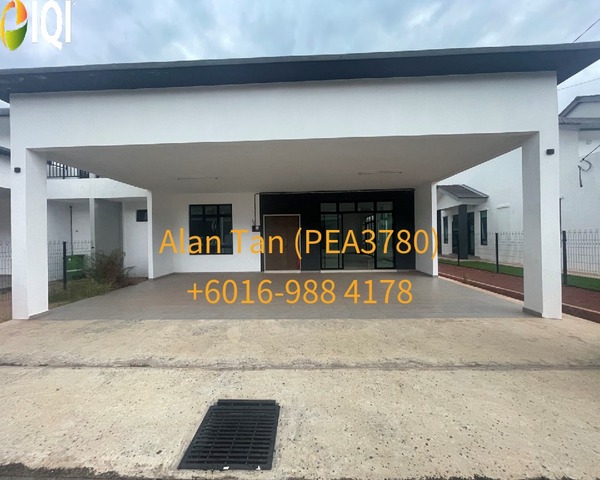
Majestic 2 @ SpringVale KotaSAS 7
Majestic 2 @ KotaSAS, Kuantan (Indera Mahkota)
₱ 11,819,520
Listed on April 30, 2026
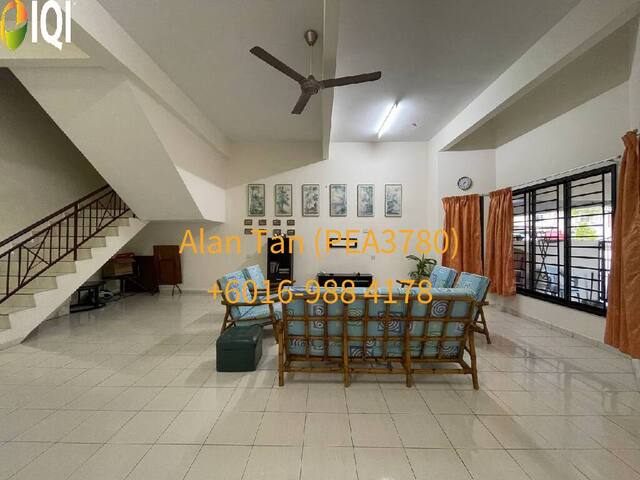
BUKIT SETONGKOL JAYA
BUKIT SETONGKOL JAYA
₱ 27,702 /month
Listed on August 18, 2026
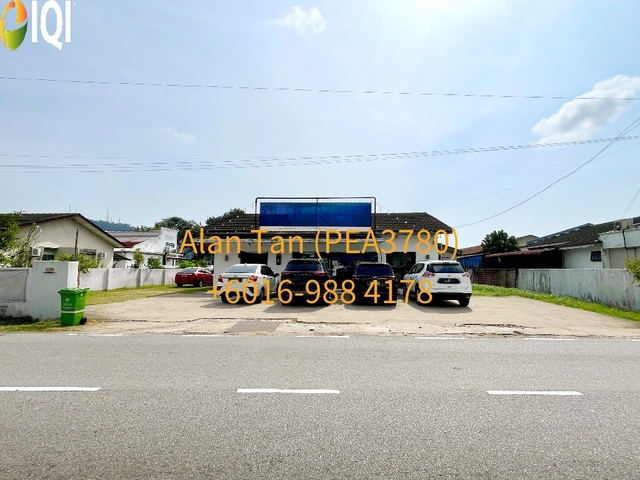
ALOR AKAR
Alor Akar, Kuantan
₱ 15,390,000
Listed on January 23, 2026

Bukit Pelindung (near Teluk Cempedak Beach, Kuantan)
Bukit Pelindung (near Teluk Cempedak Beach, Kuantan)
₱ 13,543,200
Listed on March 18, 2025
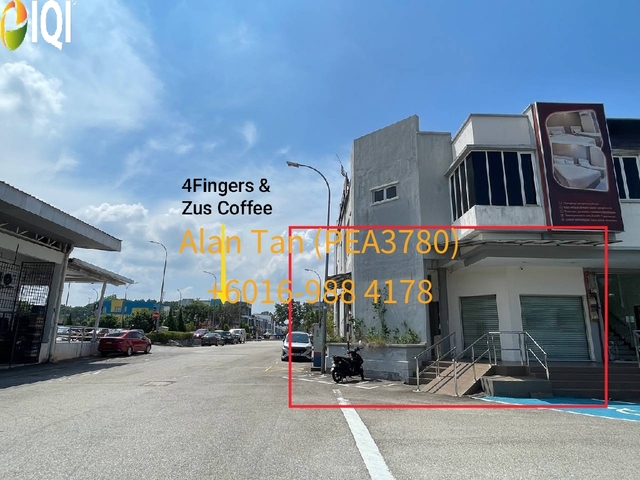
BANDAR INDERA MAHKOTA, IM 7, Kuantan
INDERA MAHKOTA 7
₱ 58,482 /month
Listed on May 16, 2026
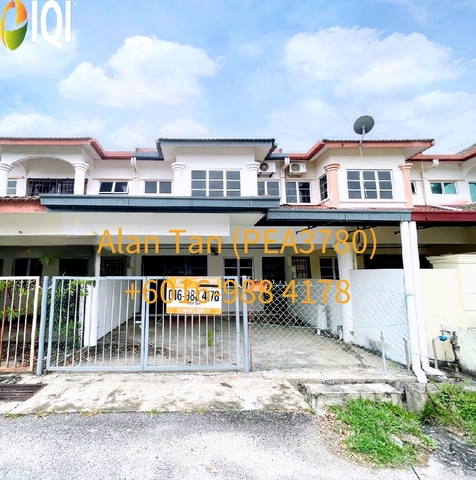
Bukit Setongkol Jaya
BUKIT SETONGKOL JAYA
₱ 6,617,700
Listed on May 21, 2026
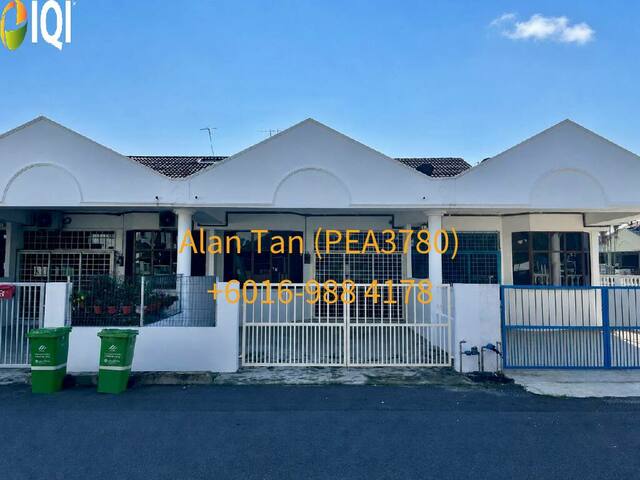
SERI SETALI / AIR PUTIH
SERI SETALI / AIR PUTIH
₱ 5,540,400
Listed on July 8, 2026
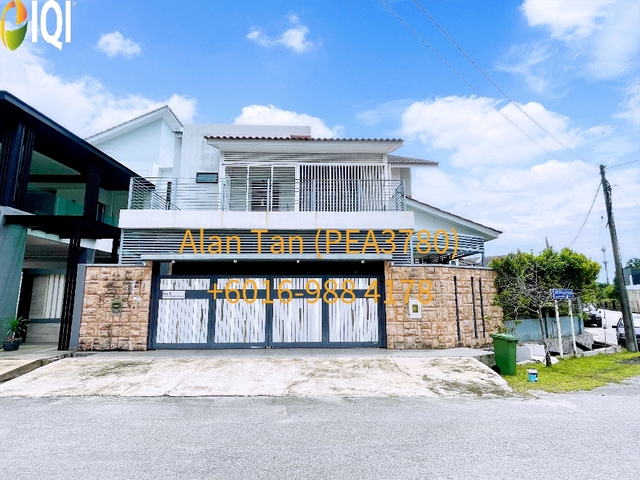
BUKIT SETONGKOL PERDANA
Bukit Setongkol Perdana, Kuantan
₱ 15,082,200
Listed on February 24, 2026
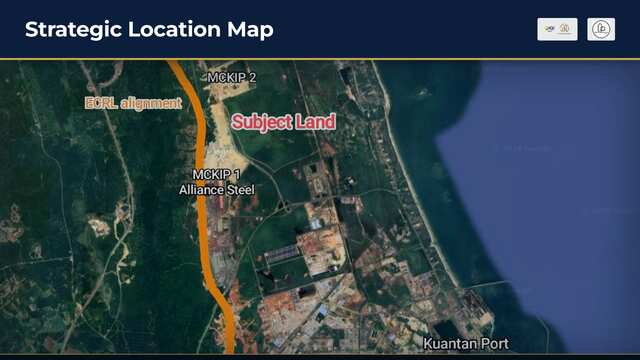
KAWASAN PERINDUSTRIAN GEBENG
KAWASAN PERINDUSTRIAN GEBENG
₱ 3,385,800,000
Listed on March 3, 2026
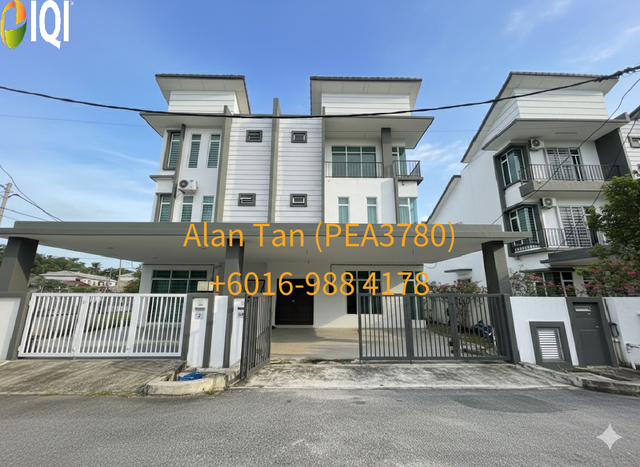
2.5 Storey NEW Semi-D House @ Kuantan (Air Putih)
Air Putih, Kuantan
₱ 14,312,700
Listed on November 19, 2025
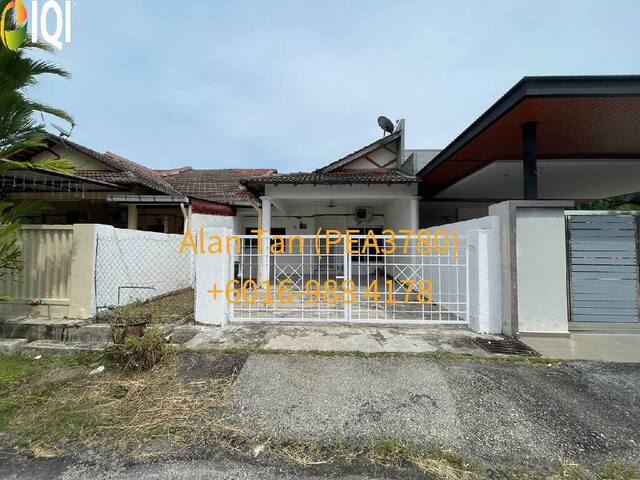
Indera Mahkota 8
Indera Mahkota 8, IM 8
₱ 4,155,300
Listed on July 17, 2026

Haji Ahmad @ Kuantan (near East Coast Mall)
Haji Ahmad @ Kuantan (near East Coast Mall)
₱ 18,468 /month
Listed on March 4, 2025
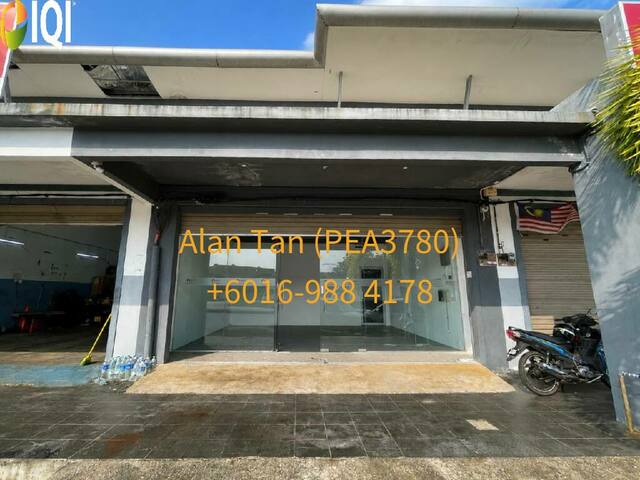
Indera Mahkota
INDERA MAHKOTA
₱ 24,624 /month
Listed on May 6, 2026
Our newly launched projects
Discover the real estate properties in and around Kuantan, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Large land area
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from ₱ 223,086,053
Listed on January 23, 2026
 Varied built-up sizes
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 18,526,482
Listed on January 23, 2026
 Industrial project type
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 77,180,850
Listed on January 23, 2026
 Spacious land area
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 17,218,332
Listed on January 23, 2026
 Larger built-up area
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 12,589,020
Listed on January 23, 2026
 Large land area
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from ₱ 8,464,500
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
Industrial and Commercial Recovery Gains Ground The Philippine property market entered the second half of 2026 with recovery strengthening across industrial, commercial and residential real estate. Industrial property remains the standout segment. First-half merchandise exports reached US$46.72 billion, the strongest performance since 1991, supported by electronics demand linked to the global AI supply chain. This momentum is feeding into a 1,200-hectare industrial land pipeline for 2026 to 2028, while industrial rents have increased 45% since 2019. New demand from EV and battery manufacturers is also supporting the sector. Metro Manila’s office vacancy remained stable at 19%, despite softer leasing volumes, while flexible workspace take-up doubled year-on-year. Retail vacancy is expected to fall below 10% by year-end, while around 3,100 new hotel rooms are scheduled for delivery in 2026. Residential Buyers Still Hold the Advantage The residential market remains firmly buyer-favourable. Inflation eased to 6.2% in July, marking a third consecutive month of improvement, while the BSP was expected to maintain its policy rate at 4.75%. Developers continue to compete for buyers through extended payment terms, rent-to-own structures and effective discounts of 3% to 12%. At the same time, future condominium supply is tightening sharply. Annual completions are expected to average around 3,600 units through 2028, down 72% from the 2017 to 2019 average. Outlook The Philippines is entering a potentially important transition period. Improving inflation, the prospect of lower borrowing costs and a shrinking condominium pipeline could support stronger residential absorption into 2027. Meanwhile, industrial assets remain the strongest structural growth story, supported by exports, manufacturing and infrastructure demand. For investors, the second half of 2026 offers an opportunity to focus on quality industrial assets, flexible commercial space and competitively priced residential properties before financing conditions improve further. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Inflation Eases as Market Conditions Improve The Philippines property market entered the second half of 2026 with a gradually improving economic outlook. Inflation declined for a second consecutive month, falling from 7.2% in April to 6.4% in June. Lower fuel and transport costs supported the improvement, while monthly inflation recorded its first decline in a year at -0.3%. The Bangko Sentral ng Pilipinas raised its policy rate to 4.75%, but inflation is expected to ease further through 2028. Economic growth is also forecast to strengthen from 2.8% in Q1 2026 to 4.4% for the full year, supporting future consumption, investment and property demand. Industrial Property Offers the Strongest Prospects Metro Manila condominiums remain a buyer’s market, creating opportunities for buyers seeking discounted properties. New condominium completions are expected to average only 3,600 units annually from 2026 to 2028, significantly below the 13,000-unit annual average recorded between 2017 and 2019. This lower supply pipeline could gradually reduce excess inventory. Developer incentives, strong overseas Filipino worker remittances and projected national price appreciation of 25% to 35% by 2031 may support long-term residential demand. Metro Manila’s office vacancy rate improved to 19%, supported by limited new supply and demand beyond the business process outsourcing sector. Retail vacancy is also expected to fall below 10% as household spending recovers. Industrial property remains the strongest segment, led by Central Luzon and the Clark corridor. Rising rents, logistics improvements, e-commerce growth and demand for energy-resilient facilities continue to strengthen investment fundamentals. Outlook Industrial and Clark corridor assets offer the strongest risk-adjusted opportunities. Selected CBD offices, retail properties and discounted condominiums also present improving prospects. Investors should remain selective, prioritising quality assets, strong locations and longer holding periods while monitoring inflation, electricity costs and geopolitical risks. Juwai IQI Newsletter August 2026Download
Philippines Real Estate Shows Stronger Recovery Signals The Philippines property market is entering the second half of 2026 with improving momentum. The US-Iran ceasefire and reopening of the Strait of Hormuz have helped stabilise global oil markets, leading to major fuel rollbacks in the Philippines. This is easing pressure on household budgets and business costs, while also supporting buyer confidence. At the same time, the proposed Japan-Philippines petroleum reserve partnership strengthens the country’s long-term energy security outlook. The residential market remains selective. Metro Manila condominiums are still a buyer’s market, with around 74,000 to 75,300 unsold units. However, developer discounts, rent-to-own schemes and longer payment terms are creating attractive entry opportunities. Supply is also expected to tighten, with only about 3,600 new condo units annually from 2026 to 2028, far below the previous peak average of 13,000 units. Regional markets such as Cavite, Laguna, Cebu, Iloilo and Davao remain stronger performers, with projected annual appreciation of 5% to 7%. Industrial and Commercial Segments Lead Growth Industrial and logistics remain the strongest investment theme. The New Clark City industrial hub is reinforcing the Clark-Pampanga corridor as a key manufacturing and logistics destination, while industrial rents have risen 45% since 2019. Commercial property is also improving. Office demand rose 70% year-on-year in Q1 2026, supported by BPO and IT-BPM expansion. Retail vacancy is expected to fall below 10% by end-2026, while hospitality is benefiting from flight surcharge cuts and route restoration. Outlook The Philippines market is not without challenges, but its fundamentals remain strong. With 115 million people, record OFW remittances, infrastructure expansion and improving energy stability, H2 2026 could mark a clearer recovery phase. Industrial assets, Clark-linked logistics, regional residential corridors and prime income-generating assets are likely to remain the best-positioned opportunities. Download to see insights from other country marketsDownload
The Philippines property market faced a more challenging environment in early 2026 as inflation, higher interest rates, and rising living costs weighed on consumer sentiment and investment activity. While some sectors remain under pressure, industrial and logistics real estate continues to stand out as the market's strongest-performing segment. Residential Market Remains Challenging The residential sector continues to face headwinds from higher borrowing costs and affordability concerns. A large inventory of unsold condominium units, combined with rising mortgage rates, has slowed buyer activity across several urban markets. Despite these challenges, demand remains relatively resilient in regional growth centres and master-planned transit-oriented communities, where long-term infrastructure improvements continue to support buyer interest. End-users remain focused on affordability, connectivity, and long-term value rather than speculative purchases. Commercial Sector Shows Mixed Recovery The commercial property market is gradually recovering, although performance remains uneven across sectors. Prime office locations continue to attract demand, particularly in established business districts where vacancy rates are expected to improve. Retail activity is also showing signs of recovery, supported by experiential retail concepts and international brands. However, the hospitality sector continues to face challenges as tourism recovery remains slower than expected in some areas. Industrial and Logistics Lead Growth Among all property sectors, industrial and logistics real estate remains the strongest performer. Continued investment in manufacturing, warehousing, and logistics infrastructure is supporting demand for industrial space, particularly within strategic growth corridors. The development of New Clark City and the Clark-Pampanga corridor continues to strengthen the region's position as a key industrial and logistics hub. Rising industrial rents and ongoing investment commitments highlight the sector's growing importance within the country's long-term economic development strategy. Outlook While inflation, interest rates, and affordability concerns may continue creating short-term challenges, the Philippines' long-term property fundamentals remain intact. Supported by infrastructure investment, urbanisation, and demographic growth, the market continues to offer opportunities for investors focused on long-term value. Industrial and logistics assets, along with strategically located commercial and residential developments, are expected to remain among the most resilient sectors through the remainder of 2026. Download to see insights from other country marketsDownload
Ready to get started?
Get in touch now.