

Leader ∙ Elite
Windz Neom
REN28801
Leader ∙ Elite
Windz Neom
REN28801
About Windz Neom
I'm striving for excellence in the property industry. With my 9 years of Real Estate experiences, I would definitely give you the best service ever for your real estate matters. One of my favourite Quote - Service Above Self !My mission is to put clients’ interests above my own, providing the highe... I'm striving for excellence in the property industry. With my 9 years of Real Estate experiences, I would definitely give you the best service ever for your real estate matters. One of my favourite Quote - Service Above Self !My mission is to put clients’ interests above my own, providing the highest level of HONESTY and EXPERTISE. My vision is to Provides an EXCELLENT & CONSISTENT customer experience 100% of the time. Be a PROFESSIONAL advisor that DIFFERENT from the rest.
2 years at IQI
39 properties on sale
13 properties on rent
Contact Windz Neom
Windz Neom Social Links
Windz Neom's Service Locations
Windz Neom's Service Locations
My Listings
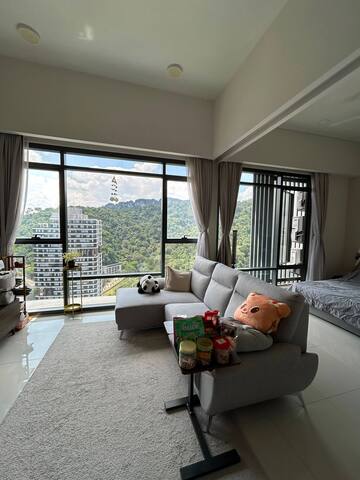
The Ridge @ KL East (Residensi Rabung KL Timur)
PERSIARAN MELATI KUARZA
₱ 38,281 /month
Listed on July 23, 2026
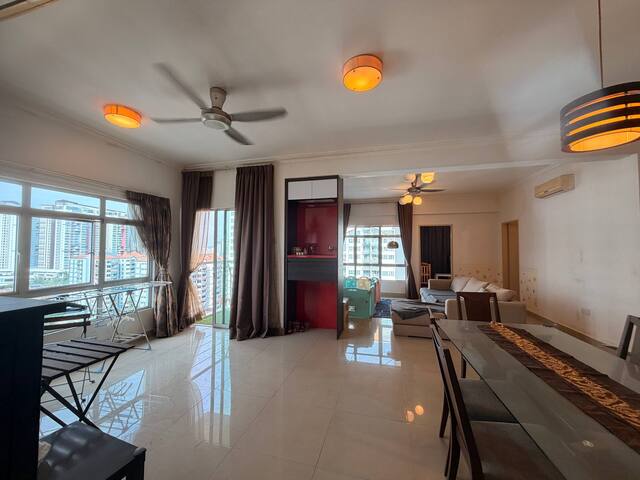
Residensi Desa
Jalan 1/127a, Kuchai Lama
₱ 8,268,642
Listed on July 15, 2026
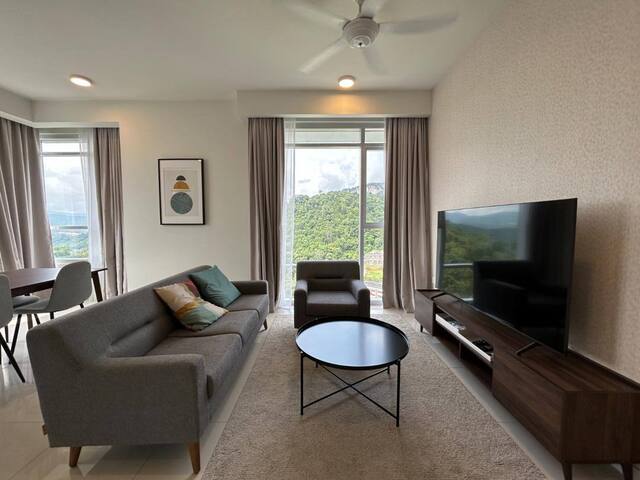
The Ridge @ KL East (Residensi Rabung KL Timur)
PERSIARAN MELATI KUARZA
₱ 48,999 /month
Listed on July 27, 2026
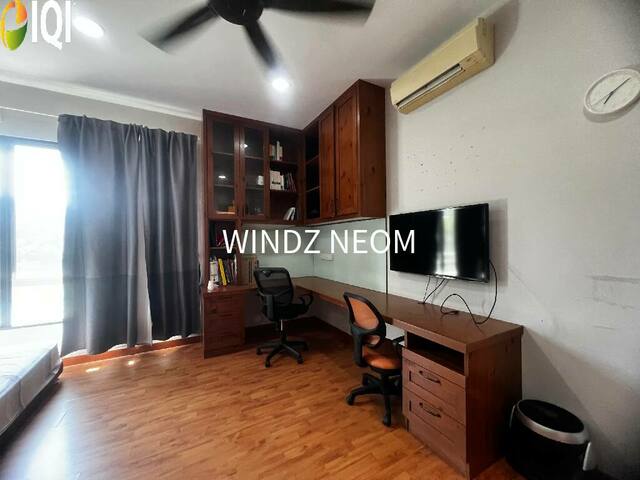
Kinrara Hills
Jalan Kinrara 6
₱ 45,936,900
Listed on January 2, 2026
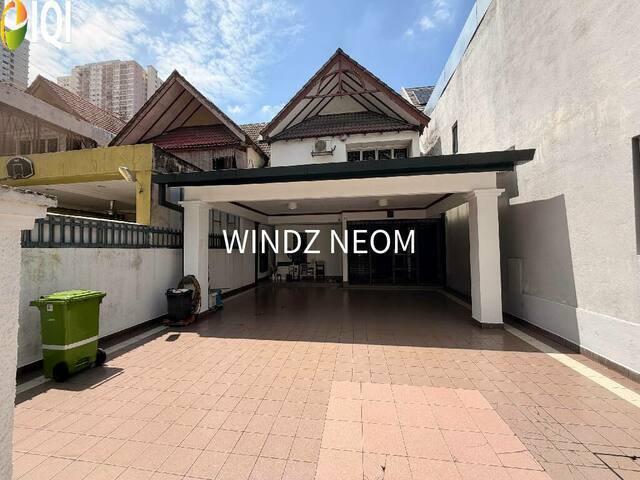
Bandar Menjalara (Desa Seri Mahkota)
Jalan 2/62C
₱ 17,762,268
Listed on March 25, 2026

The Tropika Bukit Jalil
Jalan Jalil Perkasa 7
₱ 21,130,974
Listed on July 2, 2026
Windmill Upon Hills
Jalan Permai, Genting Permai Avenue
₱ 15,312,300
Listed on April 7, 2026

Bangsar Hill Park
Lorong Maarof
₱ 99,530 /month
Listed on August 15, 2025
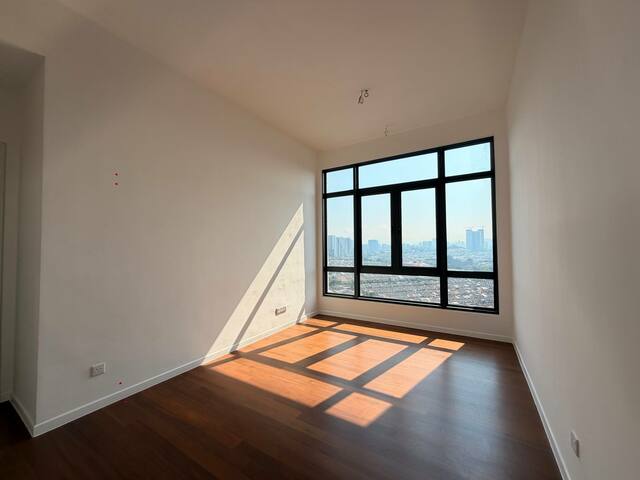
The Maple Residences OUG
Maple OUG
₱ 13,627,947
Listed on April 28, 2026
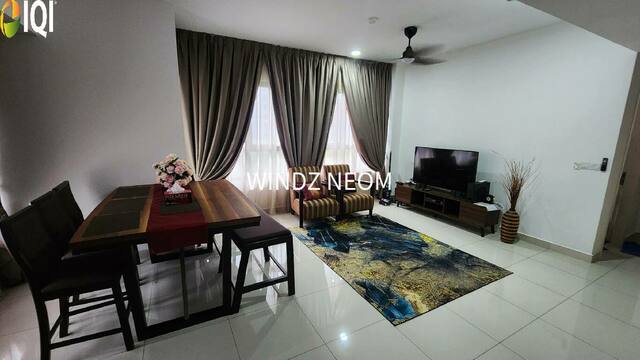
Paisley Serviced Residences @ Tropicana Metropark
Off Persiaran Teknologi Subang, Tropicana Metropark
₱ 11,484,225
Listed on May 20, 2026
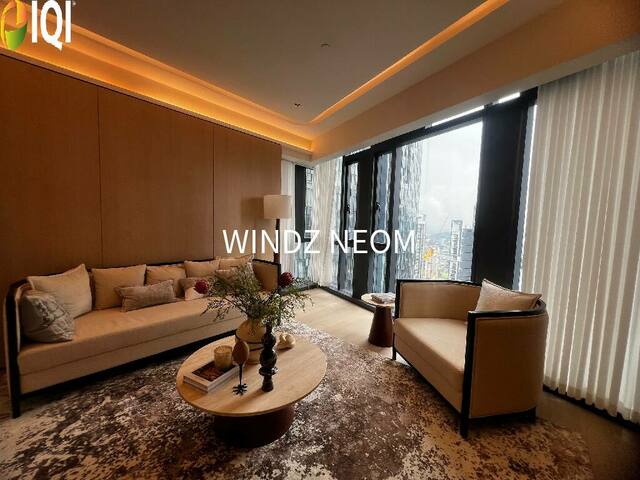
Star Residences
Jalan Yap Kwan Seng, Off Jalan Ampang
₱ 23,427,819
Listed on January 6, 2026
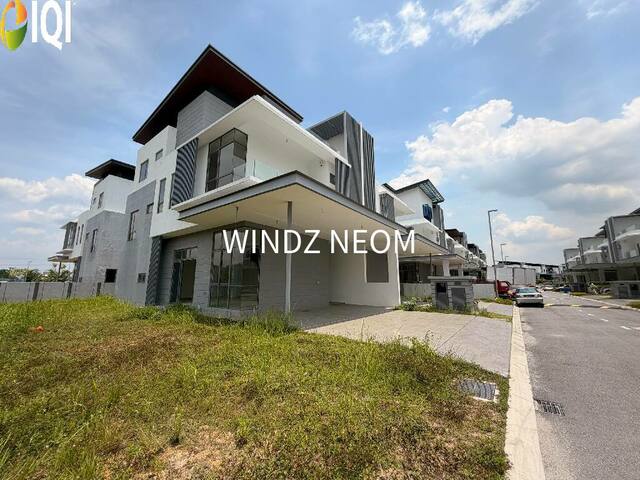
Broadleaf Residences
Jalan Anggerik Disa 31/184
₱ 37,208,889
Listed on April 28, 2026
The Maple Residences OUG
taman oug
₱ 12,249,840
Listed on April 17, 2026
Fortune Court
Block 288, Jalan Thean Teik
₱ 6,109,608
Listed on January 5, 2026

BK5
Bandar Kinrara
₱ 12,479,525
Listed on September 11, 2026
Jalan Enak
Happy Garden
₱ 78,858,345
Listed on April 7, 2026

The Andes @ Bukit Jalil
Off Mutiara Bukit Jalil
₱ 14,546,685
Listed on March 11, 2025
Lagoon Suites
Jalan Anggerik Malaxis 31/181
₱ 22,968 /month
Listed on September 13, 2026
Aria Luxury Residence
Jalan Tun Razak, Kuala Lumpur
₱ 18,374,760
Listed on March 18, 2026
The Ridge @ KL East (Residensi Rabung KL Timur)
PERSIARAN MELATI KUARZA
₱ 41,343 /month
Listed on July 27, 2026
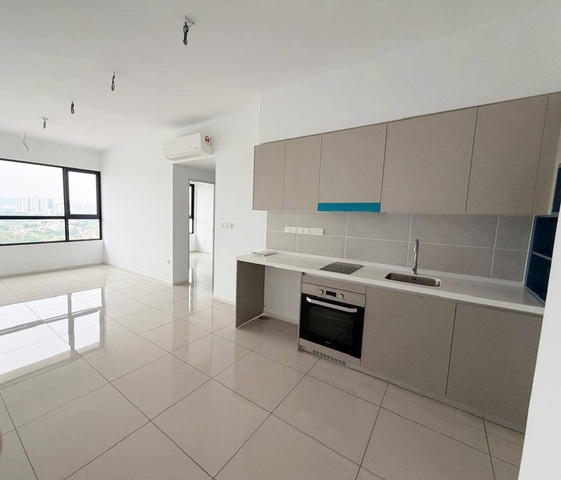
Est8 (Residensi Estetik 8)
Est8 Seputeh
₱ 10,412,364
Listed on September 21, 2026
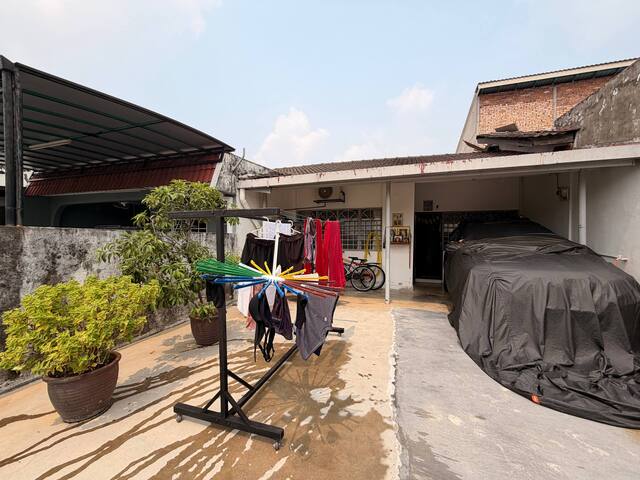
Seksyen 14, Petaling Jaya
Jalan 14/40
₱ 9,646,749
Listed on September 21, 2026
Nestree Residence @ Nestville
Pantai Sentral Park Bangsar South
₱ 122,498 /month
Listed on September 13, 2026
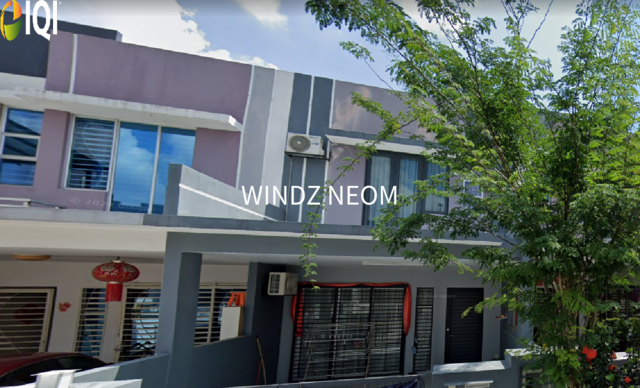
Acacia Park @ Bandar Tasik Puteri
Jalan Puteri
₱ 7,809,273
Listed on April 17, 2026
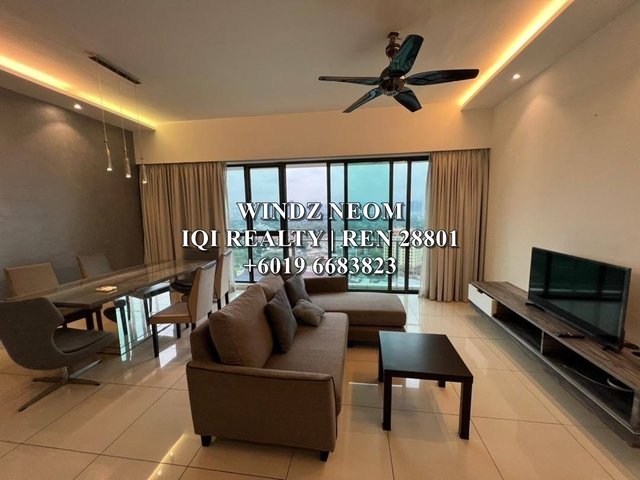
Setia Sky Residences
Jalan Tun Razak
₱ 13,474,824
Listed on April 7, 2026

Mawar Apartment
Taman Gohtong Jaya, Genting Highlands
₱ 4,899,936
Listed on August 5, 2026
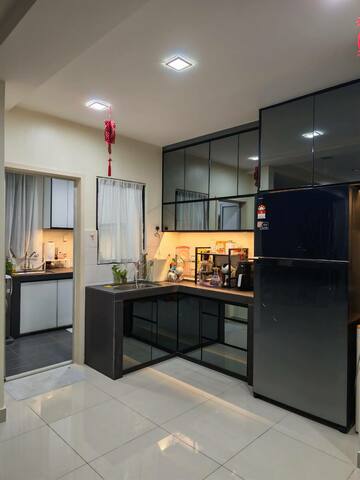
The Z Residence
Jalan 5/155, Taman Industri Bukit OUG, Bukit Jalil
₱ 11,024,856
Listed on July 2, 2026
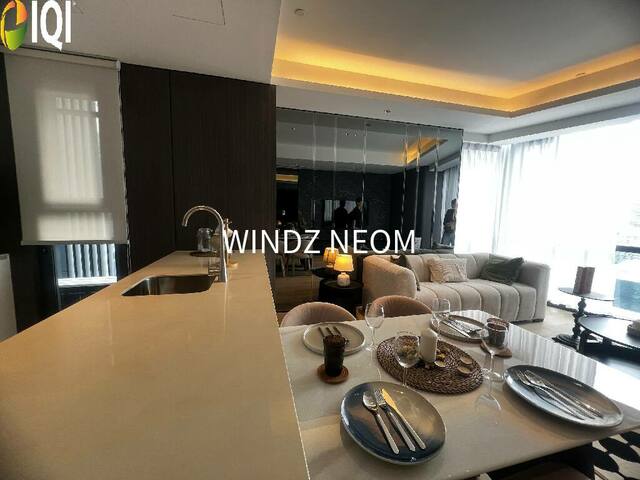
Star Residences
Jalan Yap Kwan Seng, Off Jalan Ampang
₱ 33,687,060
Listed on January 7, 2026
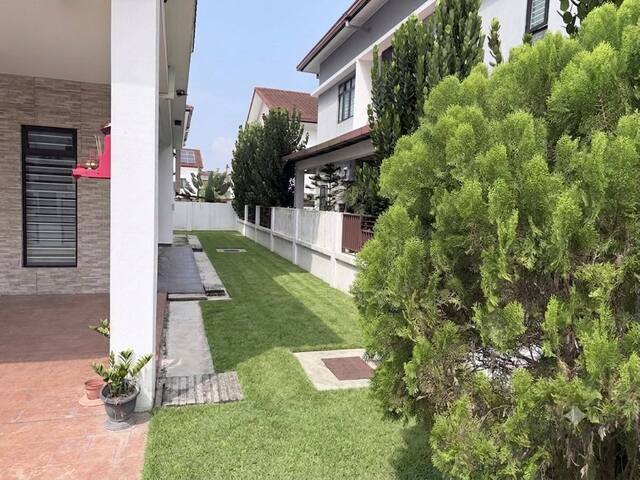
Anggun Villa 3 @ Bandar Kinrara
BANDAR KINRARA 5
₱ 45,171,285
Listed on September 19, 2026
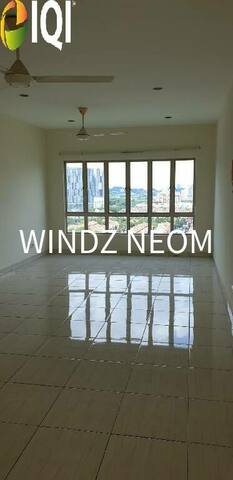
Green Avenue
Jalan 1/155B, Bukit OUG
₱ 7,196,781
Listed on August 13, 2025
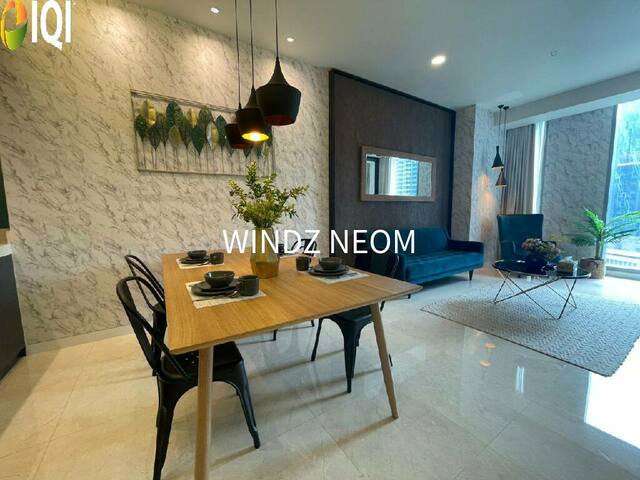
Tropicana The Residences
Jalan Ampang
₱ 21,437,220
Listed on January 23, 2026
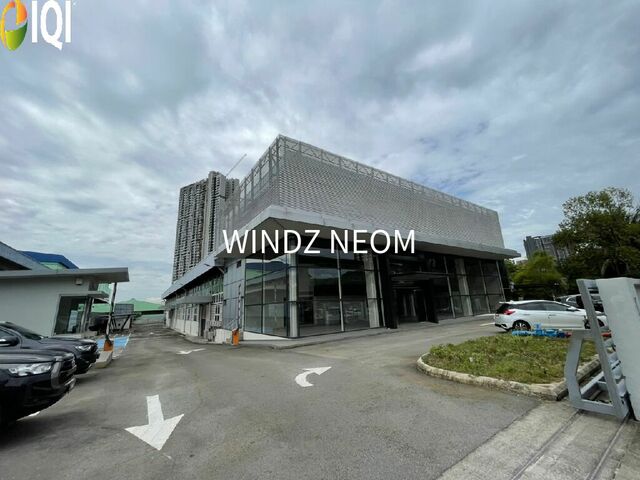
Kinrara Industrial Park
Section 1, Bandar Kinrara, 47180, Puchong
₱ 3,530,940 /month
Listed on May 6, 2026
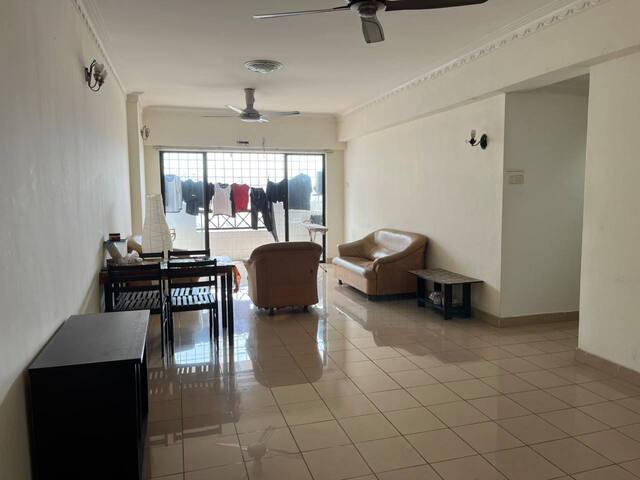
Vista Komanwel A
Jalan Barat, Bandar Bukit Jalil
₱ 6,660,851
Listed on September 17, 2026
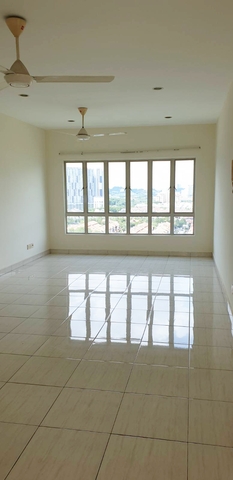
Green Avenue Condominium
Jalan Jalil Perkasa 1
₱ 7,043,658
Listed on September 17, 2026
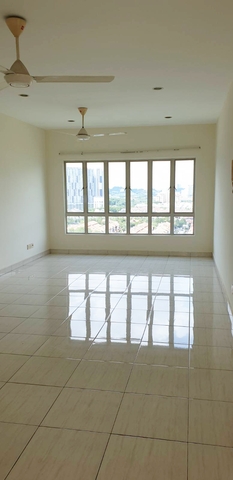
Green Avenue Condominium
Jalan Jalil Perkasa 1
₱ 27,562 /month
Listed on September 17, 2026
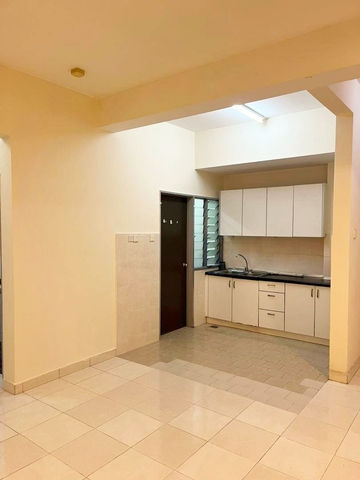
Lagoon Suites
Jalan Anggerik Malaxis 31/181
₱ 5,512,428
Listed on September 13, 2026

GENTING PERMAI PARK & RESORT
GENTING PERMAI PARK & RESORT
₱ 4,593,690
Listed on April 12, 2025
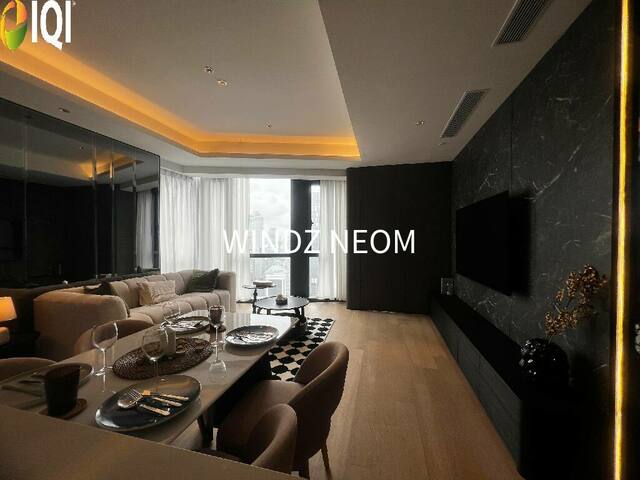
Star Residences
Jalan Yap Kwan Seng, Off Jalan Ampang
₱ 71,661,564
Listed on January 6, 2026

The Andes @ Bukit Jalil
Off Mutiara Bukit Jalil
₱ 21,130,974
Listed on March 11, 2025
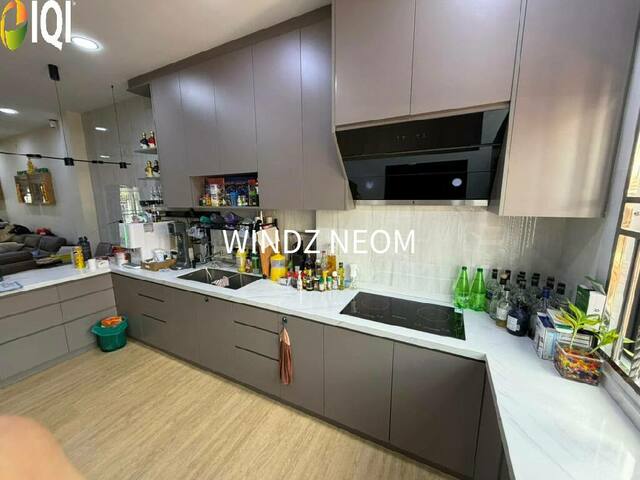
Happy Garden (Taman Gembira)
Jalan Riang, Jalan Selesa, Jalan Sukacita
₱ 27,868,386
Listed on May 20, 2026
Setia Sky Residences
Jalan Tun Razak
₱ 19,140,375
Listed on January 23, 2026

Puchong Financial Corporate Center (PFCC)
Jalan Puteri 1/2
₱ 143,522 /month
Listed on July 3, 2026
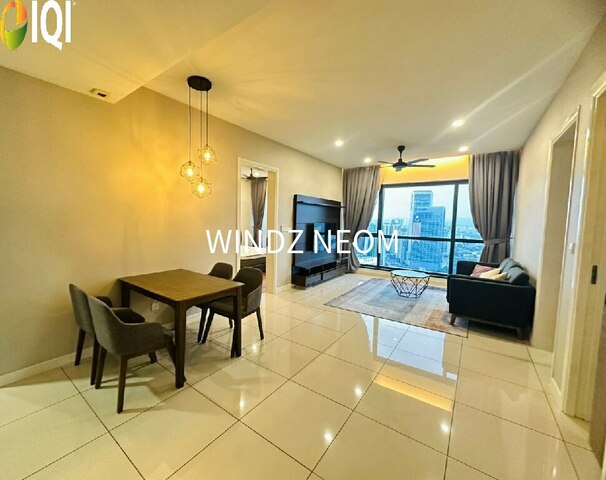
Aria Luxury Residence
Jalan Tun Razak, Kuala Lumpur
₱ 107,186 /month
Listed on September 18, 2025
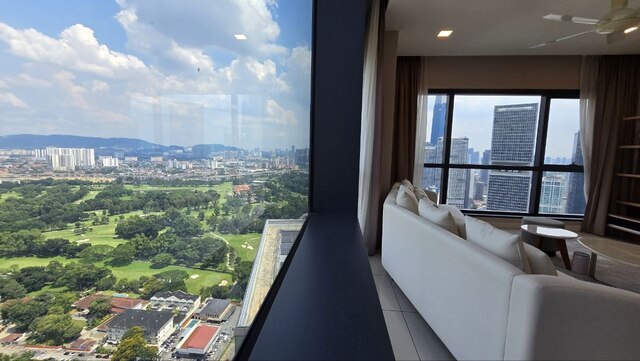
Aria Luxury Residence
Jalan Tun Razak, Kuala Lumpur
₱ 50,530,590
Listed on July 23, 2026

Scarletz Suites
Jalan Yap Kwan Seng, 50450, Kuala Lumpur
₱ 13,474,824
Listed on April 12, 2025
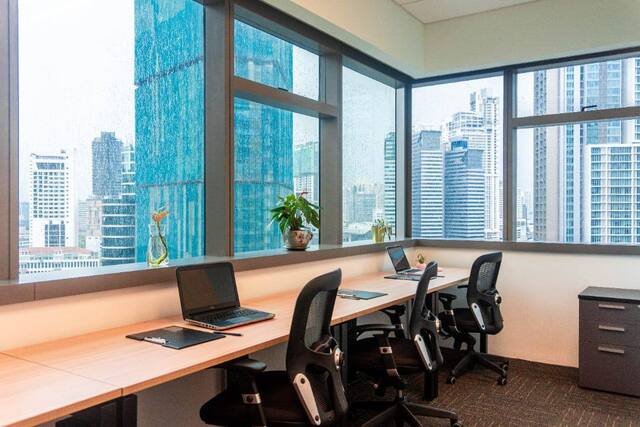
Menara Bangkok Bank | Berjaya Central Park
Jalan Ampang
₱ 306,246 /month
Listed on August 11, 2026

The Tropika Bukit Jalil
Jalan Jalil Perkasa 7
₱ 19,905,990
Listed on July 1, 2026

GENTING PERMAI PARK & RESORT
C-3-7, -, GENTING PERMAI PARK & RESORT
₱ 24,500 /month
Listed on August 5, 2026
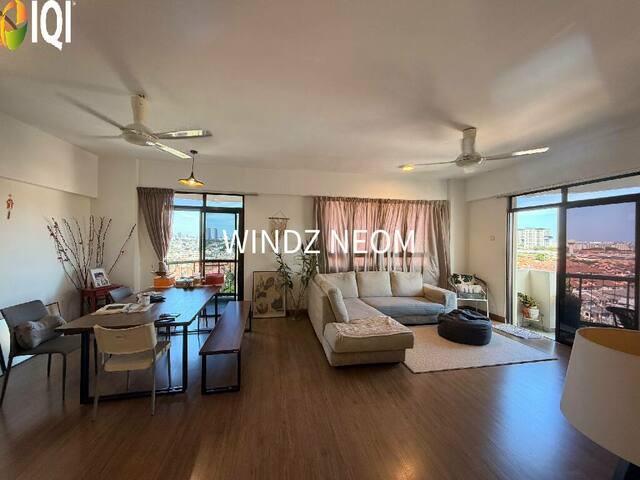
Mutiara Oriental Condominium
Jalan Bukit Mayang 1/8, Taman Bukit Mayang Emas
₱ 10,228,616
Listed on June 8, 2026
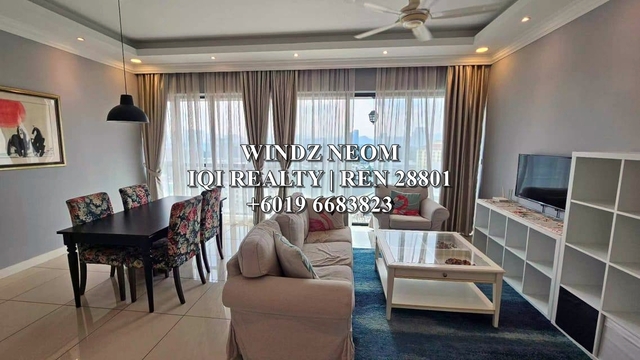
Setia Sky Residences
Jalan Tun Razak
₱ 15,312,300
Listed on April 7, 2026
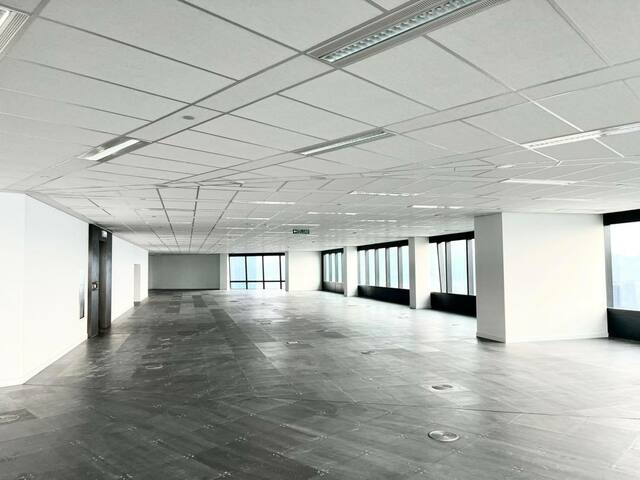
Merdeka 118 @ Warisan Merdeka 118
MERDEKA 118
₱ 2,894,025 /month
Listed on July 3, 2026

The Andes @ Bukit Jalil
Off Mutiara Bukit Jalil
₱ 21,437,220
Listed on March 11, 2025
Our newly launched projects
Discover the real estate properties in and around Kuala Lumpur, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Large land area
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from ₱ 221,959,751
Listed on January 23, 2026
 Varied built-up sizes
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 18,432,947
Listed on January 23, 2026
 Located in Simpang Ampat
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 76,791,185
Listed on January 23, 2026
 Located in Bukit Mertajam
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 17,131,401
Listed on January 23, 2026
 Larger built-up area
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 12,525,461
Listed on January 23, 2026
 Large land area
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from ₱ 8,421,765
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
Industrial and Commercial Recovery Gains Ground The Philippine property market entered the second half of 2026 with recovery strengthening across industrial, commercial and residential real estate. Industrial property remains the standout segment. First-half merchandise exports reached US$46.72 billion, the strongest performance since 1991, supported by electronics demand linked to the global AI supply chain. This momentum is feeding into a 1,200-hectare industrial land pipeline for 2026 to 2028, while industrial rents have increased 45% since 2019. New demand from EV and battery manufacturers is also supporting the sector. Metro Manila’s office vacancy remained stable at 19%, despite softer leasing volumes, while flexible workspace take-up doubled year-on-year. Retail vacancy is expected to fall below 10% by year-end, while around 3,100 new hotel rooms are scheduled for delivery in 2026. Residential Buyers Still Hold the Advantage The residential market remains firmly buyer-favourable. Inflation eased to 6.2% in July, marking a third consecutive month of improvement, while the BSP was expected to maintain its policy rate at 4.75%. Developers continue to compete for buyers through extended payment terms, rent-to-own structures and effective discounts of 3% to 12%. At the same time, future condominium supply is tightening sharply. Annual completions are expected to average around 3,600 units through 2028, down 72% from the 2017 to 2019 average. Outlook The Philippines is entering a potentially important transition period. Improving inflation, the prospect of lower borrowing costs and a shrinking condominium pipeline could support stronger residential absorption into 2027. Meanwhile, industrial assets remain the strongest structural growth story, supported by exports, manufacturing and infrastructure demand. For investors, the second half of 2026 offers an opportunity to focus on quality industrial assets, flexible commercial space and competitively priced residential properties before financing conditions improve further. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Inflation Eases as Market Conditions Improve The Philippines property market entered the second half of 2026 with a gradually improving economic outlook. Inflation declined for a second consecutive month, falling from 7.2% in April to 6.4% in June. Lower fuel and transport costs supported the improvement, while monthly inflation recorded its first decline in a year at -0.3%. The Bangko Sentral ng Pilipinas raised its policy rate to 4.75%, but inflation is expected to ease further through 2028. Economic growth is also forecast to strengthen from 2.8% in Q1 2026 to 4.4% for the full year, supporting future consumption, investment and property demand. Industrial Property Offers the Strongest Prospects Metro Manila condominiums remain a buyer’s market, creating opportunities for buyers seeking discounted properties. New condominium completions are expected to average only 3,600 units annually from 2026 to 2028, significantly below the 13,000-unit annual average recorded between 2017 and 2019. This lower supply pipeline could gradually reduce excess inventory. Developer incentives, strong overseas Filipino worker remittances and projected national price appreciation of 25% to 35% by 2031 may support long-term residential demand. Metro Manila’s office vacancy rate improved to 19%, supported by limited new supply and demand beyond the business process outsourcing sector. Retail vacancy is also expected to fall below 10% as household spending recovers. Industrial property remains the strongest segment, led by Central Luzon and the Clark corridor. Rising rents, logistics improvements, e-commerce growth and demand for energy-resilient facilities continue to strengthen investment fundamentals. Outlook Industrial and Clark corridor assets offer the strongest risk-adjusted opportunities. Selected CBD offices, retail properties and discounted condominiums also present improving prospects. Investors should remain selective, prioritising quality assets, strong locations and longer holding periods while monitoring inflation, electricity costs and geopolitical risks. Juwai IQI Newsletter August 2026Download
Philippines Real Estate Shows Stronger Recovery Signals The Philippines property market is entering the second half of 2026 with improving momentum. The US-Iran ceasefire and reopening of the Strait of Hormuz have helped stabilise global oil markets, leading to major fuel rollbacks in the Philippines. This is easing pressure on household budgets and business costs, while also supporting buyer confidence. At the same time, the proposed Japan-Philippines petroleum reserve partnership strengthens the country’s long-term energy security outlook. The residential market remains selective. Metro Manila condominiums are still a buyer’s market, with around 74,000 to 75,300 unsold units. However, developer discounts, rent-to-own schemes and longer payment terms are creating attractive entry opportunities. Supply is also expected to tighten, with only about 3,600 new condo units annually from 2026 to 2028, far below the previous peak average of 13,000 units. Regional markets such as Cavite, Laguna, Cebu, Iloilo and Davao remain stronger performers, with projected annual appreciation of 5% to 7%. Industrial and Commercial Segments Lead Growth Industrial and logistics remain the strongest investment theme. The New Clark City industrial hub is reinforcing the Clark-Pampanga corridor as a key manufacturing and logistics destination, while industrial rents have risen 45% since 2019. Commercial property is also improving. Office demand rose 70% year-on-year in Q1 2026, supported by BPO and IT-BPM expansion. Retail vacancy is expected to fall below 10% by end-2026, while hospitality is benefiting from flight surcharge cuts and route restoration. Outlook The Philippines market is not without challenges, but its fundamentals remain strong. With 115 million people, record OFW remittances, infrastructure expansion and improving energy stability, H2 2026 could mark a clearer recovery phase. Industrial assets, Clark-linked logistics, regional residential corridors and prime income-generating assets are likely to remain the best-positioned opportunities. Download to see insights from other country marketsDownload
The Philippines property market faced a more challenging environment in early 2026 as inflation, higher interest rates, and rising living costs weighed on consumer sentiment and investment activity. While some sectors remain under pressure, industrial and logistics real estate continues to stand out as the market's strongest-performing segment. Residential Market Remains Challenging The residential sector continues to face headwinds from higher borrowing costs and affordability concerns. A large inventory of unsold condominium units, combined with rising mortgage rates, has slowed buyer activity across several urban markets. Despite these challenges, demand remains relatively resilient in regional growth centres and master-planned transit-oriented communities, where long-term infrastructure improvements continue to support buyer interest. End-users remain focused on affordability, connectivity, and long-term value rather than speculative purchases. Commercial Sector Shows Mixed Recovery The commercial property market is gradually recovering, although performance remains uneven across sectors. Prime office locations continue to attract demand, particularly in established business districts where vacancy rates are expected to improve. Retail activity is also showing signs of recovery, supported by experiential retail concepts and international brands. However, the hospitality sector continues to face challenges as tourism recovery remains slower than expected in some areas. Industrial and Logistics Lead Growth Among all property sectors, industrial and logistics real estate remains the strongest performer. Continued investment in manufacturing, warehousing, and logistics infrastructure is supporting demand for industrial space, particularly within strategic growth corridors. The development of New Clark City and the Clark-Pampanga corridor continues to strengthen the region's position as a key industrial and logistics hub. Rising industrial rents and ongoing investment commitments highlight the sector's growing importance within the country's long-term economic development strategy. Outlook While inflation, interest rates, and affordability concerns may continue creating short-term challenges, the Philippines' long-term property fundamentals remain intact. Supported by infrastructure investment, urbanisation, and demographic growth, the market continues to offer opportunities for investors focused on long-term value. Industrial and logistics assets, along with strategically located commercial and residential developments, are expected to remain among the most resilient sectors through the remainder of 2026. Download to see insights from other country marketsDownload
Ready to get started?
Get in touch now.