

Team Leader (Subsales) ∙ Dreammakerz
Melissa Yap
PEA2758
About Melissa Yap
I advise clients on property strategy, investment decisions and asset disposal, with a strong focus on market analysis, due diligence, compliance and long-term outcomes. With seven years of experience in Malaysia’s property market, I have worked across residential, commercial, land and industrial as... I advise clients on property strategy, investment decisions and asset disposal, with a strong focus on market analysis, due diligence, compliance and long-term outcomes. With seven years of experience in Malaysia’s property market, I have worked across residential, commercial, land and industrial assets, supporting clients through transactions involving private treaty, sale by tender and strategic property advisory. My approach is grounded in market analysis, valuation considerations, regulatory awareness and due diligence. I work with clients across Kuantan, Kemaman and the wider East Coast, including property owners, buyers, investors and business clients.Increasingly, my work involves helping clients navigate:Property investment strategy and asset positioning__Market and valuation considerations___Holding strategy and exit planning___Commercial, industrial and land opportunities___Sale by tender and private treaty transactions___Due diligence and transaction considerations___I also lead the East Coast Tender Division, where I am involved in supporting and training new real estate negotiators in understanding the tender process and developing practical property skills.———— | Property decisions today should still make sense years from now. | __________ 我是 Melissa,一名专注于房地产策略、投资决策与资产处置的房地产顾问。在马来西亚房地产行业拥有 7年的经验,我的业务领域涵盖 住宅、商业地产、土地及工业地产,并参与 私人协议出售(Private Treaty)、公开竞标(Sale by Tender)以及房地产策略咨询。我的工作方式,不只是协助客户“找房子”或“卖房子”,而是从市场分析、价值判断、监管与合规考量,以及尽职调查出发,帮助客户看清一项房地产决策背后的风险、机会与长期影响。我目前主要扎根于 Kuantan、Pahang,同时服务 Kemaman 及东海岸地区的买家、业主、投资者及企业客户。除了房地产交易,我目前也负责 IQI 东海岸 Tender Division,参与房地产竞标业务,并协助培训新一代房地产经纪人,让他们更系统地了解竞标流程、市场判断及实际房地产操作。———— | 好的房地产决定,不只是今天正确,而是几年后回头看,依然合理。|
7 years at IQI
95 transactions
12 properties on sale
6 properties on rent

Melissa Yap's Service Locations
Melissa Yap's Service Locations
My Listings
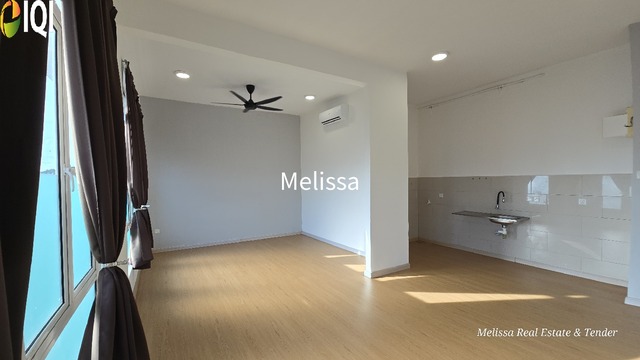
Mahkota Valley Suites
Jalan IM 9/3, Bandar Indera Mahkota
₱ 14,014 /month
Listed on April 13, 2026
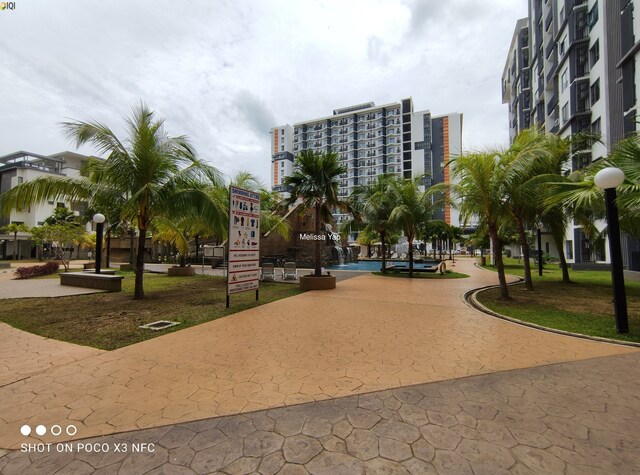
Timurbay Seafront Residence
Jalan Kuantan – Kemaman, Sungai Karang
₱ 8,564,050
Listed on December 16, 2025
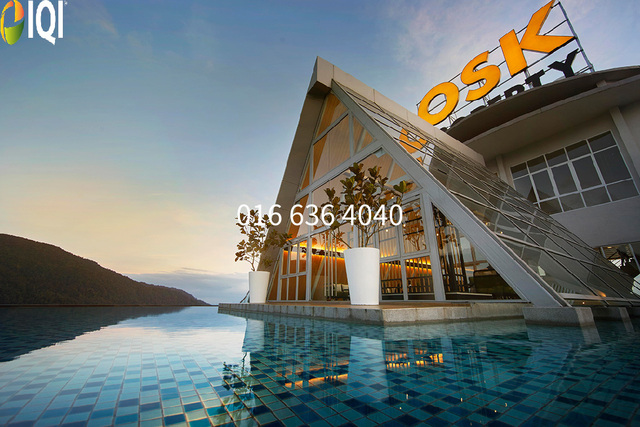
Windmill Upon Hills
Jalan Permai, Genting Permai Avenue
₱ 8,096,920
Listed on April 2, 2026

Seri Kuantan
Jalan Seri Kuantan
₱ 7,006,950
Listed on March 14, 2023
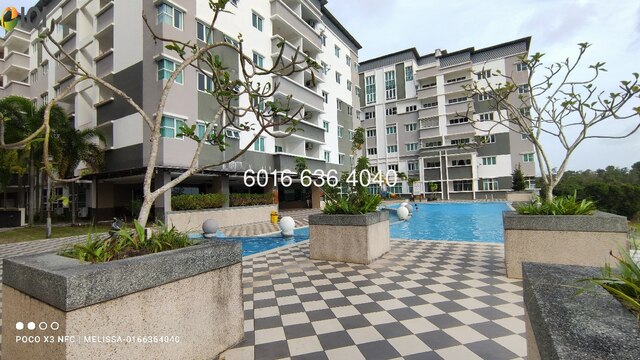
D'embassy
D'Embassy Residence Suites
₱ 6,041,548
Listed on June 20, 2026

ALAM PERDANA
LORONG IM 12, ALAM PERDANA, IM 12
₱ 24,914 /month
Listed on October 15, 2024
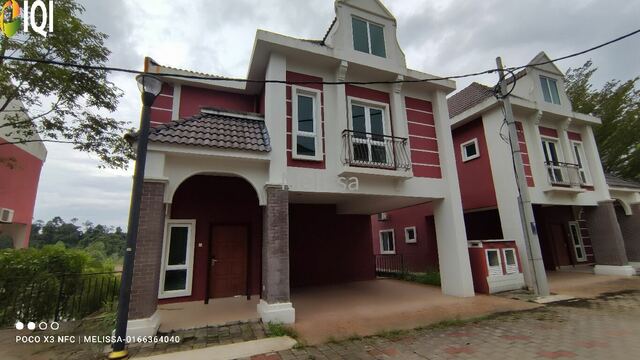
Kuantan Bukit Gambang Residence City
Jalan Warisan 3, Kampung Pohoi, 26300 Gambang, Pahang
₱ 6,041,548
Listed on October 16, 2025
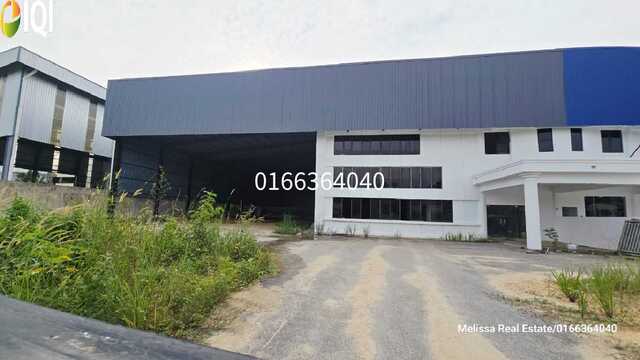
Jalan MEC Highway Gambang
1-storey Factory
₱ 60,726,900
Listed on June 22, 2026

D'embassy
D'Embassy Residence Suites
₱ 43,599 /month
Listed on October 14, 2024
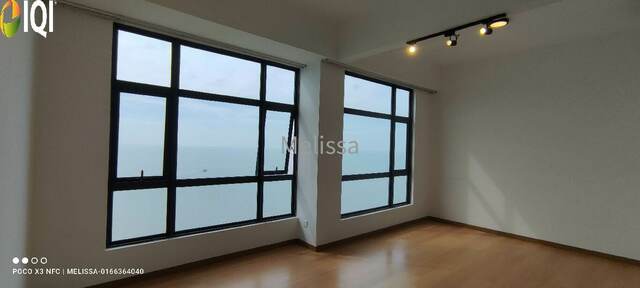
Imperium Residence Kuantan Waterfront Resort City
Tanjung Lumpur, Kuantan, Pahang
₱ 5,605,560
Listed on July 31, 2020

D'Embassy Suites
Bukit pelindung 76
₱ 56,056 /month
Listed on September 15, 2023
Bandar MEC Gambang Kuantan
105 Jalan MEC 1, Bandar MEC, Gambang Kuantan, 26300, Gambang, Pahang, 26300
₱ 295,849 /month
Listed on April 14, 2026
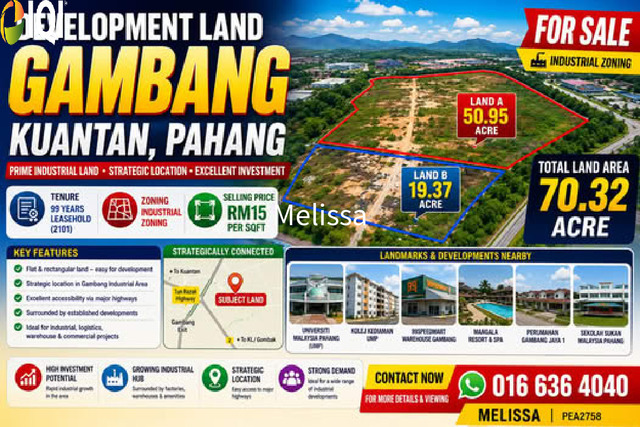
Persiaran Bandar Gambang
Persiaran Bandar Gambang, Perdana 3, 26300 Gambang, Pahang
₱ 716,266,000
Listed on June 22, 2026
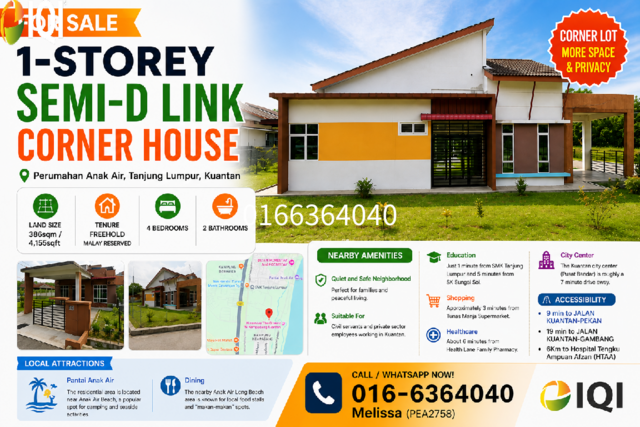
PERUMAHAN ANAK AIR
LORONG ANAK AIR BARU 2,PERUMAHAN ANAK AIR, 26060
₱ 6,539,820
Listed on September 30, 2026
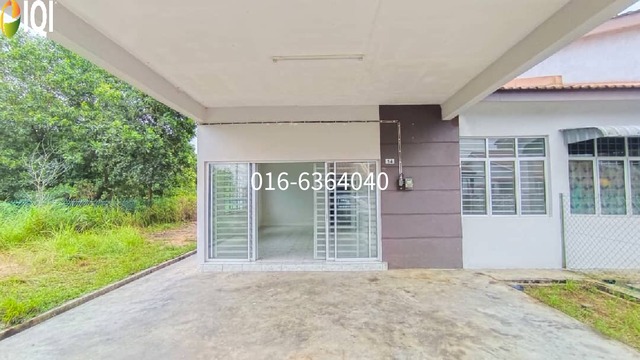
Residensi Prima Mahkota Jaya 2
Mahkota Jaya 2, Gambang
₱ 3,861,608 /month
Listed on April 14, 2026
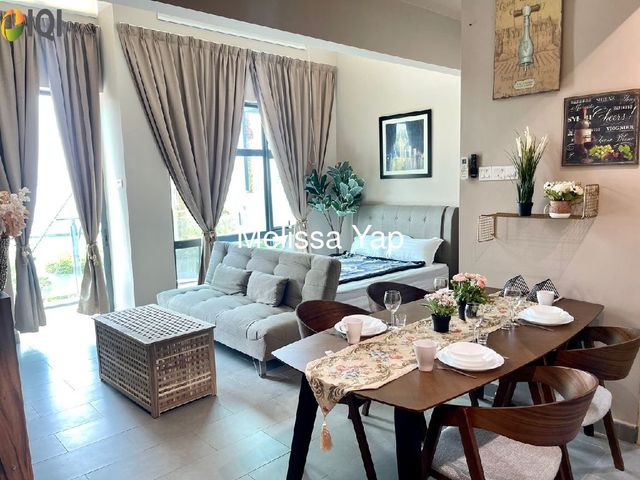
IMPERIUM RESIDENCE, KUANTAN WATERFRONT
JALAN TANJUNG LUMPUR, IMPERIUM RESIDENCE, KUANTAN WATERFRONT
₱ 9,731,875
Listed on August 25, 2023
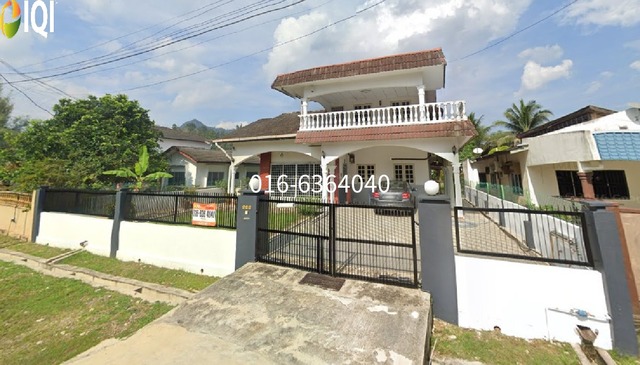
Sungai Marong
Bentong Pahang
₱ 14,792,450
Listed on October 2, 2024
hulu jabur
Jalan Jabor Lama
₱ 15,571,000
Listed on December 1, 2025
Our newly launched projects
Discover the real estate properties in and around Kuantan, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Large land area
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from ₱ 225,709,742
Listed on January 23, 2026
 Located in Bukit Minyak
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 18,744,370
Listed on January 23, 2026
 Located in Simpang Ampat
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 78,088,565
Listed on January 23, 2026
 Spacious land area
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 17,420,835
Listed on January 23, 2026
 Larger built-up area
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 12,737,078
Listed on January 23, 2026
 Located in Nibong Tebal
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from ₱ 8,564,050
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
Residential Recovery Moves Into Clearer View The Philippine property market is showing stronger signs of recovery, led by a sharp improvement in residential absorption. In Metro Manila, preselling net take-up surged 765% year-on-year in Q1 2026, driven mainly by the economic and affordable segments. As a result, remaining inventory life fell to 6.8 years, down from a peak of 13.4 years in mid-2025. Developers are now prioritising the clearance of ready-for-occupancy stock before launching new projects, while completions are expected to decline from 2027 onward. Vacancy is still projected to reach 25.6% by year-end, but this largely reflects earlier supply decisions rather than current demand conditions. Demand also remains healthy in well-priced fringe locations such as the C5 Corridor and Katipunan, reinforcing the importance of the right combination of product, location and pricing. Commercial and Industrial Demand Adds Depth The recovery is also being supported by stronger commercial demand. The Philippines is ranked as the world’s second-largest GCC delivery location, with the GCC workforce projected to reach around 289,000 professionals across approximately 200 centres in 2026. This is supporting demand for prime CBD offices and key provincial markets. Tourism has also improved, with 3.16 million international arrivals in H1 2026, up 5.4%, while hotel average daily rates rose 2.4%. Industrial remains another strong segment, supported by new logistics supply and PHP 81.4 billion in approved foreign manufacturing pledges. Outlook The Philippines appears to be entering a confirmed recovery phase, but opportunities remain selective. With buyer-friendly pricing gradually being absorbed and future supply becoming more constrained, well-located residential, office and industrial assets may benefit most as the market continues to improve. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Industrial and Commercial Recovery Gains Ground The Philippine property market entered the second half of 2026 with recovery strengthening across industrial, commercial and residential real estate. Industrial property remains the standout segment. First-half merchandise exports reached US$46.72 billion, the strongest performance since 1991, supported by electronics demand linked to the global AI supply chain. This momentum is feeding into a 1,200-hectare industrial land pipeline for 2026 to 2028, while industrial rents have increased 45% since 2019. New demand from EV and battery manufacturers is also supporting the sector. Metro Manila’s office vacancy remained stable at 19%, despite softer leasing volumes, while flexible workspace take-up doubled year-on-year. Retail vacancy is expected to fall below 10% by year-end, while around 3,100 new hotel rooms are scheduled for delivery in 2026. Residential Buyers Still Hold the Advantage The residential market remains firmly buyer-favourable. Inflation eased to 6.2% in July, marking a third consecutive month of improvement, while the BSP was expected to maintain its policy rate at 4.75%. Developers continue to compete for buyers through extended payment terms, rent-to-own structures and effective discounts of 3% to 12%. At the same time, future condominium supply is tightening sharply. Annual completions are expected to average around 3,600 units through 2028, down 72% from the 2017 to 2019 average. Outlook The Philippines is entering a potentially important transition period. Improving inflation, the prospect of lower borrowing costs and a shrinking condominium pipeline could support stronger residential absorption into 2027. Meanwhile, industrial assets remain the strongest structural growth story, supported by exports, manufacturing and infrastructure demand. For investors, the second half of 2026 offers an opportunity to focus on quality industrial assets, flexible commercial space and competitively priced residential properties before financing conditions improve further. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Inflation Eases as Market Conditions Improve The Philippines property market entered the second half of 2026 with a gradually improving economic outlook. Inflation declined for a second consecutive month, falling from 7.2% in April to 6.4% in June. Lower fuel and transport costs supported the improvement, while monthly inflation recorded its first decline in a year at -0.3%. The Bangko Sentral ng Pilipinas raised its policy rate to 4.75%, but inflation is expected to ease further through 2028. Economic growth is also forecast to strengthen from 2.8% in Q1 2026 to 4.4% for the full year, supporting future consumption, investment and property demand. Industrial Property Offers the Strongest Prospects Metro Manila condominiums remain a buyer’s market, creating opportunities for buyers seeking discounted properties. New condominium completions are expected to average only 3,600 units annually from 2026 to 2028, significantly below the 13,000-unit annual average recorded between 2017 and 2019. This lower supply pipeline could gradually reduce excess inventory. Developer incentives, strong overseas Filipino worker remittances and projected national price appreciation of 25% to 35% by 2031 may support long-term residential demand. Metro Manila’s office vacancy rate improved to 19%, supported by limited new supply and demand beyond the business process outsourcing sector. Retail vacancy is also expected to fall below 10% as household spending recovers. Industrial property remains the strongest segment, led by Central Luzon and the Clark corridor. Rising rents, logistics improvements, e-commerce growth and demand for energy-resilient facilities continue to strengthen investment fundamentals. Outlook Industrial and Clark corridor assets offer the strongest risk-adjusted opportunities. Selected CBD offices, retail properties and discounted condominiums also present improving prospects. Investors should remain selective, prioritising quality assets, strong locations and longer holding periods while monitoring inflation, electricity costs and geopolitical risks. Juwai IQI Newsletter August 2026Download
Philippines Real Estate Shows Stronger Recovery Signals The Philippines property market is entering the second half of 2026 with improving momentum. The US-Iran ceasefire and reopening of the Strait of Hormuz have helped stabilise global oil markets, leading to major fuel rollbacks in the Philippines. This is easing pressure on household budgets and business costs, while also supporting buyer confidence. At the same time, the proposed Japan-Philippines petroleum reserve partnership strengthens the country’s long-term energy security outlook. The residential market remains selective. Metro Manila condominiums are still a buyer’s market, with around 74,000 to 75,300 unsold units. However, developer discounts, rent-to-own schemes and longer payment terms are creating attractive entry opportunities. Supply is also expected to tighten, with only about 3,600 new condo units annually from 2026 to 2028, far below the previous peak average of 13,000 units. Regional markets such as Cavite, Laguna, Cebu, Iloilo and Davao remain stronger performers, with projected annual appreciation of 5% to 7%. Industrial and Commercial Segments Lead Growth Industrial and logistics remain the strongest investment theme. The New Clark City industrial hub is reinforcing the Clark-Pampanga corridor as a key manufacturing and logistics destination, while industrial rents have risen 45% since 2019. Commercial property is also improving. Office demand rose 70% year-on-year in Q1 2026, supported by BPO and IT-BPM expansion. Retail vacancy is expected to fall below 10% by end-2026, while hospitality is benefiting from flight surcharge cuts and route restoration. Outlook The Philippines market is not without challenges, but its fundamentals remain strong. With 115 million people, record OFW remittances, infrastructure expansion and improving energy stability, H2 2026 could mark a clearer recovery phase. Industrial assets, Clark-linked logistics, regional residential corridors and prime income-generating assets are likely to remain the best-positioned opportunities. Download to see insights from other country marketsDownload
Ready to get started?
Get in touch now.
