

Negotiator ∙ United
Ku Mei
REN54405
About Ku Mei
Leveraging market knowledge and negotiation skills to deliver exceptional results. Your real estate success is my priority. Ready to make your real estate dreams a reality? Let's chat. Your dream home awaits.
5 years at IQI
266 transactions
7 properties on sale
11 properties on rent
Ku Mei Social Links
No social links available.
Ku Mei's Service Locations
Ku Mei's Service Locations
My Listings
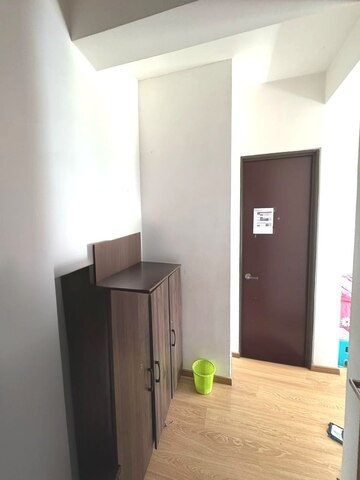
Country Garden @ Danga Bay
Lebuhraya Sultan Iskandar
₱ 46,681 /month
Listed on October 15, 2026
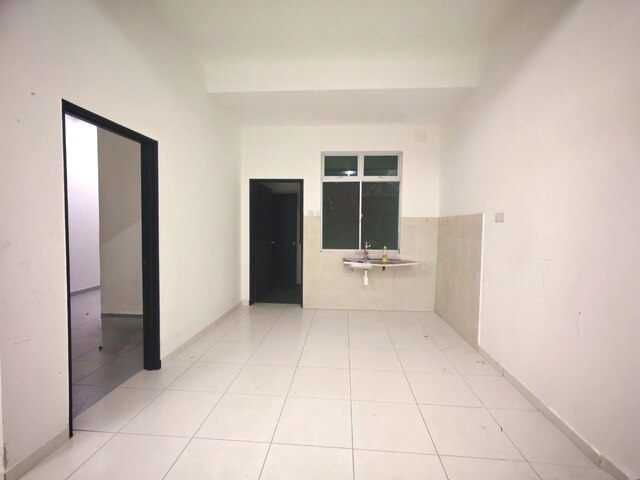
Taman Pulai Mutiara 2 @ Johor
17, Jalan Mutiara 4/1
₱ 34,233 /month
Listed on October 15, 2026
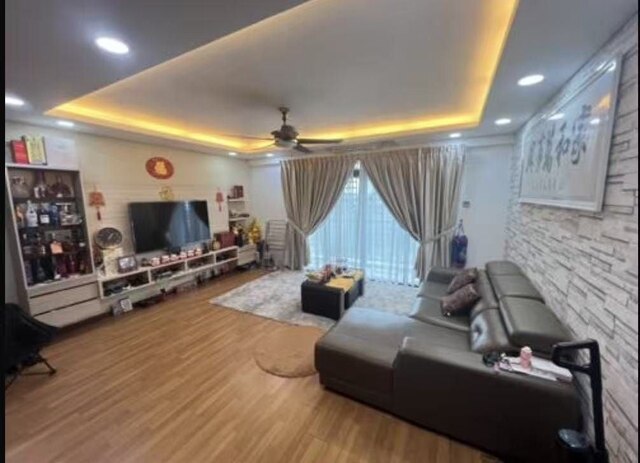
The Garden Residences (Residensi Anjung Hijauan)
Jalan Persiaran Mutiara Mas
₱ 9,024,974
Listed on September 21, 2026
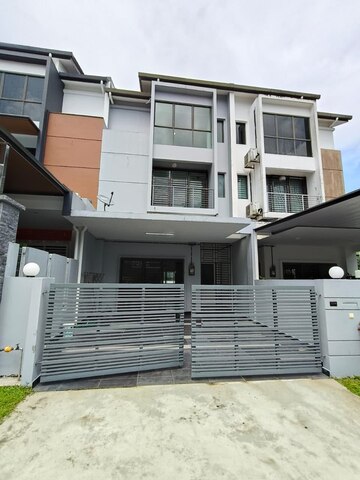
Bandar Indahpura
Jln Cempaka , Bandar Indahpura, 81000 Kulai, Johor Darul Ta'zim
₱ 37,345 /month
Listed on September 21, 2026
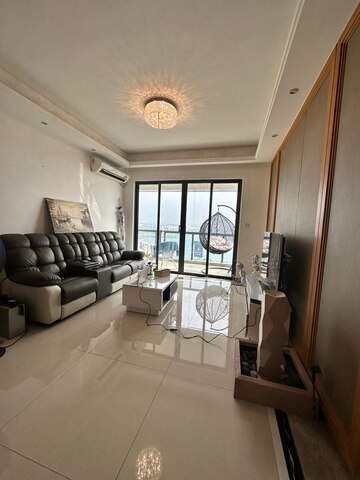
R&F Princess Cove Mercu 3 (New Phase)
1, Jalan Tanjung Puteri, Tanjung Puteri, 80300 Johor Bahru, Johor Darul Takzim, Malaysia
₱ 19,450,375
Listed on September 21, 2026
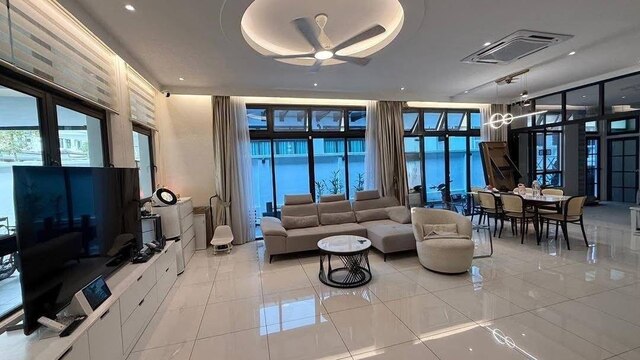
The Aldingham @ Eco Botanic
Jalan Eko Botani , 79100 Gelang Patah, Johor Darul Ta'zim
₱ 27,230,525
Listed on September 21, 2026
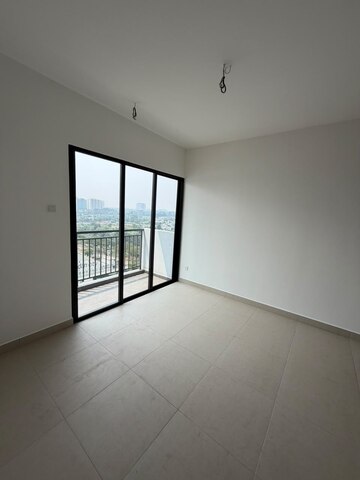
Pandan Heights (Residensi Pandan 3)
Jalan Pandan, Pusat Perdagangan Pandan, 81100 Johor Bahru, Johor Darul Ta'zim
₱ 8,246,959
Listed on September 21, 2026
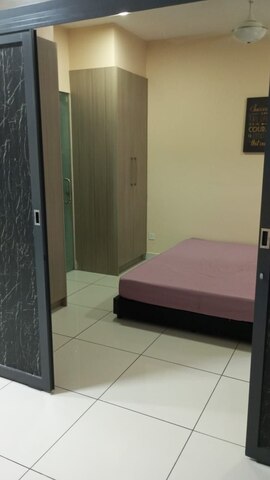
1Tebrau (One Tebrau Residence)
Tebrau Highway
₱ 27,231 /month
Listed on October 15, 2026
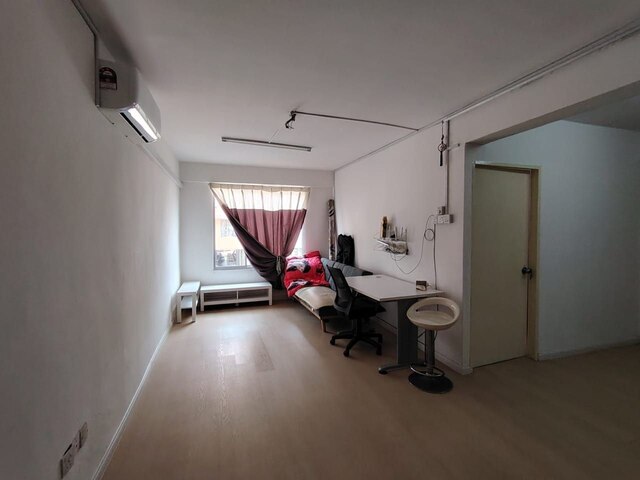
Sri Lanang Flat (Rumah Pangsa Sri Lanang)
Taman Desa Tebrau, Johor Bahru
₱ 27,697 /month
Listed on September 21, 2026
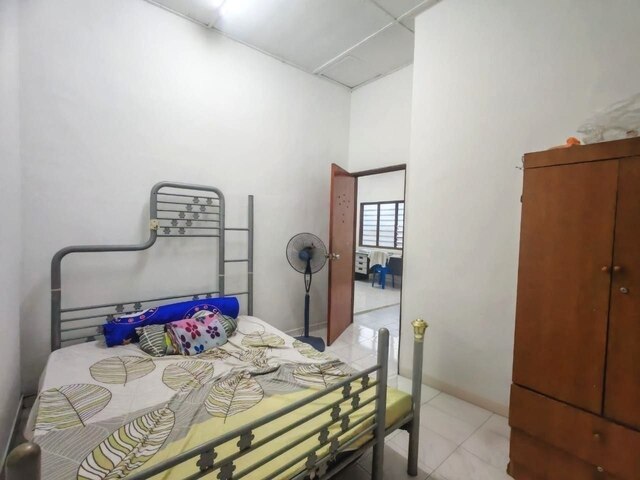
Jalan Dasa 3
Jalan Dasa 3
₱ 7,468,944
Listed on October 15, 2026
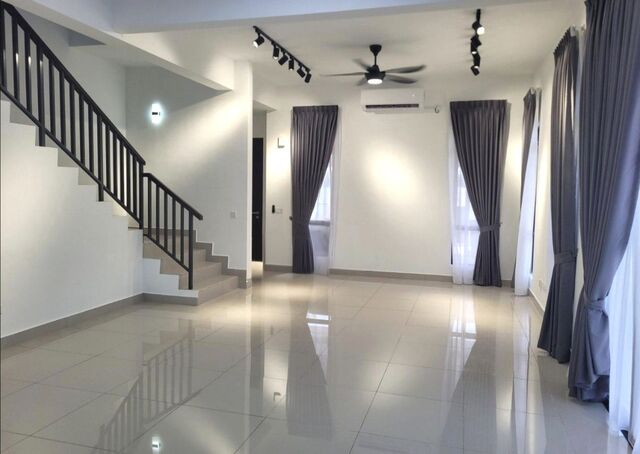
Aspira ParkHomes @ Gelang Patah
Johor
₱ 68,465 /month
Listed on October 15, 2026
R&F Princess Cove
Jalan Tanjung Puteri
₱ 43,569 /month
Listed on October 15, 2026
Garden Villas @ Bukit Indah
Jalan Indah 11/X
₱ 57,573 /month
Listed on October 15, 2026
Sapphire Hills @ Bandar Baru Kangkar Pulai
Jalan Pulai Ceria 1
₱ 9,336,180
Listed on October 15, 2026
IOI Bandar Putra Kulai
Jalan Putra , Bandar Putra Kulai, 81000 Kulai, Johor Darul
₱ 31,121 /month
Listed on September 21, 2026
Meridin Bayvue Apartment (Sierra Meridian)
56, Jalan Sierra Perdana 4/1, Taman Sierra Perdana
₱ 32,677 /month
Listed on October 11, 2026
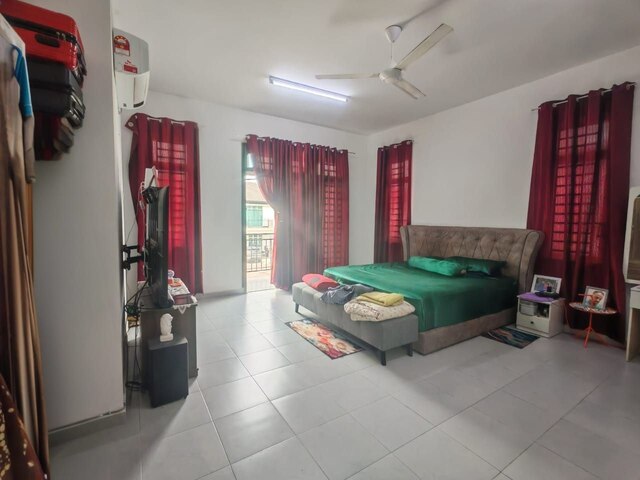
Taman Pulai Mutiara
Jalan Pulai Mutiara 81300 Kangkar Pulai
₱ 11,203,416
Listed on October 15, 2026
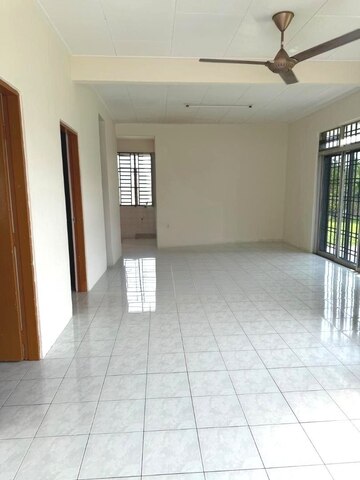
Taman Impian Jaya
Jalan Impian , Taman Impian Jaya, 81400 Senai, Johor, Malaysia
₱ 29,565 /month
Listed on September 21, 2026
Our newly launched projects
Discover the real estate properties in and around Johor Bahru, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Large land area
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from ₱ 225,554,640
Listed on January 23, 2026
 Located in Bukit Minyak
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 18,731,489
Listed on January 23, 2026
 Industrial project type
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 78,034,905
Listed on January 23, 2026
 Located in Bukit Mertajam
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 17,408,864
Listed on January 23, 2026
 Larger built-up area
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 12,728,325
Listed on January 23, 2026
 Located in Nibong Tebal
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from ₱ 8,558,165
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
Residential Recovery Moves Into Clearer View The Philippine property market is showing stronger signs of recovery, led by a sharp improvement in residential absorption. In Metro Manila, preselling net take-up surged 765% year-on-year in Q1 2026, driven mainly by the economic and affordable segments. As a result, remaining inventory life fell to 6.8 years, down from a peak of 13.4 years in mid-2025. Developers are now prioritising the clearance of ready-for-occupancy stock before launching new projects, while completions are expected to decline from 2027 onward. Vacancy is still projected to reach 25.6% by year-end, but this largely reflects earlier supply decisions rather than current demand conditions. Demand also remains healthy in well-priced fringe locations such as the C5 Corridor and Katipunan, reinforcing the importance of the right combination of product, location and pricing. Commercial and Industrial Demand Adds Depth The recovery is also being supported by stronger commercial demand. The Philippines is ranked as the world’s second-largest GCC delivery location, with the GCC workforce projected to reach around 289,000 professionals across approximately 200 centres in 2026. This is supporting demand for prime CBD offices and key provincial markets. Tourism has also improved, with 3.16 million international arrivals in H1 2026, up 5.4%, while hotel average daily rates rose 2.4%. Industrial remains another strong segment, supported by new logistics supply and PHP 81.4 billion in approved foreign manufacturing pledges. Outlook The Philippines appears to be entering a confirmed recovery phase, but opportunities remain selective. With buyer-friendly pricing gradually being absorbed and future supply becoming more constrained, well-located residential, office and industrial assets may benefit most as the market continues to improve. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Industrial and Commercial Recovery Gains Ground The Philippine property market entered the second half of 2026 with recovery strengthening across industrial, commercial and residential real estate. Industrial property remains the standout segment. First-half merchandise exports reached US$46.72 billion, the strongest performance since 1991, supported by electronics demand linked to the global AI supply chain. This momentum is feeding into a 1,200-hectare industrial land pipeline for 2026 to 2028, while industrial rents have increased 45% since 2019. New demand from EV and battery manufacturers is also supporting the sector. Metro Manila’s office vacancy remained stable at 19%, despite softer leasing volumes, while flexible workspace take-up doubled year-on-year. Retail vacancy is expected to fall below 10% by year-end, while around 3,100 new hotel rooms are scheduled for delivery in 2026. Residential Buyers Still Hold the Advantage The residential market remains firmly buyer-favourable. Inflation eased to 6.2% in July, marking a third consecutive month of improvement, while the BSP was expected to maintain its policy rate at 4.75%. Developers continue to compete for buyers through extended payment terms, rent-to-own structures and effective discounts of 3% to 12%. At the same time, future condominium supply is tightening sharply. Annual completions are expected to average around 3,600 units through 2028, down 72% from the 2017 to 2019 average. Outlook The Philippines is entering a potentially important transition period. Improving inflation, the prospect of lower borrowing costs and a shrinking condominium pipeline could support stronger residential absorption into 2027. Meanwhile, industrial assets remain the strongest structural growth story, supported by exports, manufacturing and infrastructure demand. For investors, the second half of 2026 offers an opportunity to focus on quality industrial assets, flexible commercial space and competitively priced residential properties before financing conditions improve further. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Inflation Eases as Market Conditions Improve The Philippines property market entered the second half of 2026 with a gradually improving economic outlook. Inflation declined for a second consecutive month, falling from 7.2% in April to 6.4% in June. Lower fuel and transport costs supported the improvement, while monthly inflation recorded its first decline in a year at -0.3%. The Bangko Sentral ng Pilipinas raised its policy rate to 4.75%, but inflation is expected to ease further through 2028. Economic growth is also forecast to strengthen from 2.8% in Q1 2026 to 4.4% for the full year, supporting future consumption, investment and property demand. Industrial Property Offers the Strongest Prospects Metro Manila condominiums remain a buyer’s market, creating opportunities for buyers seeking discounted properties. New condominium completions are expected to average only 3,600 units annually from 2026 to 2028, significantly below the 13,000-unit annual average recorded between 2017 and 2019. This lower supply pipeline could gradually reduce excess inventory. Developer incentives, strong overseas Filipino worker remittances and projected national price appreciation of 25% to 35% by 2031 may support long-term residential demand. Metro Manila’s office vacancy rate improved to 19%, supported by limited new supply and demand beyond the business process outsourcing sector. Retail vacancy is also expected to fall below 10% as household spending recovers. Industrial property remains the strongest segment, led by Central Luzon and the Clark corridor. Rising rents, logistics improvements, e-commerce growth and demand for energy-resilient facilities continue to strengthen investment fundamentals. Outlook Industrial and Clark corridor assets offer the strongest risk-adjusted opportunities. Selected CBD offices, retail properties and discounted condominiums also present improving prospects. Investors should remain selective, prioritising quality assets, strong locations and longer holding periods while monitoring inflation, electricity costs and geopolitical risks. Juwai IQI Newsletter August 2026Download
Philippines Real Estate Shows Stronger Recovery Signals The Philippines property market is entering the second half of 2026 with improving momentum. The US-Iran ceasefire and reopening of the Strait of Hormuz have helped stabilise global oil markets, leading to major fuel rollbacks in the Philippines. This is easing pressure on household budgets and business costs, while also supporting buyer confidence. At the same time, the proposed Japan-Philippines petroleum reserve partnership strengthens the country’s long-term energy security outlook. The residential market remains selective. Metro Manila condominiums are still a buyer’s market, with around 74,000 to 75,300 unsold units. However, developer discounts, rent-to-own schemes and longer payment terms are creating attractive entry opportunities. Supply is also expected to tighten, with only about 3,600 new condo units annually from 2026 to 2028, far below the previous peak average of 13,000 units. Regional markets such as Cavite, Laguna, Cebu, Iloilo and Davao remain stronger performers, with projected annual appreciation of 5% to 7%. Industrial and Commercial Segments Lead Growth Industrial and logistics remain the strongest investment theme. The New Clark City industrial hub is reinforcing the Clark-Pampanga corridor as a key manufacturing and logistics destination, while industrial rents have risen 45% since 2019. Commercial property is also improving. Office demand rose 70% year-on-year in Q1 2026, supported by BPO and IT-BPM expansion. Retail vacancy is expected to fall below 10% by end-2026, while hospitality is benefiting from flight surcharge cuts and route restoration. Outlook The Philippines market is not without challenges, but its fundamentals remain strong. With 115 million people, record OFW remittances, infrastructure expansion and improving energy stability, H2 2026 could mark a clearer recovery phase. Industrial assets, Clark-linked logistics, regional residential corridors and prime income-generating assets are likely to remain the best-positioned opportunities. Download to see insights from other country marketsDownload
Ready to get started?
Get in touch now.
