

Team Leader (Subsales) ∙ United
Alvin Cham
REN37907
About Alvin Cham
凭借丰富的市场知识和卓越的谈判技巧,为您带来非凡的成果。您的置业成功是我的首要任务。准备好将您的置业梦想变为现实了吗?让我们聊聊吧。您的梦想家园正在等待着您。
6 years at IQI
82 transactions
39 properties on sale
3 properties on rent
Alvin Cham Social Links
No social links available.
Alvin Cham's Service Locations
Alvin Cham's Service Locations
My Listings
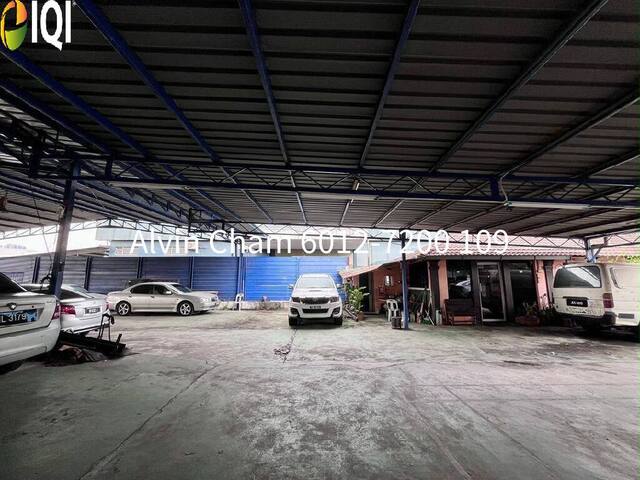
Pasir Gudang Highway
Jalan Pasir Gudang Higway
₱ 280,201 /month
Listed on October 5, 2026
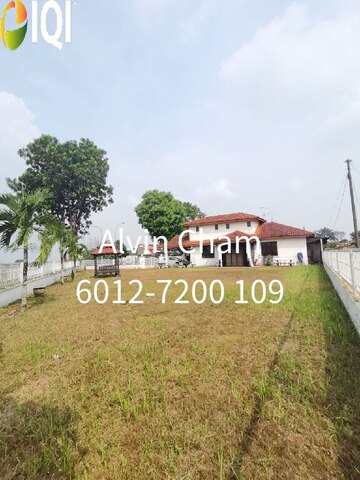
Taman Pelangi Indah
Jalan Ayu
₱ 17,123,370
Listed on October 22, 2026
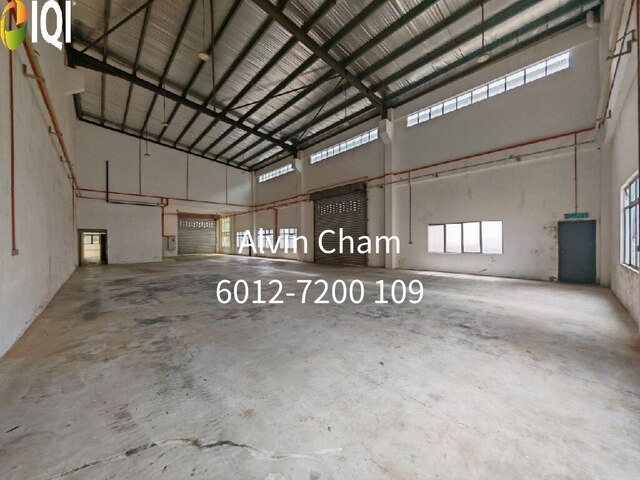
Taman Perindustrian Desa Cemerlang
Jalan Canggih, Taman Desa Cemerlang, Ulu Tiram, Johor
₱ 63,045,135
Listed on October 16, 2026
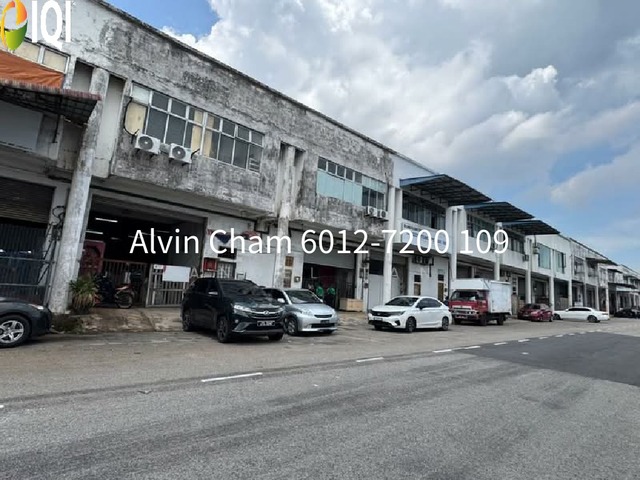
Taman Industri Jaya
Jalan Bistari
₱ 19,925,376
Listed on September 22, 2026
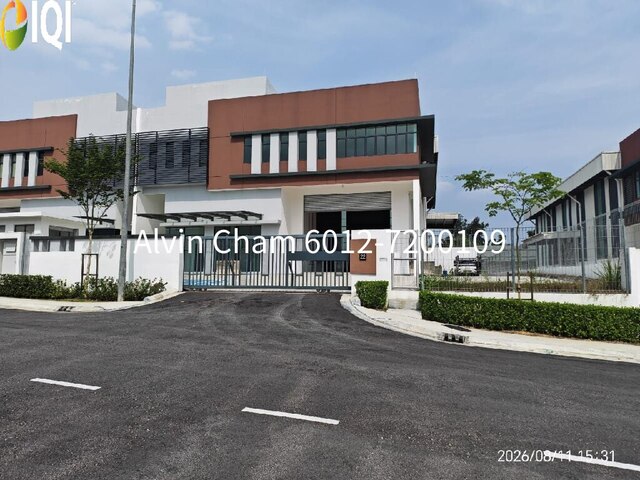
Taman Perindustrian Desa Cemerlang
Jalan Desa Cemerlang
₱ 72,852,156
Listed on September 9, 2026
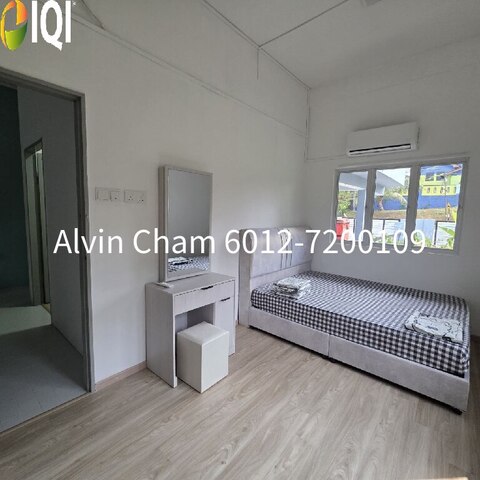
Kampung Bahru
Jalan Abdul Samad
₱ 186,800 /month
Listed on September 21, 2026
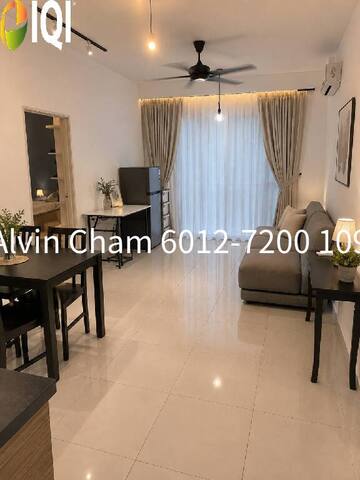
Residensi Masai (Parc Regency)
Jalan Masai Jaya, Off Jalan Masai Baru
₱ 4,825,677
Listed on October 7, 2026
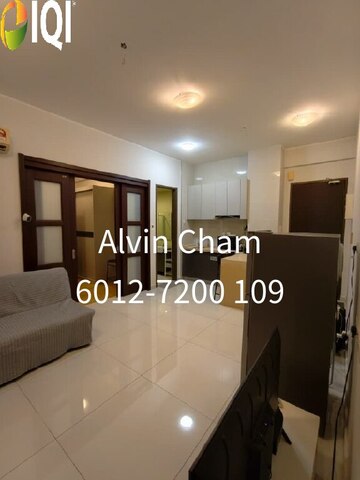
AmberSide @ Country Garden Danga Bay
Danga Bay, Johor Bahru, Johor
₱ 5,432,778
Listed on October 9, 2026
Dedaun Hijau (Greenfield Regency)
Taman Tampoi Indah, Johor Bahru
₱ 6,849,348
Listed on October 5, 2026
Danga Sutera
Jalan Danga Sutera, Taman Sutera Utama, Skudai, Johor
₱ 16,345,035
Listed on October 12, 2026
Taman Kempas Indah
Jalan Kempas Indah, Taman Kempas Indah
₱ 10,585,356
Listed on October 10, 2026
Kawasan Perindustrian SILC
Jalan Gelang Patah
₱ 44,365,095
Listed on October 5, 2026
Scott Towers
Off Jalan Datin Halimah, Larkin
₱ 6,382,347
Listed on October 6, 2026
Nusa Heights (Nusa Puncak)
Jalan Idaman 9, Taman Nusa Idaman, Iskandar Puteri (Nusajaya), Johor
₱ 8,561,685
Listed on September 23, 2026
Eco Business Park 3
Taman Kota Masai, 81700 Pasir Gudang
₱ 29,576,730
Listed on November 6, 2026
Pandan Heights (Residensi Pandan 3)
Jalan Pandan
₱ 7,939,017
Listed on September 30, 2026
Kawasan Perindustrian Cemerlang
Jalan Maju Cemerlang
₱ 101,183,550
Listed on August 28, 2026
Bandar Uda Utama
Jalan Uda Utma
₱ 32,690,070
Listed on October 5, 2026
Neu Suites
Jalan Nipah
₱ 29,390 /month
Listed on October 10, 2026
Taman Desa Cemerlang
alan Saga , taman desa cemerlang, Taman Desa Cemerlang, Ulu Tiram, Johor
₱ 9,931,555
Listed on October 19, 2026
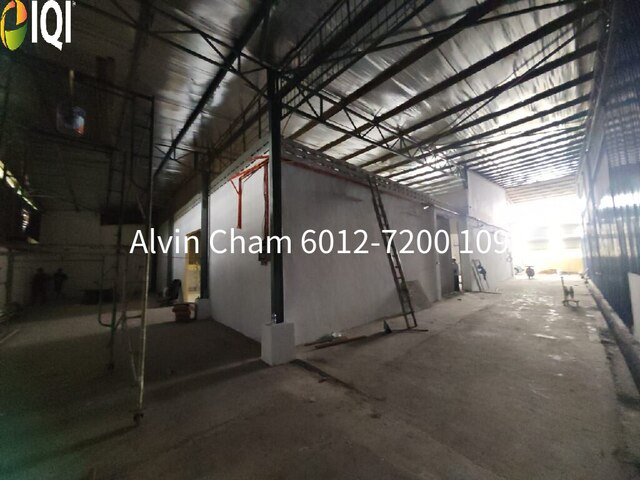
Taman Johor Jaya
Jalan Seroja
₱ 59,153,460
Listed on October 4, 2026
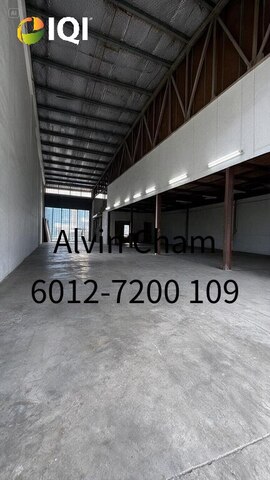
Taman Daya
Jalan Bertam
₱ 19,458,375
Listed on October 30, 2026
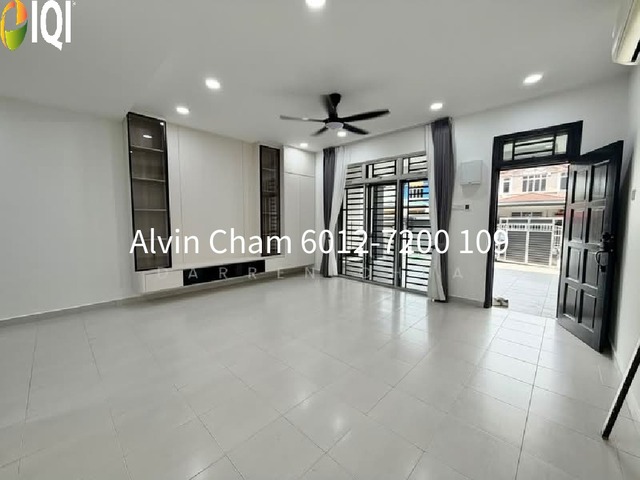
L.A Garden (La Garden Bandar Jaya Putra)
Jln Jaya Putra 5, Bandar Jaya Putra, 81100 Bandar Jaya Putra, Johor Bahru, Johor
₱ 11,955,226
Listed on September 25, 2026
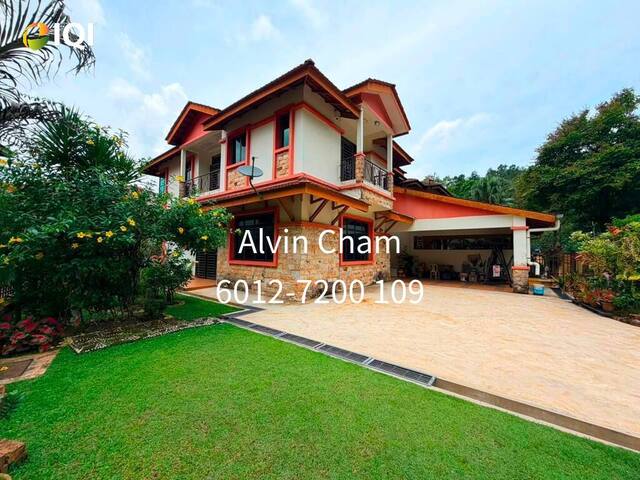
Nusa Idaman
Jalan Nusa Idaman 3, Taman Nusa Idaman, Iskandar Puteri (Nusajaya), Johor
₱ 20,236,710
Listed on October 30, 2026
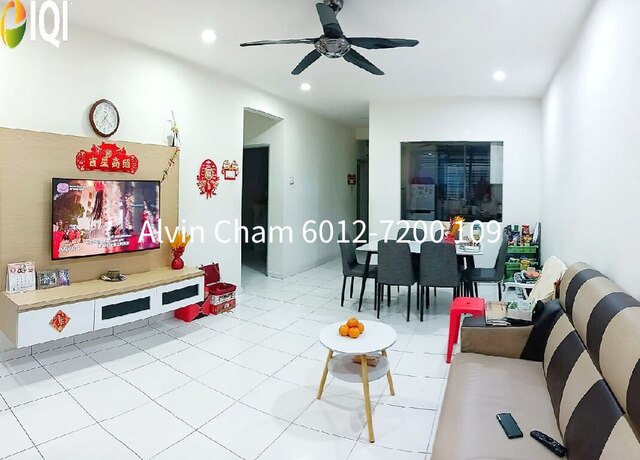
Scott Towers
Off Jalan Datin Halimah, Larkin
₱ 6,226,680
Listed on September 28, 2026
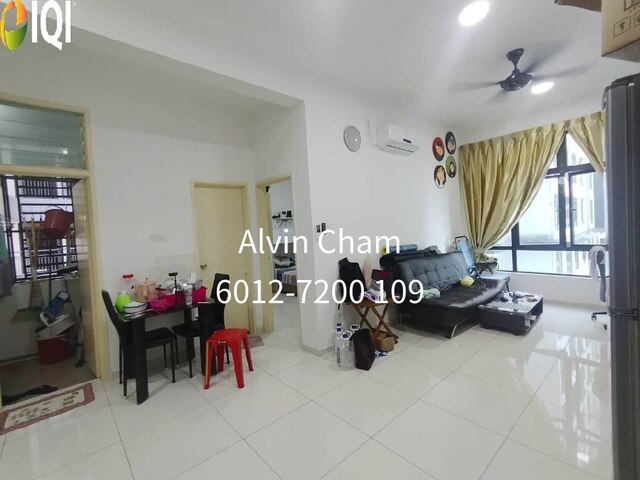
D'Summit Residences
Jln Kempas Utama 2/1, Kempas, Johor Bahru, Johor
₱ 4,327,543
Listed on October 8, 2026
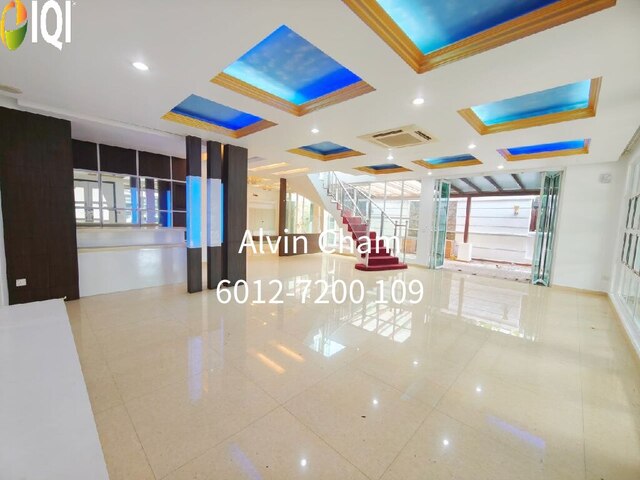
Taman Sutera Utama
Jalan Sutera Pulai 2/1
₱ 25,685,055
Listed on October 12, 2026
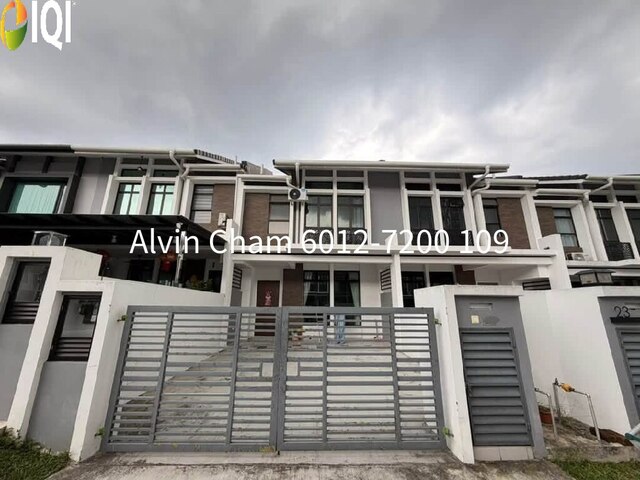
Dahlia @ Seri Austin
Jalan Seri Austin 5
₱ 12,266,560
Listed on September 24, 2026
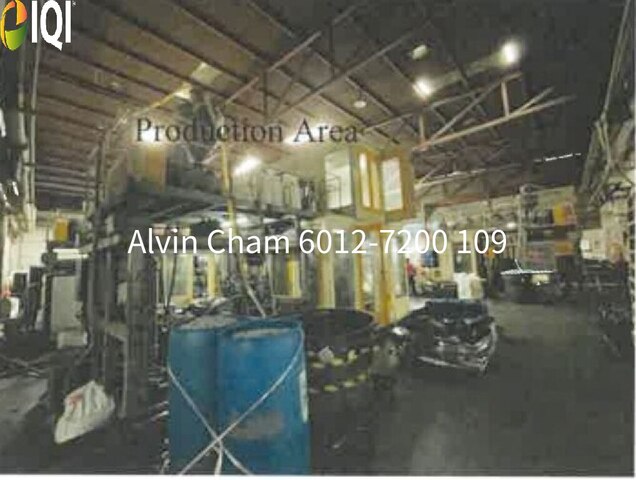
Taman Industri Jaya
Jalan Bistari
₱ 202,367,100
Listed on September 22, 2026
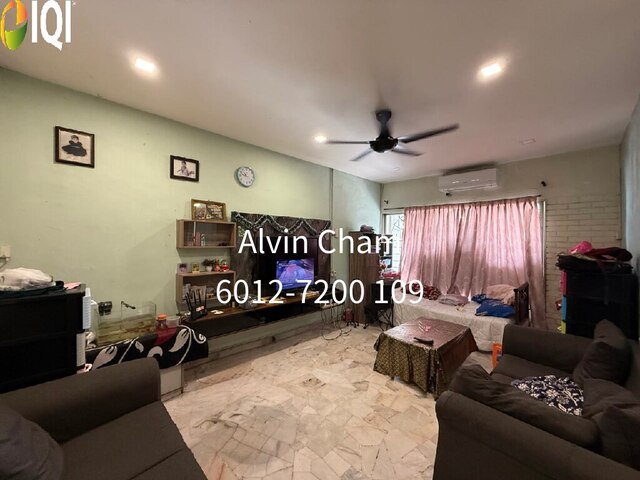
Taman Desa Jaya
Jalan Permatang
₱ 9,028,686
Listed on October 15, 2026
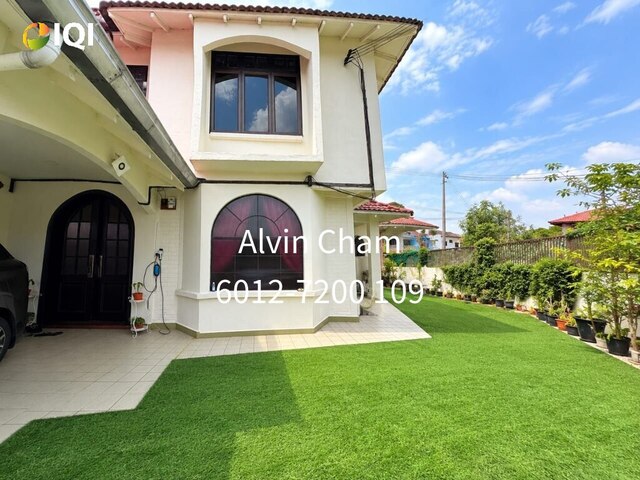
Taman Tun Aminah
Jalan Hang Tuah
₱ 15,068,566
Listed on October 30, 2026
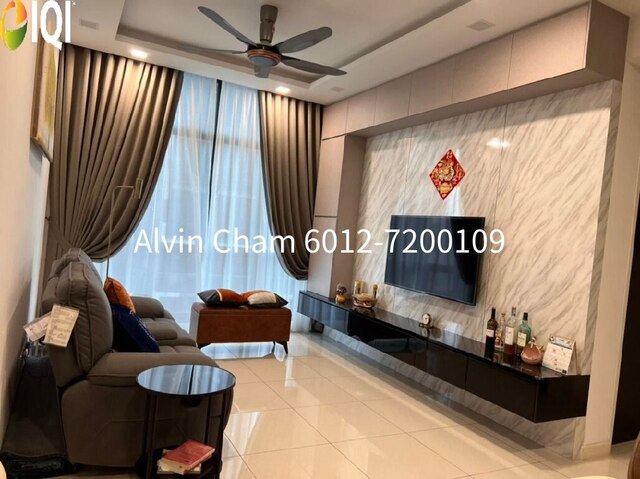
Setia Sky 88 (Pangsapuri Setia 88)
Jalan Dato Abdullah Tahir, Johor Bahru
₱ 10,118,355
Listed on September 21, 2026
Taman Skudai Bahru
Jalan Hang Tuah
₱ 9,931,555
Listed on November 3, 2026
Aspira Gardens
Johor
₱ 25,685,055
Listed on November 3, 2026
South Hills
Jalan Puncak Selatan, Masai, Johor
₱ 12,609,027
Listed on October 4, 2026
D'Summit Residences
Jln Kempas Utama 2/1, Kempas, Johor Bahru, Joho
₱ 8,561,685
Listed on July 17, 2026
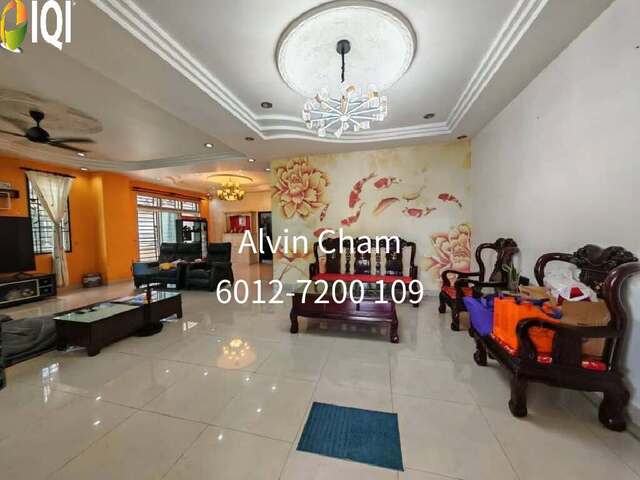
Taman Desa Cemerlang
Jalan Kenanga 4, Taman Desa Cemerlang, Ulu Tiram, Johor
₱ 19,147,041
Listed on October 15, 2026
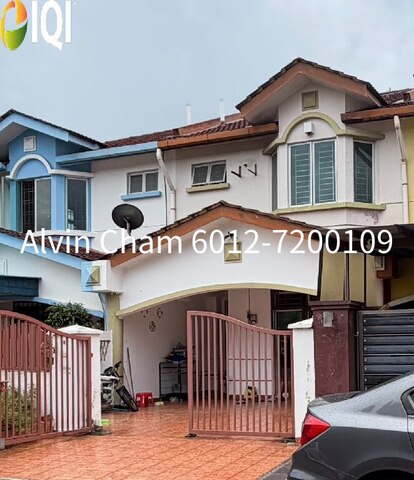
Taman Nusa Bestari 2
Jalan Bestari 6
₱ 11,363,691
Listed on September 21, 2026
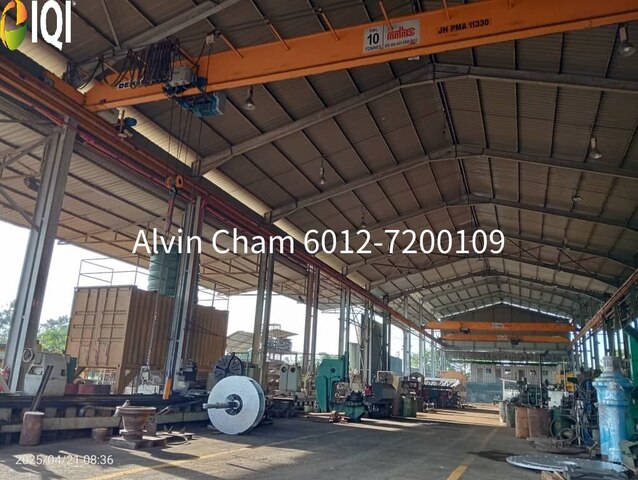
Kampung Seelong Jaya
Jalan Kempas Lama
₱ 373,600,800
Listed on April 25, 2025
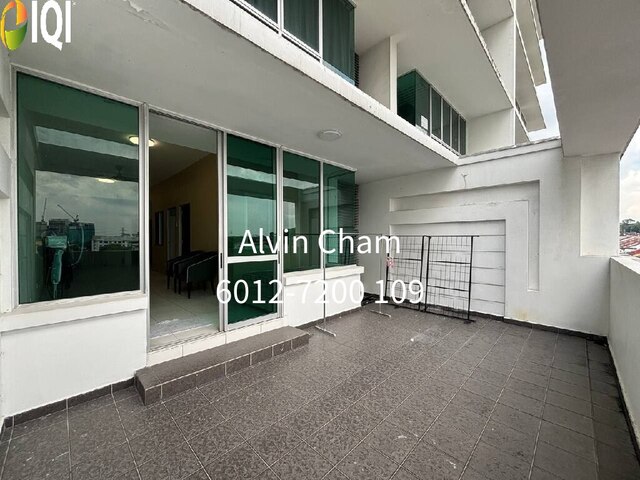
Akademik Suite @ Mount Austin
Jalan Austin Heights Utama
₱ 5,681,846
Listed on October 19, 2026
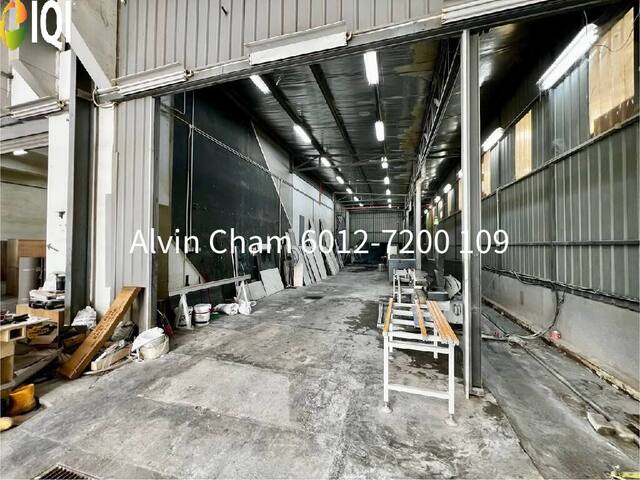
Eco Business Park 1
Jalan Ekoperniagaan 1/5, Eco Business Park 1, Johor Bahru, Johor
₱ 48,256,770
Listed on October 7, 2026
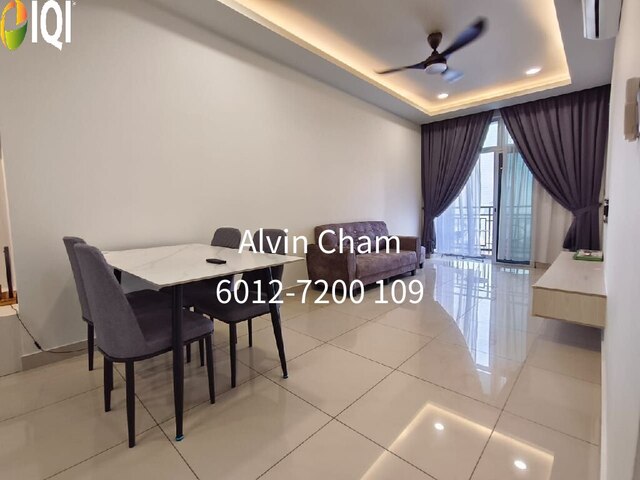
SKS Habitat Apartment, Larkin
Jalan Larkin perdana 2
₱ 7,472,016
Listed on October 16, 2026
Our newly launched projects
Discover the real estate properties in and around Johor Bahru, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Located in Kubang Semang
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from ₱ 225,647,411
Listed on January 23, 2026
 Varied built-up sizes
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 18,739,193
Listed on January 23, 2026
 Located in Simpang Ampat
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₱ 78,067,001
Listed on January 23, 2026
 Located in Bukit Mertajam
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 17,416,024
Listed on January 23, 2026
 Located in Bukit Mertajam
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₱ 12,733,561
Listed on January 23, 2026
 Large land area
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from ₱ 8,561,685
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
Residential Recovery Moves Into Clearer View The Philippine property market is showing stronger signs of recovery, led by a sharp improvement in residential absorption. In Metro Manila, preselling net take-up surged 765% year-on-year in Q1 2026, driven mainly by the economic and affordable segments. As a result, remaining inventory life fell to 6.8 years, down from a peak of 13.4 years in mid-2025. Developers are now prioritising the clearance of ready-for-occupancy stock before launching new projects, while completions are expected to decline from 2027 onward. Vacancy is still projected to reach 25.6% by year-end, but this largely reflects earlier supply decisions rather than current demand conditions. Demand also remains healthy in well-priced fringe locations such as the C5 Corridor and Katipunan, reinforcing the importance of the right combination of product, location and pricing. Commercial and Industrial Demand Adds Depth The recovery is also being supported by stronger commercial demand. The Philippines is ranked as the world’s second-largest GCC delivery location, with the GCC workforce projected to reach around 289,000 professionals across approximately 200 centres in 2026. This is supporting demand for prime CBD offices and key provincial markets. Tourism has also improved, with 3.16 million international arrivals in H1 2026, up 5.4%, while hotel average daily rates rose 2.4%. Industrial remains another strong segment, supported by new logistics supply and PHP 81.4 billion in approved foreign manufacturing pledges. Outlook The Philippines appears to be entering a confirmed recovery phase, but opportunities remain selective. With buyer-friendly pricing gradually being absorbed and future supply becoming more constrained, well-located residential, office and industrial assets may benefit most as the market continues to improve. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Industrial and Commercial Recovery Gains Ground The Philippine property market entered the second half of 2026 with recovery strengthening across industrial, commercial and residential real estate. Industrial property remains the standout segment. First-half merchandise exports reached US$46.72 billion, the strongest performance since 1991, supported by electronics demand linked to the global AI supply chain. This momentum is feeding into a 1,200-hectare industrial land pipeline for 2026 to 2028, while industrial rents have increased 45% since 2019. New demand from EV and battery manufacturers is also supporting the sector. Metro Manila’s office vacancy remained stable at 19%, despite softer leasing volumes, while flexible workspace take-up doubled year-on-year. Retail vacancy is expected to fall below 10% by year-end, while around 3,100 new hotel rooms are scheduled for delivery in 2026. Residential Buyers Still Hold the Advantage The residential market remains firmly buyer-favourable. Inflation eased to 6.2% in July, marking a third consecutive month of improvement, while the BSP was expected to maintain its policy rate at 4.75%. Developers continue to compete for buyers through extended payment terms, rent-to-own structures and effective discounts of 3% to 12%. At the same time, future condominium supply is tightening sharply. Annual completions are expected to average around 3,600 units through 2028, down 72% from the 2017 to 2019 average. Outlook The Philippines is entering a potentially important transition period. Improving inflation, the prospect of lower borrowing costs and a shrinking condominium pipeline could support stronger residential absorption into 2027. Meanwhile, industrial assets remain the strongest structural growth story, supported by exports, manufacturing and infrastructure demand. For investors, the second half of 2026 offers an opportunity to focus on quality industrial assets, flexible commercial space and competitively priced residential properties before financing conditions improve further. The contents of this article were contributed by Dara Ko-Saavedra, Head of IQI Philippines. Download to see insights from other country marketsDownload
Inflation Eases as Market Conditions Improve The Philippines property market entered the second half of 2026 with a gradually improving economic outlook. Inflation declined for a second consecutive month, falling from 7.2% in April to 6.4% in June. Lower fuel and transport costs supported the improvement, while monthly inflation recorded its first decline in a year at -0.3%. The Bangko Sentral ng Pilipinas raised its policy rate to 4.75%, but inflation is expected to ease further through 2028. Economic growth is also forecast to strengthen from 2.8% in Q1 2026 to 4.4% for the full year, supporting future consumption, investment and property demand. Industrial Property Offers the Strongest Prospects Metro Manila condominiums remain a buyer’s market, creating opportunities for buyers seeking discounted properties. New condominium completions are expected to average only 3,600 units annually from 2026 to 2028, significantly below the 13,000-unit annual average recorded between 2017 and 2019. This lower supply pipeline could gradually reduce excess inventory. Developer incentives, strong overseas Filipino worker remittances and projected national price appreciation of 25% to 35% by 2031 may support long-term residential demand. Metro Manila’s office vacancy rate improved to 19%, supported by limited new supply and demand beyond the business process outsourcing sector. Retail vacancy is also expected to fall below 10% as household spending recovers. Industrial property remains the strongest segment, led by Central Luzon and the Clark corridor. Rising rents, logistics improvements, e-commerce growth and demand for energy-resilient facilities continue to strengthen investment fundamentals. Outlook Industrial and Clark corridor assets offer the strongest risk-adjusted opportunities. Selected CBD offices, retail properties and discounted condominiums also present improving prospects. Investors should remain selective, prioritising quality assets, strong locations and longer holding periods while monitoring inflation, electricity costs and geopolitical risks. Juwai IQI Newsletter August 2026Download
Philippines Real Estate Shows Stronger Recovery Signals The Philippines property market is entering the second half of 2026 with improving momentum. The US-Iran ceasefire and reopening of the Strait of Hormuz have helped stabilise global oil markets, leading to major fuel rollbacks in the Philippines. This is easing pressure on household budgets and business costs, while also supporting buyer confidence. At the same time, the proposed Japan-Philippines petroleum reserve partnership strengthens the country’s long-term energy security outlook. The residential market remains selective. Metro Manila condominiums are still a buyer’s market, with around 74,000 to 75,300 unsold units. However, developer discounts, rent-to-own schemes and longer payment terms are creating attractive entry opportunities. Supply is also expected to tighten, with only about 3,600 new condo units annually from 2026 to 2028, far below the previous peak average of 13,000 units. Regional markets such as Cavite, Laguna, Cebu, Iloilo and Davao remain stronger performers, with projected annual appreciation of 5% to 7%. Industrial and Commercial Segments Lead Growth Industrial and logistics remain the strongest investment theme. The New Clark City industrial hub is reinforcing the Clark-Pampanga corridor as a key manufacturing and logistics destination, while industrial rents have risen 45% since 2019. Commercial property is also improving. Office demand rose 70% year-on-year in Q1 2026, supported by BPO and IT-BPM expansion. Retail vacancy is expected to fall below 10% by end-2026, while hospitality is benefiting from flight surcharge cuts and route restoration. Outlook The Philippines market is not without challenges, but its fundamentals remain strong. With 115 million people, record OFW remittances, infrastructure expansion and improving energy stability, H2 2026 could mark a clearer recovery phase. Industrial assets, Clark-linked logistics, regional residential corridors and prime income-generating assets are likely to remain the best-positioned opportunities. Download to see insights from other country marketsDownload
Ready to get started?
Get in touch now.
