Newsletter
Keep yourself update with our current news for Juwai IQI
Saudi Arabia Property Market Outlook 2026: Vision 2030 Sustains Growth
Vision 2030 Continues to Drive Market MomentumSaudi Arabia’s real estate market maintained strong momentum in June 2026, supported by Vision 2030, major infrastructure investment and continued population growth.Demand remains healthy across the residential, commercial, hospitality and logistics sectors, particularly in Riyadh, Jeddah and Dammam.Large government-backed developments, including NEOM, Diriyah Gate, The Red Sea and Qiddiya, continue to attract domestic and international capital. These projects are also creating long-term demand for housing, offices, hospitality assets and supporting infrastructure. Residential and Office Sectors Lead GrowthResidential property remains the market’s largest segment, accounting for an estimated 45% of investment activity. Demand is being supported by homeownership programmes, improved mortgage accessibility and rising urbanisation.Commercial property represents around 25% of investment, while hospitality accounts for 15%. Industrial assets contribute approximately 10%, with mixed-use projects making up the remaining 5%.Office leasing activity is strengthening as corporations expand and multinational companies establish regional headquarters in Riyadh. Industrial and logistics properties are also benefiting from e-commerce growth and increased supply chain investment.Among major cities, Riyadh recorded the highest investment activity index at 100, followed by Jeddah at 82 and Dammam at 65. Makkah and Madinah recorded indices of 58 and 50 respectively.OutlookSaudi Arabia’s property outlook for 2026 to 2028 remains positive.Prime residential locations are expected to record further price appreciation, while office demand should remain supported by regional headquarters expansion. Logistics and industrial developments may outperform as supply chains and e-commerce activity grow.Continued regulatory reforms and Vision 2030 projects are also expected to support higher foreign investment, transaction activity and stable rental growth over the medium term.Download to see insights from other country marketsDownload
30 July
Philippines Property Market Outlook 2026: Industrial Assets Lead as Inflation Eases
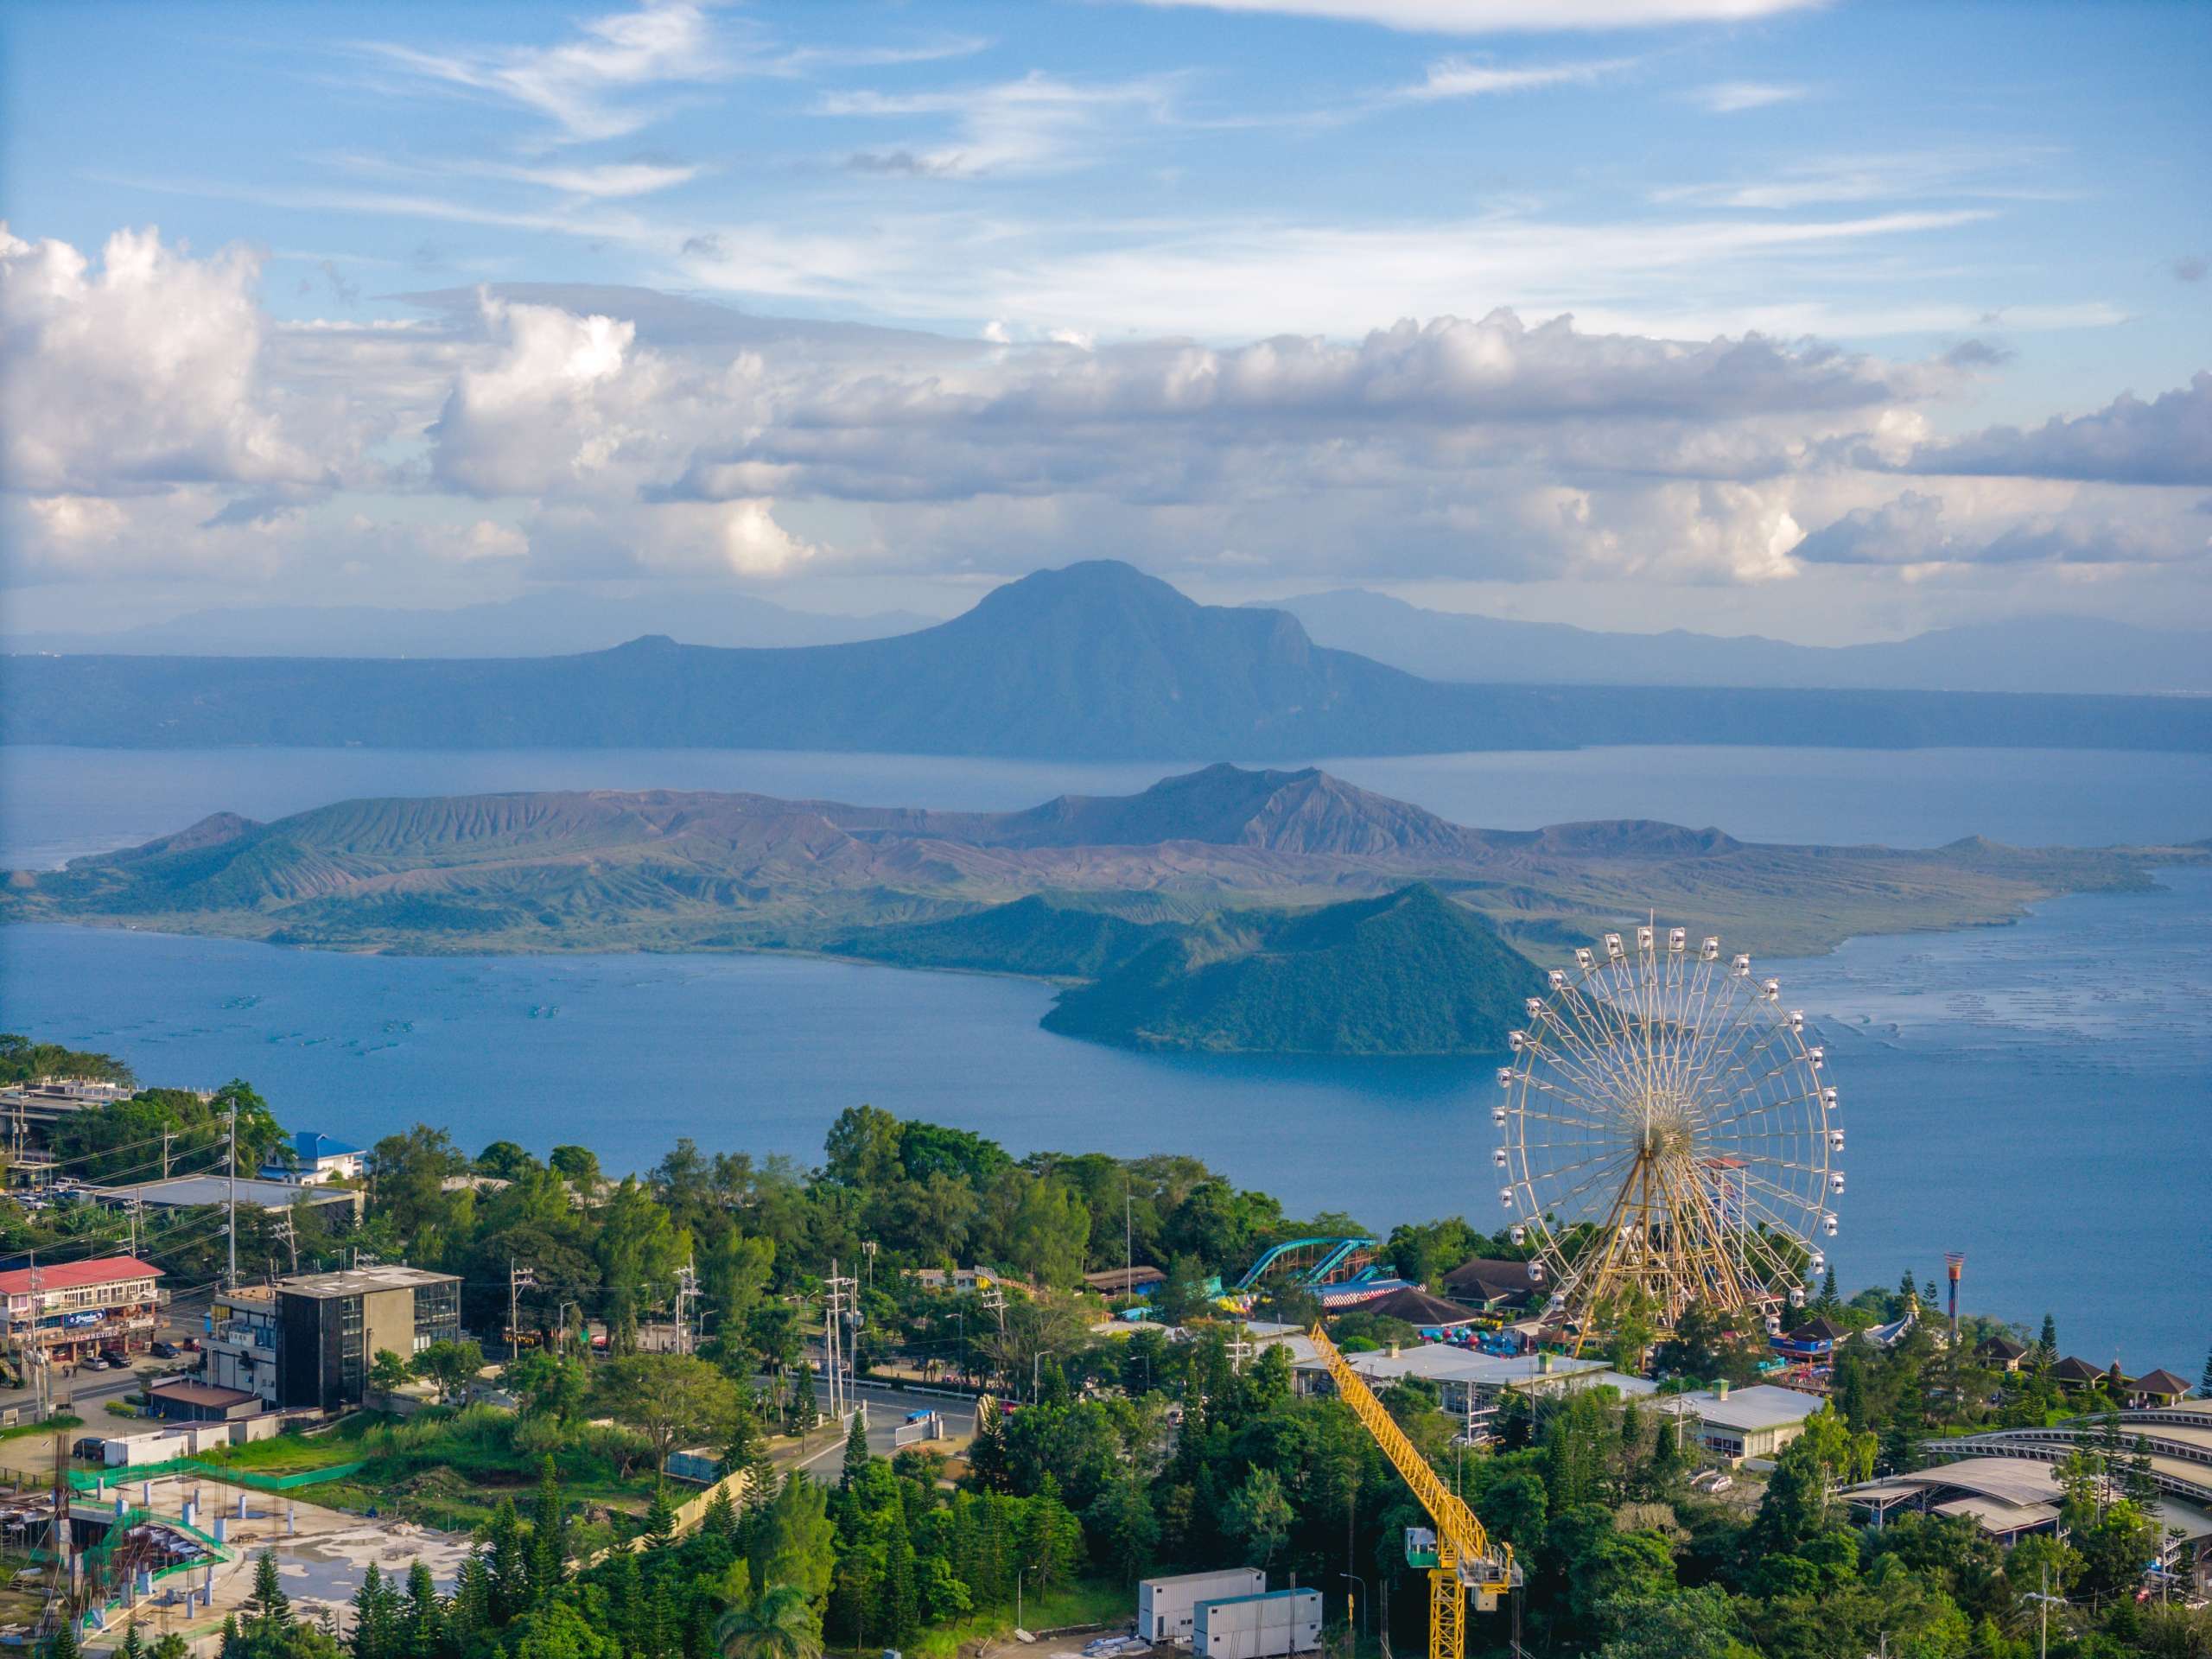
Inflation Eases as Market Conditions ImproveThe Philippines property market entered the second half of 2026 with a gradually improving economic outlook.Inflation declined for a second consecutive month, falling from 7.2% in April to 6.4% in June. Lower fuel and transport costs supported the improvement, while monthly inflation recorded its first decline in a year at -0.3%.The Bangko Sentral ng Pilipinas raised its policy rate to 4.75%, but inflation is expected to ease further through 2028. Economic growth is also forecast to strengthen from 2.8% in Q1 2026 to 4.4% for the full year, supporting future consumption, investment and property demand. Industrial Property Offers the Strongest ProspectsMetro Manila condominiums remain a buyer’s market, creating opportunities for buyers seeking discounted properties. New condominium completions are expected to average only 3,600 units annually from 2026 to 2028, significantly below the 13,000-unit annual average recorded between 2017 and 2019.This lower supply pipeline could gradually reduce excess inventory. Developer incentives, strong overseas Filipino worker remittances and projected national price appreciation of 25% to 35% by 2031 may support long-term residential demand.Metro Manila’s office vacancy rate improved to 19%, supported by limited new supply and demand beyond the business process outsourcing sector. Retail vacancy is also expected to fall below 10% as household spending recovers.Industrial property remains the strongest segment, led by Central Luzon and the Clark corridor. Rising rents, logistics improvements, e-commerce growth and demand for energy-resilient facilities continue to strengthen investment fundamentals.OutlookIndustrial and Clark corridor assets offer the strongest risk-adjusted opportunities.Selected CBD offices, retail properties and discounted condominiums also present improving prospects. Investors should remain selective, prioritising quality assets, strong locations and longer holding periods while monitoring inflation, electricity costs and geopolitical risks.Juwai IQI Newsletter August 2026Download
29 July
2026 Financial Outlook: Lower Oil Prices, Gold Opportunities and Asia Property Growth
Lower Oil Prices Bring Economic ReliefGlobal financial conditions are showing signs of improvement after a turbulent start to 2026. Oil prices fell by more than 20% in June, declining from US$105 to around US$73 per barrel as tensions between the United States and Iran eased and key shipping routes gradually reopened.Lower oil prices could reduce pressure on transport, food and manufacturing costs, offering some relief to households. The global economy is also expected to remain resilient, with projected growth of 2.8% in 2026 and a stronger recovery anticipated in 2027.Gold has also retreated from its January record of US$5,595 to approximately US$4,000. However, forecasts cited in the guide suggest prices could reach between US$4,900 and US$6,000 by year-end, keeping gold relevant as part of a diversified portfolio. Capital Moves Towards Asia-Pacific PropertyInvestors placed a record US$47 billion into Asia-Pacific property during the first quarter of 2026, representing a 31% year-on-year increase.The region’s appeal is supported by stronger potential returns. Savings accounts provide roughly 2.5% annually, while government bonds offer around 4%. In comparison, selected rental properties across Bali, Turkey, Thailand, Malaysia and Vietnam may generate approximately 5% to 8.5% in annual rental yields, before any capital appreciation.Southeast Asia’s projected growth of 4.3% further strengthens its appeal as one of the world’s faster-growing regions.OutlookThe improving economic environment supports a balanced financial strategy rather than concentrating money in one asset.A practical approach may include income-generating property, selected gold exposure and sufficient emergency cash. With energy costs easing and investment activity strengthening across Asia-Pacific, disciplined diversification may help investors capture growth while remaining prepared for future uncertainty.Download to see insights from other country marketsDownload
29 July
Pakistan Property Market Outlook 2026: Karachi Shifts Towards Yield-Driven Growth
Karachi Enters a More Disciplined Market PhaseKarachi’s real estate market is moving towards a more stable and yield-driven investment environment, supported by macroeconomic improvements and major fiscal reforms.As of June 2026, the State Bank of Pakistan maintained its policy rate at 11.50%, while inflation stood at 11.70%. Foreign exchange reserves reached USD 22.04 billion, helping the Pakistani rupee stabilise at approximately PKR 278.16 per US dollar.The FY2026-27 Federal Budget also removed the Section 7E deemed income tax on undeveloped land and reduced the combined transaction withholding tax for active filers to 4.0%. For a PKR 100 million property transaction, this represents potential tax savings of PKR 4 million, lowering entry and exit costs for investors. Yields and Infrastructure Support Investor InterestKarachi’s residential market recorded an average gross rental yield of 6.67% in Q1 2026, reinforcing the city’s appeal to income-focused investors.Selected locations have delivered stronger results. Clifton’s average residential valuation reached PKR 15.6 crore, following 16% year-on-year appreciation. In DHA Phase 8, commercial properties generated estimated net yields of 11% to 13%.DHA Phase 6 also recorded an average net profit of 22% for buy, renovate and resell strategies. Meanwhile, Naya Nazimabad achieved cumulative capital appreciation of 461% between January 2016 and June 2026.Infrastructure remains another important driver, with PKR 100.19 billion allocated to 816 development schemes across Karachi.OutlookPakistan’s property market is becoming more predictable, but investors are likely to remain focused on rental income, established locations and transaction efficiency.Karachi assets offering strong yields, infrastructure access and measurable demand should be better positioned as the market moves away from speculation and towards disciplined, income-led growth.Download to see insights from other country marketsDownload
29 July
Malaysia Property Market Outlook 2026: Buyers Gain the Advantage
Malaysia’s Market Shifts in Favour of BuyersMalaysia’s property market entered the second half of 2026 with a clearer focus on value, affordability and financial discipline.Targeted fuel subsidies and higher living costs have reduced the appeal of speculative property purchases. Instead, the market increasingly rewards buyers who study pricing, location fundamentals and long-term affordability before making a decision.Slower house price growth has also encouraged sellers to set more realistic asking prices. This creates a stronger negotiating position for informed buyers seeking competitively priced assets.Maturing suburban corridors such as Kajang and Bangi South may offer opportunities where pricing, infrastructure and future demand are aligned. The market is not experiencing a broad collapse, but it has become more selective and buyer-friendly. Transit Access and Cash Flow Take PriorityThe rationalisation of fuel subsidies is also changing how Malaysians evaluate property locations. Buyers and tenants are placing greater importance on public transport access, rather than measuring convenience by distance alone.Transit-oriented developments are therefore becoming more important. Properties connected to rail networks may attract stronger rental demand while helping residents reduce their exposure to rising transport costs.Financial management is equally critical. Investors are being encouraged to review existing loans, improve cash flow and avoid excessive borrowing before adding another property to their portfolio.Maintaining sufficient liquidity allows investors to respond when below-market opportunities appear without placing unnecessary pressure on their monthly finances.OutlookThe second half of 2026 is likely to favour the analytical and financially prepared buyer.Properties with realistic pricing, reliable transit access and sustainable holding costs should remain better positioned. Buyers who manage debt carefully and prioritise long-term fundamentals can use the current market adjustment to build a stronger and more resilient property portfolio.Download to see insights from other country marketsDownload
29 July
Chinese Home Buying in Canada Could Reach US$5 Billion Annually
Chinese Buying Continues After Permanent ResidencyCanada’s foreign buyer restrictions may have reduced direct purchases by non-residents, but they do not apply in the same way to permanent residents.According to Juwai IQI Co-Founder and Group Managing Director Daniel Ho, Chinese buyers continue entering Canada’s housing market after obtaining permanent residency. Once they become Canadian permanent residents, they can purchase property under the same rules as other eligible buyers.In 2025, 21,115 Chinese nationals became Canadian permanent residents, representing 5.4% of all new permanent residents. Their share increased to 5.6% in Q1 2026.Across both periods, Canada welcomed 25,805 new Chinese permanent residents, making China the country’s fourth-largest source of new permanent residents. Annual Purchases Estimated at Up to US$4.98 BillionThere is no precise public figure showing how many new permanent residents purchase homes, how quickly they buy or how much they spend.However, Juwai IQI estimates that one year’s intake of new Chinese permanent residents could generate between US$2.52 billion and US$4.98 billion in Canadian residential purchases. This is equivalent to approximately CA$3.6 billion to CA$7.1 billion.The estimate reflects the group’s historic preference for real assets and homeownership. It also excludes Chinese buyers who received permanent residency in earlier years and purchased later, buyers using eligible work permits and those who have since become Canadian citizens.OutlookChinese demand is likely to remain an important part of Canada’s residential market, even when it is not recorded as foreign buying.Future activity will depend on immigration levels, affordability and the time new residents take to move from renting into ownership. Nevertheless, permanent residency will remain a significant pathway connecting Chinese families with Canadian housing demand.Download to see insights from other country marketsDownload
29 July
Italy Property Market Outlook 2026: Prices Rise as the Rate Cycle Turns
Residential Momentum Remains StrongItaly’s housing market entered the second half of 2026 with solid momentum. House prices increased 5.2% year-on-year in Q1 2026, supported by stronger transaction activity and improving demand.New-build prices rose 6.7%, while existing homes gained 4.8%. Residential sales also increased 4.4% year-on-year, with total transactions forecast to grow by approximately 8.4% across 2026.Price growth remained concentrated in major cities. Milan led with a 6.3% increase, followed by Rome at 5.0% and Turin at 3.6%. National asking prices averaged €2,188 per square metre in April.However, the financing environment has become less supportive. The European Central Bank raised its deposit rate to 2.25% in June 2026, weakening the lower-cost mortgage conditions that supported the earlier recovery. Quality Assets Continue to Attract CapitalHigher interest rates have not significantly reduced demand for premium assets. Commercial property investment reached €12.5 billion in 2025, up 23% year-on-year, with international investors contributing 58% of total capital.Luxury property also remained resilient. International buyers now account for around 35% of Italy’s prime market, supported by continued demand for lifestyle properties and high-net-worth relocation.Residential rental fundamentals remain attractive, with average gross yields of 7.23% nationally. Yields ranged from 9.17% in Catania to 5.26% in Milan.Competition is strongest for Grade-A offices, energy-efficient buildings and prime coastal properties, where limited supply continues to support values.OutlookItaly’s property market is expected to remain positive but more selective.Higher financing costs may slow leveraged purchases, while cash-rich buyers and international investors should remain active. Well-located, energy-efficient and income-producing assets are likely to outperform as the wider market moves towards more measured growth.Download to see insights from other country marketsDownload
29 July
Malaysia Property Outlook 2026: How Energy Investment Is Supporting Regional Demand
Energy Investment Supports Property DemandMalaysia’s oil and gas industry remains resilient, supported by upstream capital commitments from PETRONAS, Shell, ExxonMobil and ConocoPhillips.The PETRONAS Activity Outlook 2025 to 2027 projects continued offshore maintenance demand, with Dayang Enterprise securing RM4 billion in contracts. Major energy hubs such as Bintulu, Kerteh, Pengerang and Sabah’s deepwater fields remain central to industry activity.This investment extends beyond the energy sector. Operational centres in Kuala Lumpur, Selangor and Sarawak continue to support steady demand for residential and commercial property from companies, workers and related service providers.The energy ecosystem also includes engineering, logistics, offshore services and project management companies, creating a wider economic effect across key regional markets. Johor and Sabah Benefit From Regional GrowthJohor Bahru continues to show how energy and infrastructure development can influence property performance.Serviced apartment values increased 20.4%, while double-storey terrace properties rose 8.6% in Q2 2025. This growth was supported by the Johor-Singapore Special Economic Zone and activity surrounding the Pengerang Integrated Complex.Sabah is also benefiting from stronger energy activity. A 4.9% rebound in the oil and gas sector helped lift the state’s gross domestic product to RM88.8 billion.These developments suggest that property demand is increasingly linked to employment creation, infrastructure investment and the expansion of supporting industries around established energy hubs.OutlookMalaysia’s energy sector should remain a steady driver of selected property markets.Locations connected to major oil and gas operations may continue to attract residential and commercial demand, particularly where infrastructure, employment and supporting services are expanding. Investors should focus on established operational hubs and areas with clear long-term economic activity rather than relying on short-term price movements.Download to see insights from other country marketsDownload
29 July

