

Leader (Subsales) ∙ United
Christine Tan
REN56919
About Christine Tan
Christine Tan (REN 56919) is an IQI Realty real estate negotiator helping buyers, sellers, landlords and investors buy, sell, rent or lease residential, commercial and industrial property in Shah Alam, Petaling Jaya, Subang Jaya and Kuala Lumpur. Her property experience includes houses, condominiums... Christine Tan (REN 56919) is an IQI Realty real estate negotiator helping buyers, sellers, landlords and investors buy, sell, rent or lease residential, commercial and industrial property in Shah Alam, Petaling Jaya, Subang Jaya and Kuala Lumpur. Her property experience includes houses, condominiums, shop lots, offices, factories and land. She assists with property searches and viewings, marketing, rental enquiries, negotiation and transaction support. With a background in regional finance, Christine brings a practical, numbers-aware approach to comparing property options and planning next steps. Contact Christine to discuss your property needs.
4 years at IQI
162 transactions
21 properties on sale
7 properties on rent
Christine Tan Social Links
Christine Tan's Service Locations
Christine Tan's Service Locations
My Listings
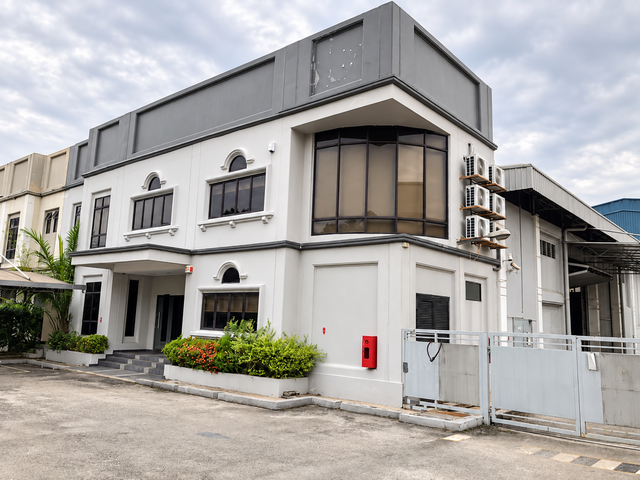
Taman Sains Selangor 1
Jalan Teknologi 3
₫ 222,578,426 /month
Listed on October 28, 2026
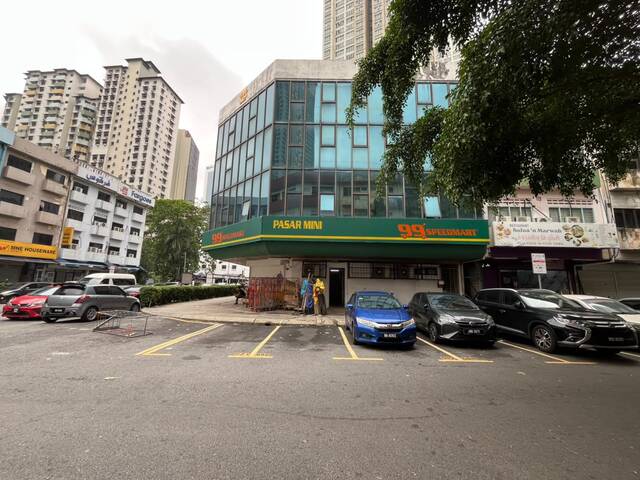
Jalan Tun Razak
Jalan Tun Razak
₫ 13,354,705,560
Listed on October 12, 2026
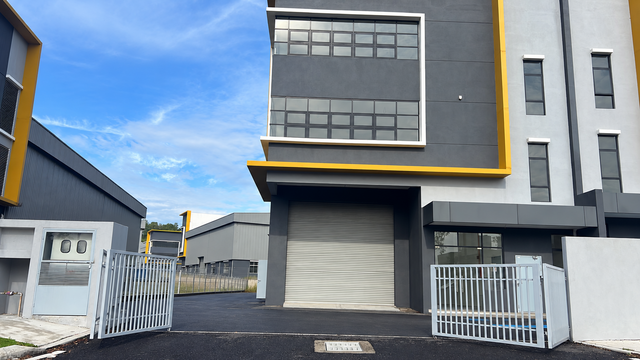
XME Business Park
Jalan Platinum 5, Nilai Impian, Nilai, Negeri Sembilan
₫ 31,160,979,640
Listed on October 25, 2026
2 Storey Bungalow @ Ampang
Jalan Ampang Ulu 3, Ampang Hilir, Ampang, 55000, Kuala Lumpur
₫ 31,796,918,000
Listed on September 27, 2023
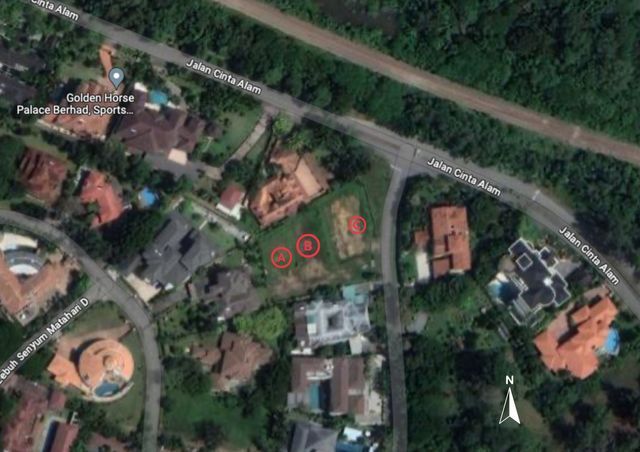
Country Heights, Kajang land for sale
Lorong Cinta Alam
₫ 8,388,026,968
Listed on August 22, 2023
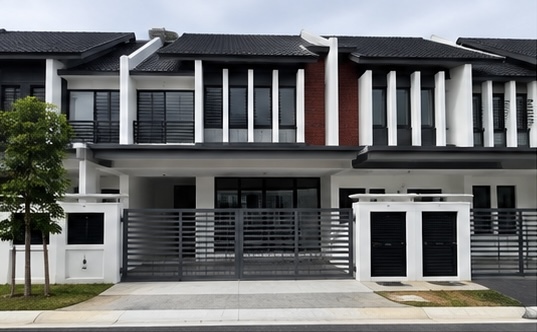
Elmina Valley 2
Elmina Valley 2, Jalan Metafasa U16
₫ 4,960,319,208
Listed on October 8, 2026
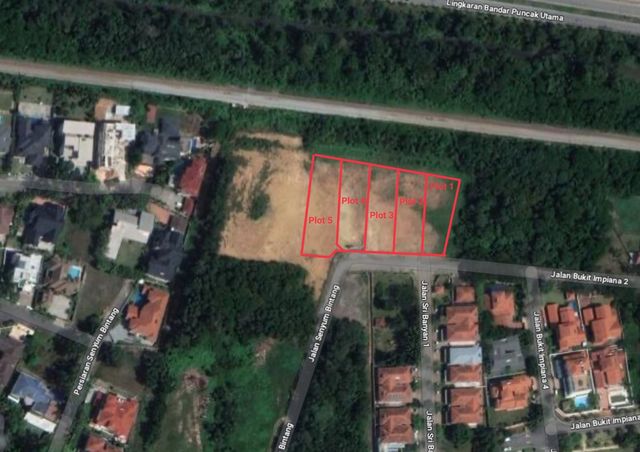
Country Heights, Kajang land for sale
Jalan Senyum Bintang
₫ 9,539,075,400
Listed on August 22, 2023
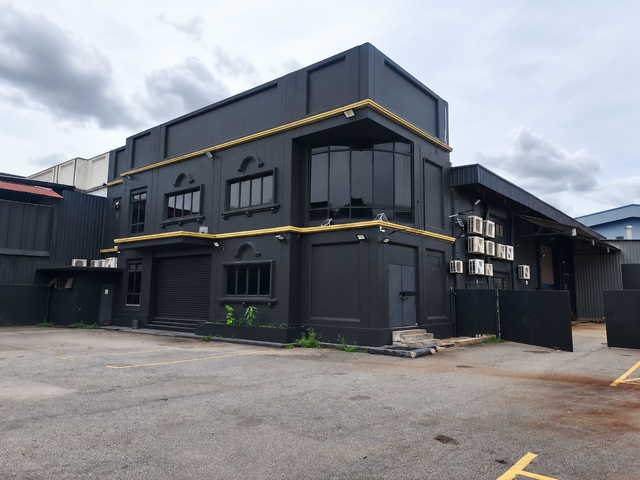
Kota Damansara Factory for rent
Jalan Teknologi 3
₫ 241,656,577 /month
Listed on October 29, 2026
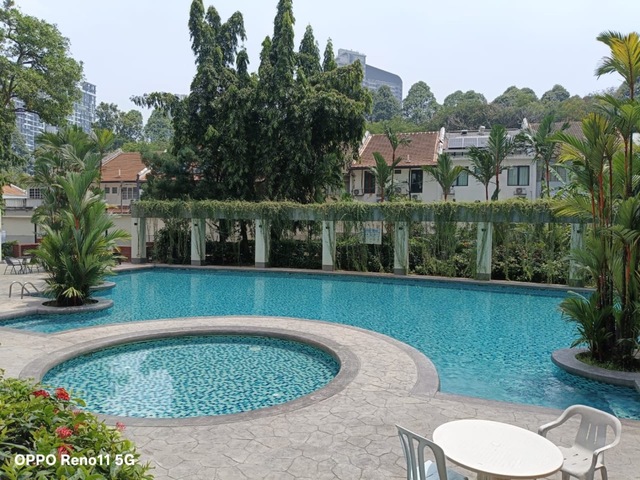
Maxwell Towers Condominium, Petaling Jaya for sale
Jalan 5/58, Bukit Gasing
₫ 4,133,599,340
Listed on October 29, 2026
park 51 residency for sale
Jalan 51A/241, Seksyen 51A
₫ 2,798,128,784 /month
Listed on April 15, 2026
Persiraran Atmosfera, Seksyen U5, Shah Alam
Persiraran Atmosfera, Seksyen U5, Shah Alam
₫ 22,257,843 /month
Listed on October 27, 2026
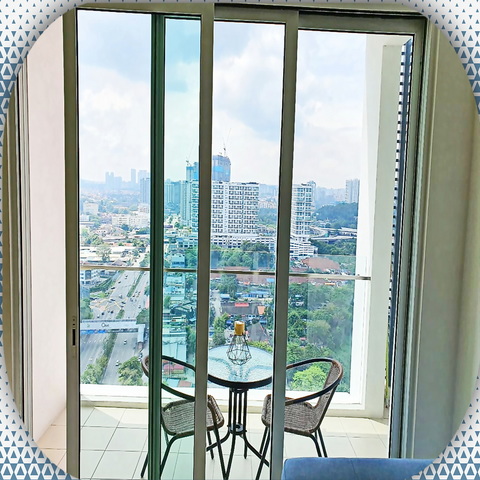
Southbank Residence
Old Klang Road
₫ 3,688,442,488
Listed on October 20, 2023
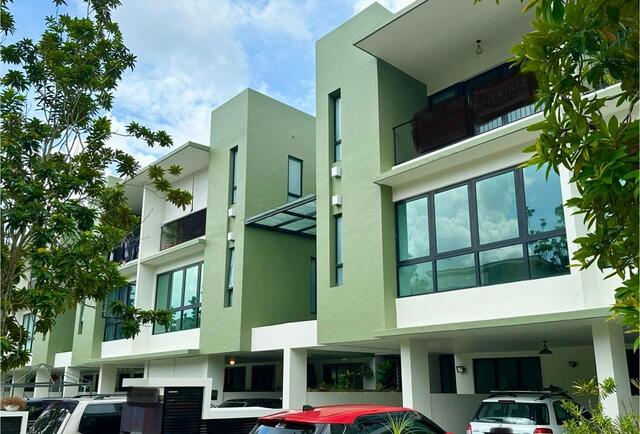
Primer Garden Town Villas @ Cahaya SPK
Jalan Hijau Pelangi U9/55
₫ 4,769,537,700
Listed on July 30, 2026
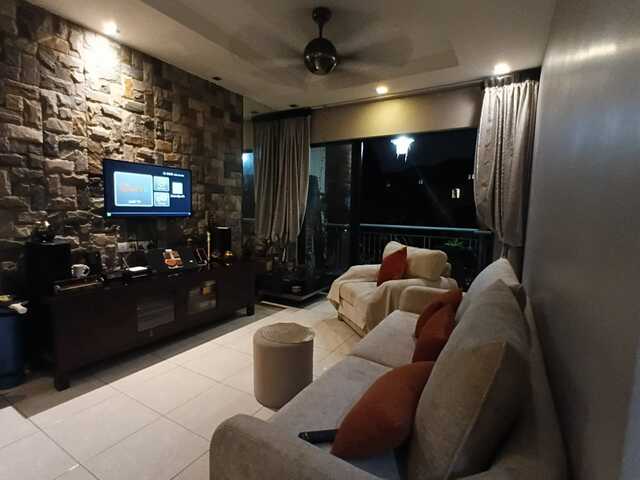
Casa Indah 1
Casa Indah 1 Condominium, 2A Jalan Persiaran Surian, Tropicana Indah, 47410 Petaling Jaya, Selangor
₫ 4,820,412,769
Listed on October 26, 2026
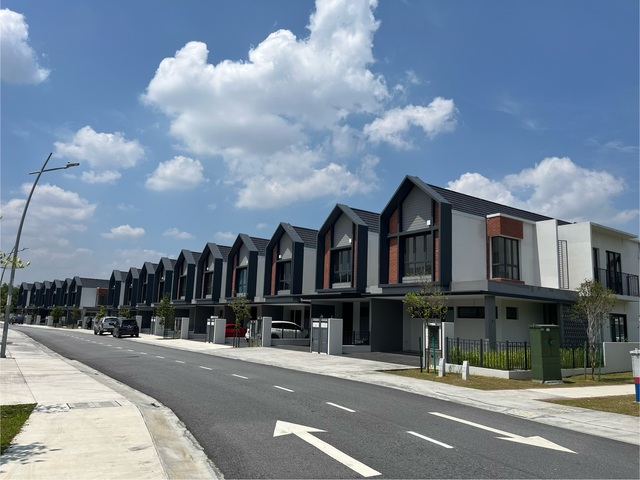
ilham residence for sale
Ilham Residence
₫ 6,995,321,960
Listed on March 22, 2025
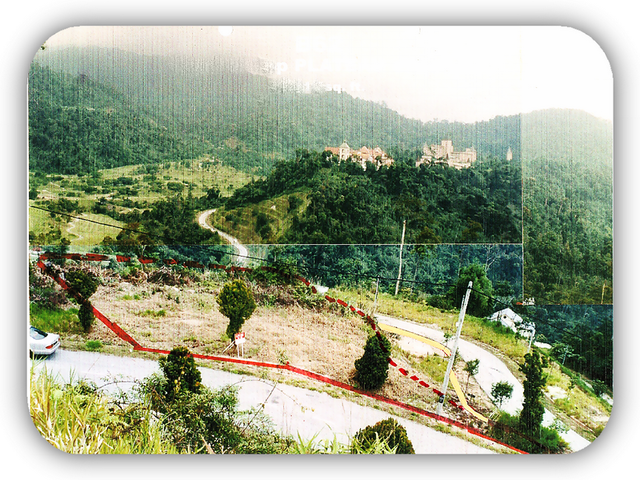
Bungalow Land @ Berjaya Hill Resort, Bukit Tinggi
Jalan Jati 9, Berjaya Hill Resort, Bukit Tinggi, Bentong, 28750, Pahang
₫ 8,968,816,754
Listed on October 6, 2023
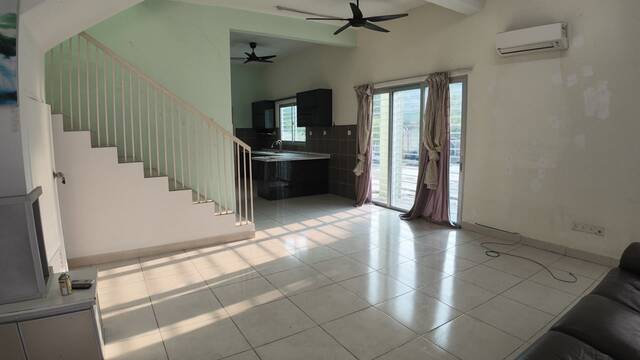
Jalan Ceri, Bandar Hillpark, Puncak Alam
Jalan Ceri, Bandar Hillpark, Puncak Alam
₫ 4,769,537,700
Listed on October 6, 2026
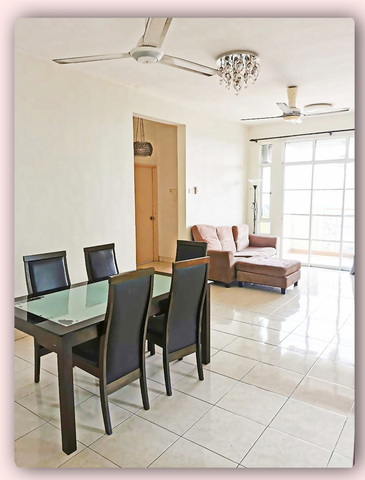
Kelana Sentral
Jalan SS 6/12
₫ 2,480,159,604
Listed on October 14, 2023
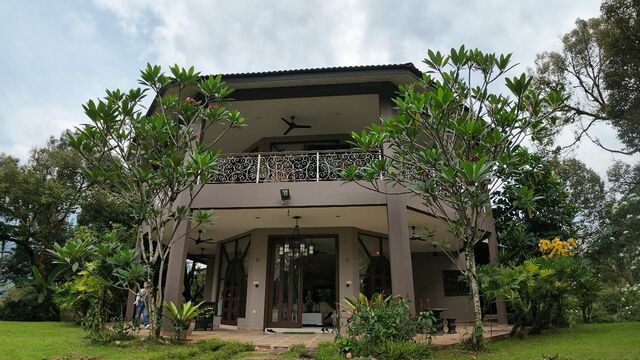
raub durian land for sale
Jalan Tras Raub 27600 Pahang
₫ 146,265,822,800 /month
Listed on June 18, 2026
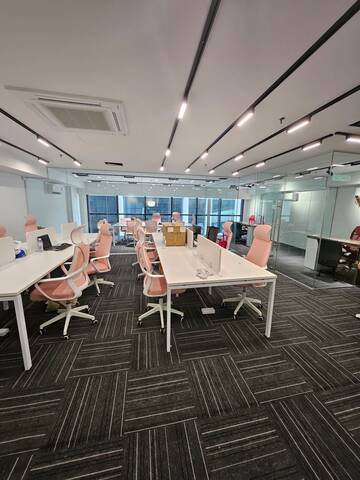
EmHub Kota Damansara
EmHub Kota Damansara
₫ 19,078,150,800
Listed on October 7, 2026
Bandar Utama
Selangor
₫ 9,539,075,400
Listed on October 7, 2026
Perdana View Condominium
Jalan PJU 8/1
₫ 2,543,753,440
Listed on August 3, 2023
Maxwell Towers
Jalan 5/58, Bukit Gasing
₫ 4,578,756,192
Listed on June 27, 2023
Raub, Pahang
Raub, Pahang
₫ 18,442,212,440
Listed on September 29, 2026
Parklane Commercial Hub
SS7, Kelana Jaya, Petaling Jaya, Selangor
₫ 19,078,150,800
Listed on September 28, 2023
EmHub Kota Damansara for Sale
EmHub Kota Damansara
₫ 12,400,798,020
Listed on July 21, 2026
Univ 360 placecondo, Seri Kembangan for sale
Univ 360 place condo, Seri Kembangan for sale
₫ 3,179,691,800 /month
Listed on October 22, 2026
bukit tinggi bungalow for sale
Bukit Tinggi Resort, 28750 Bentong, Pahang
₫ 34,976,609,800 /month
Listed on June 16, 2026
Our newly launched projects
Discover the real estate properties in and around Kuala Lumpur, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Located in Kubang Semang
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from ₫ 92,182,572,161
Listed on January 23, 2026
 Located in Bukit Minyak
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₫ 7,655,425,978
Listed on January 23, 2026
 Industrial project type
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₫ 31,892,308,754
Listed on January 23, 2026
 Spacious land area
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₫ 7,114,878,372
Listed on January 23, 2026
 Larger built-up area
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₫ 5,201,975,785
Listed on January 23, 2026
 Large land area
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from ₫ 3,497,660,980
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
5 Oct, 2026
Vietnam Property Market October 2026: Policy Reform Reshapes a Resilient but Selective Market
Policy Reform Takes Centre Stage Vietnam’s residential market is entering the final quarter of 2026 with policy, rather than pricing, driving the conversation. Resolution 21-NQ/TW is set to shape the next round of Land Law and housing amendments, including proposals linking apartment use to a building’s service life and placing greater reconstruction obligations on owners. The changes could also introduce heavier taxation on excess property profits and vacant or unused assets, while land allocation may increasingly favour commercial apartment supply. MBS Research expects some new apartment projects could shift toward 50–99-year tenures, although implementing rules have not yet been issued. Despite the uncertainty, activity remains substantial. Nearly 34,000 new homes were launched nationwide in Q2, with around 19,600 units sold, equivalent to an absorption rate of approximately 58%. Average primary apartment prices reached around VND 80 million per sqm, up 10% from 2025. Strong Economy Meets Financing Pressure Hanoi illustrates the market’s growing divide. Q2 sales fell 45% year-on-year, even as luxury-led launches pushed primary prices up 36% to about US$4,659 per sqm. Mortgage rates of 12–14% remain the biggest obstacle for first-time buyers. At the same time, Vietnam’s macroeconomic backdrop remains strong. GDP grew 8.39% year-on-year in Q2, while registered FDI reached US$40.63 billion in the first eight months, up 55.4%. Of this, US$5.32 billion was committed to real estate. Outlook Vietnam is likely to remain a selective, end-user-led market rather than enter a broad rally. High financing costs and new legal considerations will make cash strength, legal clarity and land-backed assets increasingly important. For buyers and investors, due diligence around ownership structure, land-use rights and project legality will matter as much as location and product quality. Vietnam, October 2026 The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
Hanoi Apartment Market Faces Resale Pressure Hanoi’s apartment market is entering a more cautious phase as resale pressure increases among investors who bought off-plan or during construction with short-term flipping strategies. After several years of strong price growth, market conditions have cooled. Capital gains are no longer guaranteed, while the end of mortgage grace periods is exposing some investors to higher floating interest rates and heavier repayment obligations. This is encouraging more owners to sell, with liquidity and debt reduction becoming a greater priority than maximising returns. According to market data cited in the report, asking prices at several Hanoi projects have already corrected from their previous peaks. Imperia Sola Park fell around 12.6%, Lumi Hanoi declined approximately 9.5%, while Kepler Land recorded an 8.6% correction. Market Shifts From Speculation to Liquidity The change marks an important shift in Vietnam’s residential market. Some leveraged investors are no longer holding properties in expectation of further short-term appreciation. Instead, they are looking to exit quickly, reduce debt exposure and, in some cases, accept losses. For genuine homebuyers and investors with stronger cash positions, this may create improved negotiating conditions in Hanoi’s secondary apartment market. Rather than competing in a rapidly rising market, buyers may now have greater scope to negotiate on properties where sellers are under financing pressure. Outlook Hanoi’s apartment market is likely to remain more selective and liquidity-driven in the near term. Resale pressure could continue to create opportunities for buyers who have sufficient cash and are willing to negotiate carefully. The key advantage is shifting towards financially prepared buyers, particularly those able to identify motivated sellers and acquire quality secondary-market units at prices below previous market peaks. The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
30 Jul, 2026
Vietnam Property Market Outlook 2026: Infrastructure Corridors Lead the Next Growth Cycle
Vietnam’s Housing Market Enters a Selective Reset Vietnam’s residential market entered August 2026 in a period of consolidation. Prices remain relatively firm, but transaction activity is slower as buyers become more selective and borrowing costs stay elevated. During Q2 2026, developers launched approximately 12,000 primary condominiums across the enlarged Ho Chi Minh City market and more than 4,000 units in Hanoi. However, luxury absorption remained below 30% in Ho Chi Minh City, while Hanoi’s take-up rate eased to around 20%. Inner-city primary prices reached approximately USD 5,400 to USD 9,500 per square metre. Pressure was more visible in the secondary market, where prices declined 5% to 8% in Ho Chi Minh City and by as much as 12% in parts of Hanoi. Floating mortgage rates of 13% to 16% are encouraging some owners to lower asking prices. However, the market has not experienced widespread distress, while the new land-price framework is helping maintain a floor under development costs and headline prices. Infrastructure Redirects Property Demand Vietnam has approximately 234 major infrastructure projects worth VND 3.4 quadrillion underway. These investments are shifting demand from crowded central districts towards better-connected suburban and regional corridors. In the south, growth is concentrating around the Ho Chi Minh City and Dong Nai corridor, supported by Long Thanh International Airport, new ring roads, expressways and Metro Line 1. Northern demand is moving towards Hanoi’s gateway districts and neighbouring Hung Yen and Bac Ninh. Da Nang is also showing stronger primary-market activity, supported by limited prime coastal supply. Outlook Vietnam’s next property cycle is expected to favour patience and careful asset selection rather than short-term speculation. With average gross rental yields near 3.85%, investment returns will depend increasingly on infrastructure-led capital appreciation. Legally clear projects with strong connectivity and genuine end-user demand should remain best positioned, particularly for buyers with sufficient holding power and a multi-year investment horizon. Download to see insights from other country marketsDownload
Vietnam Residential Market Enters a More Selective Cycle Vietnam’s residential market opened 2026 in a transition phase, with prices still rising but liquidity cooling. This suggests the market is moving away from easy speculative gains toward a more disciplined cycle. Residential prices rose around 12% year-on-year in Q1 2026, while liquidity fell nearly 40%. However, there was no sign of distress selling, pointing to a healthy reset rather than a sharp downturn. Primary condominium prices reached new highs across major cities. In Hanoi, average prices were around USD 3,950 per sqm, up 30% year-on-year. In post-merger Ho Chi Minh City, prices averaged around USD 3,900 per sqm, supported by new supply and limited premium stock. Supply also improved. Ho Chi Minh City recorded around 8,010 new condo launches, up 104% year-on-year. Yet affordability remains the key challenge, with much of the new supply priced above the level affordable to mass-market buyers. Strong Fundamentals, But Investors Are More Careful Vietnam’s underlying fundamentals remain supportive. The economy grew 8.02% in 2025, while real estate FDI reached USD 389.5 million in Q1 2026, representing around 7.2% of total inflows. However, investor behaviour is changing. Demand is now concentrating on projects with clear legal status, reliable construction progress and long-term value. Satellite locations such as Binh Duong and Ba Ria-Vung Tau are gaining attention as central city prices continue to stretch. Outlook Vietnam’s property market is expected to remain attractive, but more selective. With average gross rental yields at around 3.85%, the market is less of a pure income play and more of a capital appreciation and infrastructure-led growth story. Buyers with strong holding power, careful project selection and a long-term view are likely to be better positioned than short-term speculators. Download to see insights from other country marketsDownload
Ready to get started?
Get in touch now.
