

Leader ∙ Elite
Windz Neom
REN28801
Leader ∙ Elite
Windz Neom
REN28801
About Windz Neom
I'm striving for excellence in the property industry. With my 9 years of Real Estate experiences, I would definitely give you the best service ever for your real estate matters. One of my favourite Quote - Service Above Self !My mission is to put clients’ interests above my own, providing the highe... I'm striving for excellence in the property industry. With my 9 years of Real Estate experiences, I would definitely give you the best service ever for your real estate matters. One of my favourite Quote - Service Above Self !My mission is to put clients’ interests above my own, providing the highest level of HONESTY and EXPERTISE. My vision is to Provides an EXCELLENT & CONSISTENT customer experience 100% of the time. Be a PROFESSIONAL advisor that DIFFERENT from the rest.
2 years at IQI
35 properties on sale
13 properties on rent
Contact Windz Neom
Windz Neom Social Links
Windz Neom's Service Locations
Windz Neom's Service Locations
My Listings
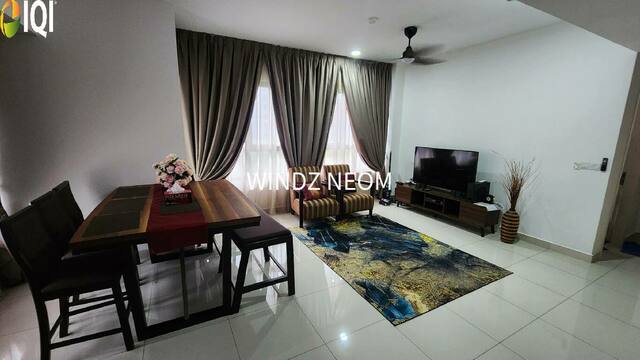
Paisley Serviced Residences @ Tropicana Metropark
Off Persiaran Teknologi Subang, Tropicana Metropark
₫ 4,767,186,975
Listed on May 20, 2026

Bangsar Hill Park
Lorong Maarof
₫ 41,315,620 /month
Listed on August 15, 2025
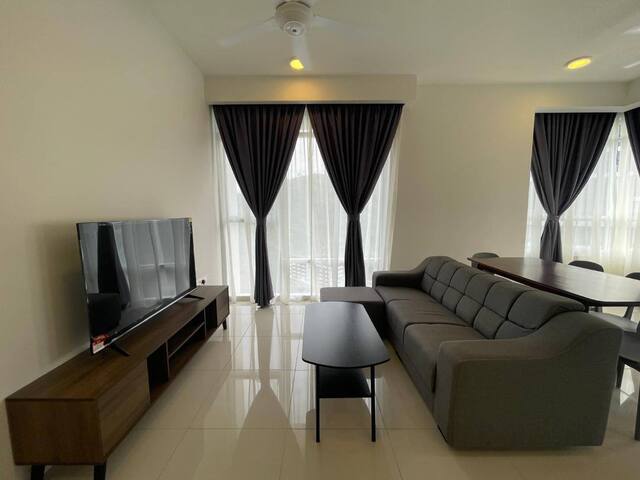
The Ridge @ KL East (Residensi Rabung KL Timur)
PERSIARAN MELATI KUARZA
₫ 17,161,873 /month
Listed on July 27, 2026
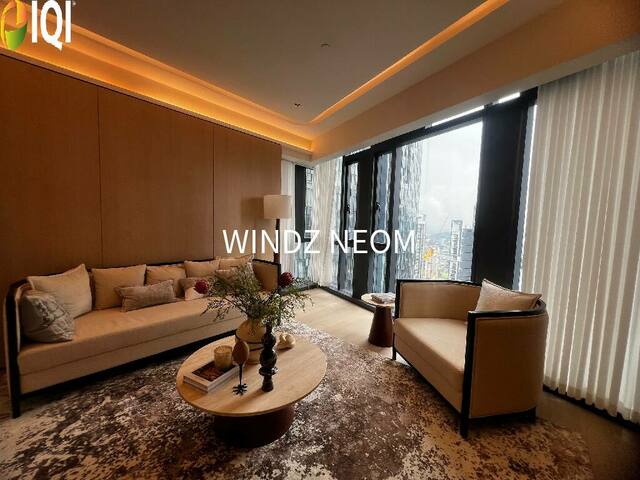
Star Residences
Jalan Yap Kwan Seng, Off Jalan Ampang
₫ 9,725,061,429
Listed on January 6, 2026
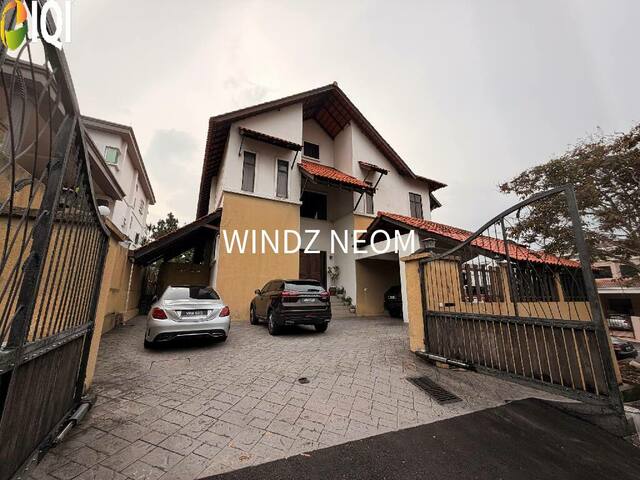
Jalan Enak
Happy Garden
₫ 38,137,495,800
Listed on April 7, 2026

The Tropika Bukit Jalil
Jalan Jalil Perkasa 7
₫ 8,771,624,034
Listed on July 2, 2026
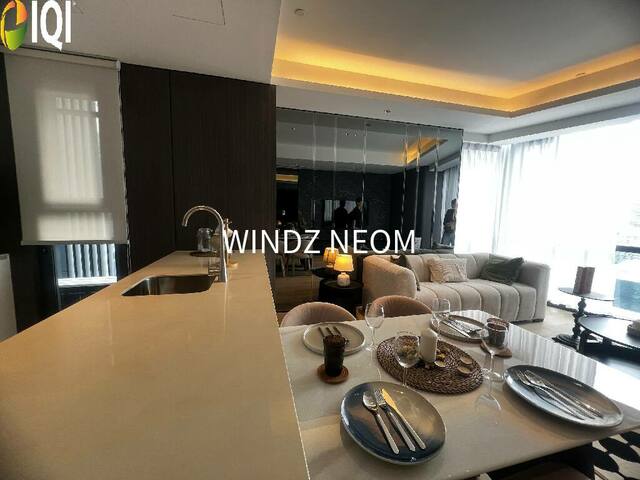
Star Residences
Jalan Yap Kwan Seng, Off Jalan Ampang
₫ 13,983,748,460
Listed on January 7, 2026
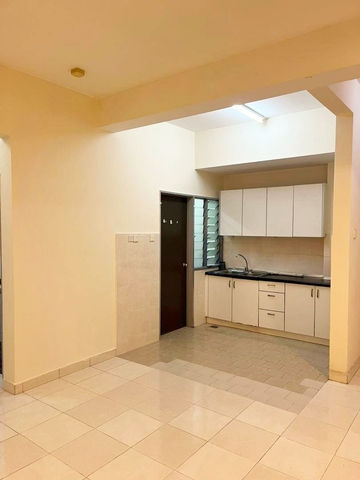
Lagoon Suites
Jalan Anggerik Malaxis 31/181
₫ 2,288,249,748
Listed on September 13, 2026
Green Avenue
Jalan 1/155B, Bukit OUG
₫ 2,987,437,171
Listed on August 13, 2025

GENTING PERMAI PARK & RESORT
GENTING PERMAI PARK & RESORT
₫ 1,906,874,790
Listed on April 12, 2025
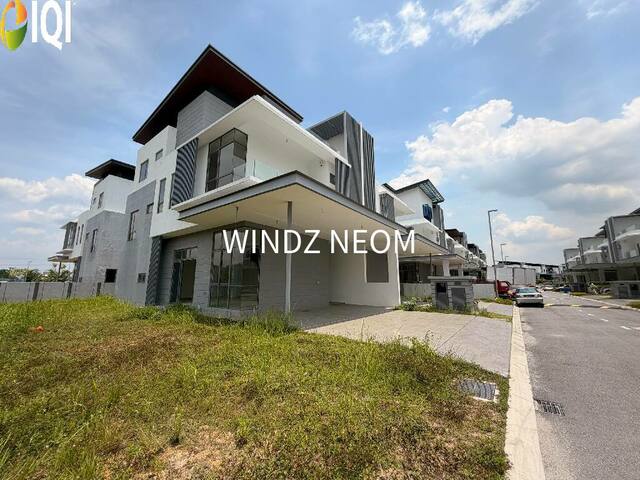
Broadleaf Residences
Jalan Anggerik Disa 31/184
₫ 15,445,685,799
Listed on April 28, 2026
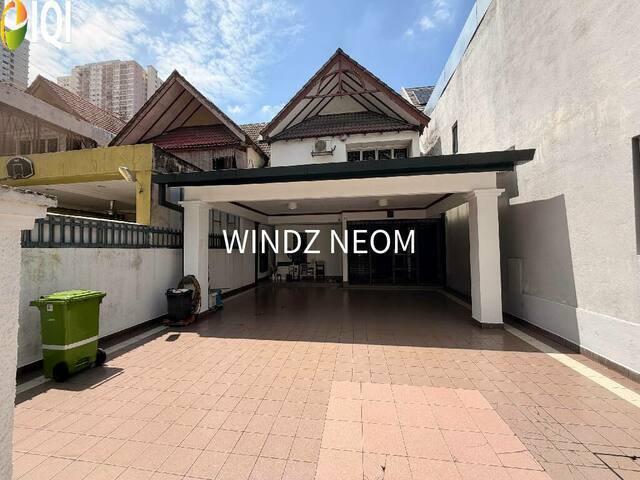
Bandar Menjalara (Desa Seri Mahkota)
Jalan 2/62C
₫ 7,373,249,188
Listed on March 25, 2026

The Andes @ Bukit Jalil
Off Mutiara Bukit Jalil
₫ 6,038,436,835
Listed on March 11, 2025
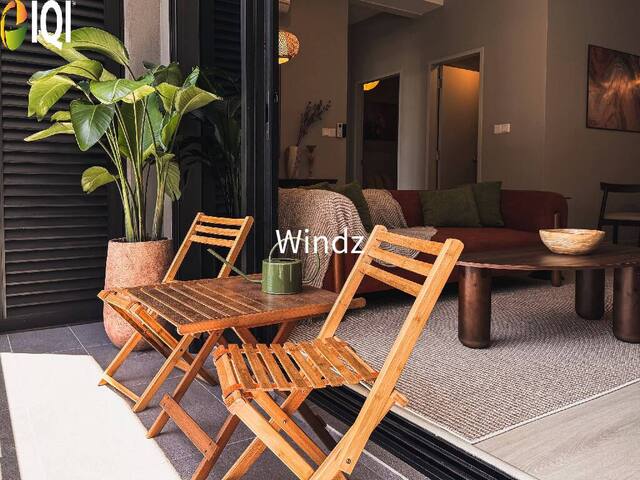
Nestree Residence @ Nestville
Pantai Sentral Park Bangsar South
₫ 50,849,994 /month
Listed on September 13, 2026
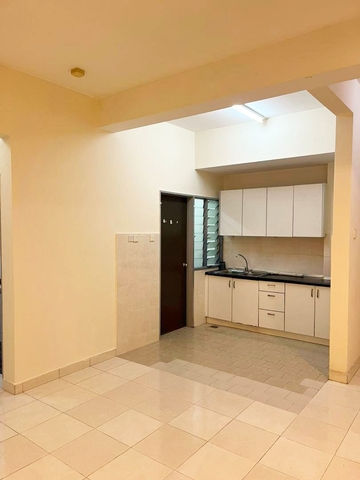
Lagoon Suites
Jalan Anggerik Malaxis 31/181
₫ 9,534,374 /month
Listed on September 13, 2026
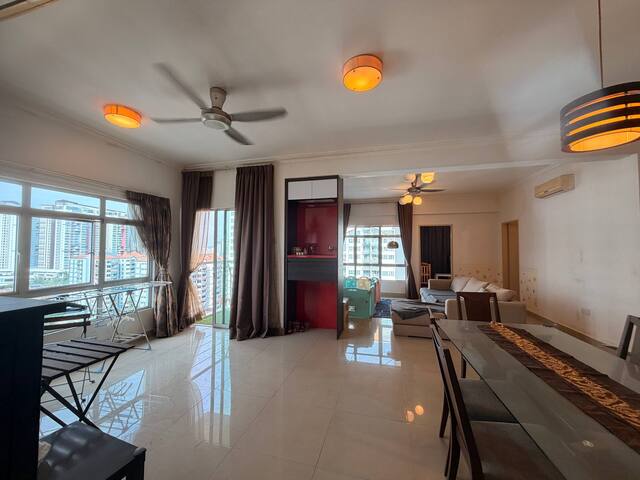
Residensi Desa
Jalan 1/127a, Kuchai Lama
₫ 3,432,374,622
Listed on July 15, 2026
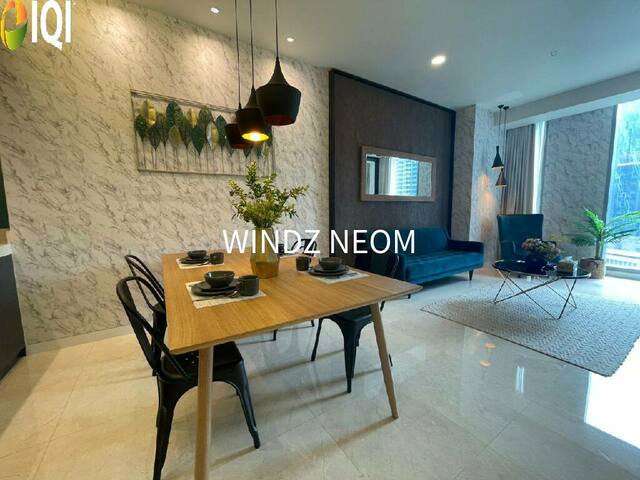
Tropicana The Residences
Jalan Ampang
₫ 8,898,749,020
Listed on January 23, 2026
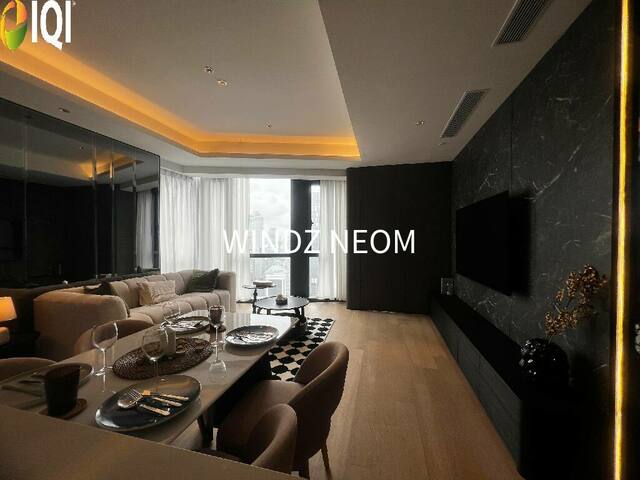
Star Residences
Jalan Yap Kwan Seng, Off Jalan Ampang
₫ 29,747,246,724
Listed on January 6, 2026
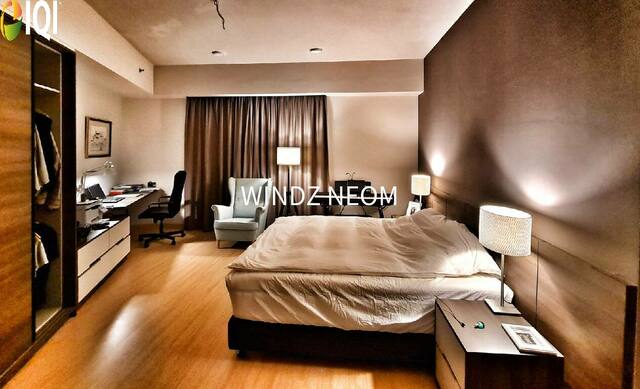
Windmill Upon Hills
Jalan Permai, Genting Permai Avenue
₫ 6,356,249,300
Listed on April 7, 2026

The Andes @ Bukit Jalil
Off Mutiara Bukit Jalil
₫ 8,771,624,034
Listed on March 11, 2025

BK5
Bandar Kinrara
₫ 5,180,343,180
Listed on September 11, 2026
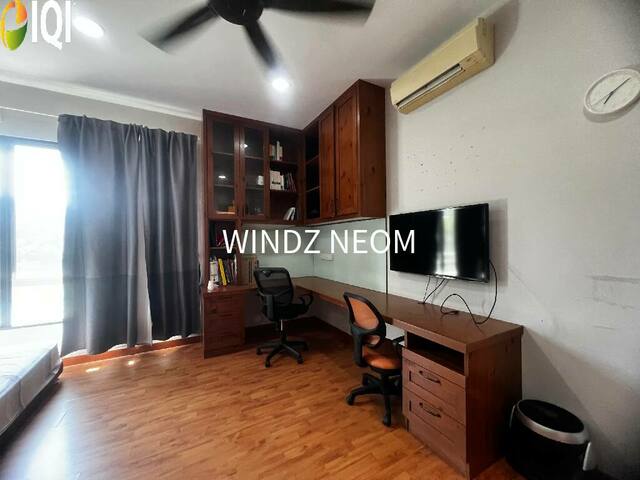
Kinrara Hills
Jalan Kinrara 6
₫ 19,068,747,900
Listed on January 2, 2026
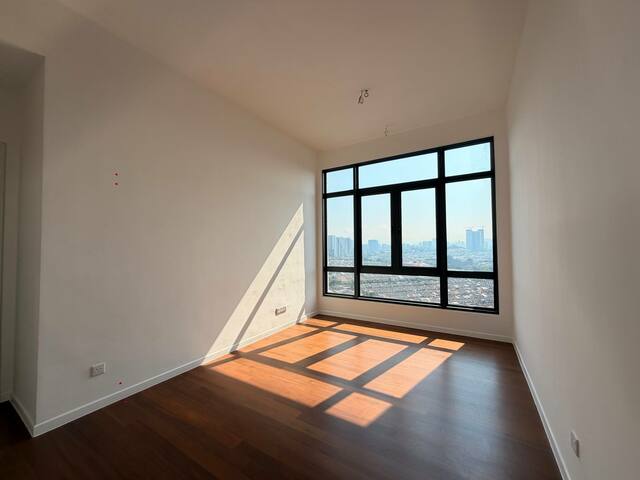
The Maple Residences OUG
Maple OUG
₫ 5,657,061,877
Listed on April 28, 2026
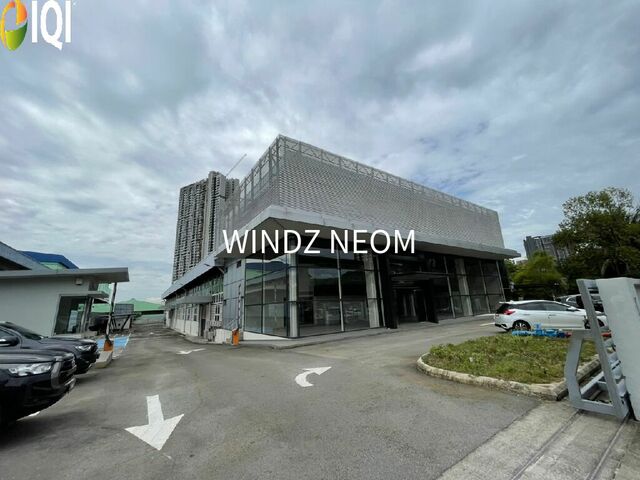
Kinrara Industrial Park
Section 1, Bandar Kinrara, 47180, Puchong
₫ 1,465,719,307 /month
Listed on May 6, 2026
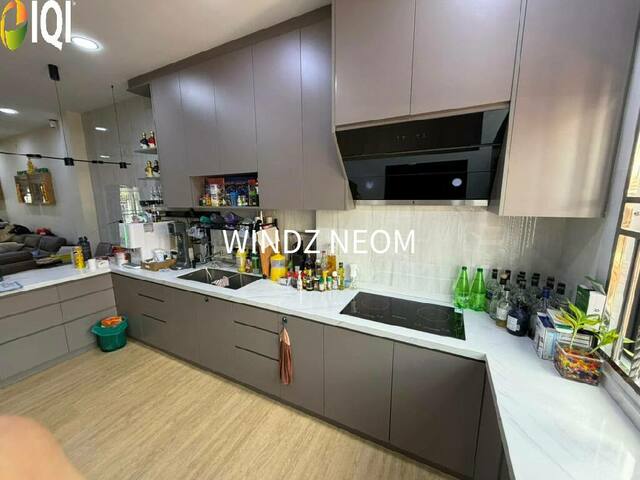
Happy Garden (Taman Gembira)
Jalan Riang, Jalan Selesa, Jalan Sukacita
₫ 11,568,373,726
Listed on May 20, 2026
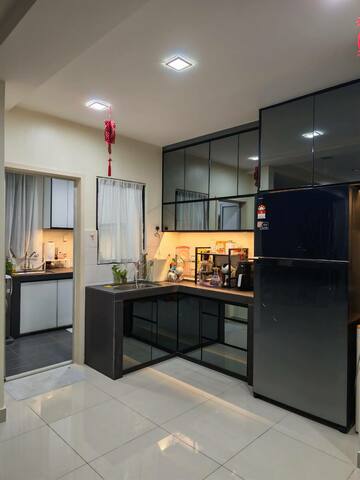
The Z Residence
Jalan 5/155, Taman Industri Bukit OUG, Bukit Jalil
₫ 4,576,499,496
Listed on July 2, 2026
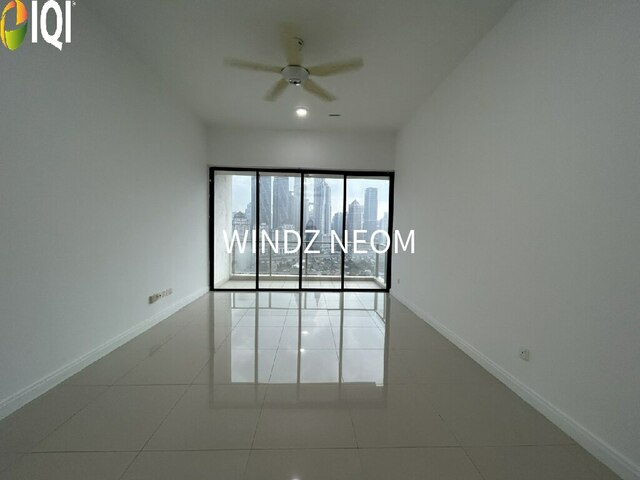
Setia Sky Residences
Jalan Tun Razak
₫ 7,945,311,625
Listed on January 23, 2026

Puchong Financial Corporate Center (PFCC)
Jalan Puteri 1/2
₫ 59,577,125 /month
Listed on July 3, 2026
Aria Luxury Residence
Jalan Tun Razak, Kuala Lumpur
₫ 7,627,499,160
Listed on March 18, 2026
The Maple Residences OUG
taman oug
₫ 5,084,999,440
Listed on April 17, 2026
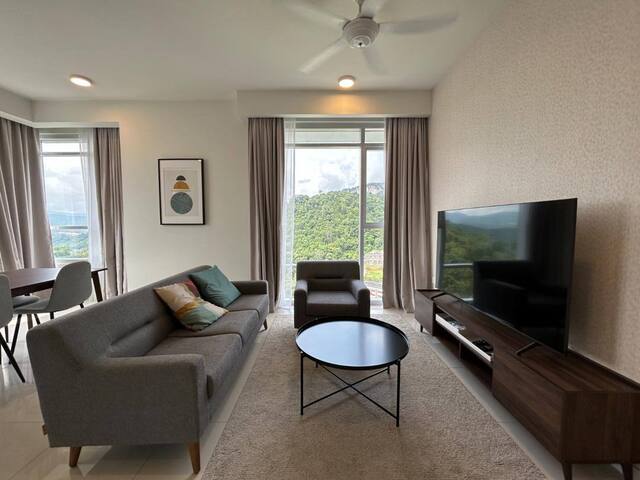
The Ridge @ KL East (Residensi Rabung KL Timur)
PERSIARAN MELATI KUARZA
₫ 20,339,998 /month
Listed on July 27, 2026
Aria Luxury Residence
Jalan Tun Razak, Kuala Lumpur
₫ 44,493,745 /month
Listed on September 18, 2025
Aria Luxury Residence
Jalan Tun Razak, Kuala Lumpur
₫ 20,975,622,690
Listed on July 23, 2026
Setia Sky Residences
Jalan Tun Razak
₫ 5,593,499,384
Listed on April 7, 2026
Fortune Court
Block 288, Jalan Thean Teik
₫ 2,536,143,471
Listed on January 5, 2026

Scarletz Suites
Jalan Yap Kwan Seng, 50450, Kuala Lumpur
₫ 5,593,499,384
Listed on April 12, 2025

SkyVogue Residences
Taman Desa
₫ 4,767,186,975
Listed on June 4, 2026
Acacia Park @ Bandar Tasik Puteri
Jalan Puteri
₫ 3,241,687,143
Listed on April 17, 2026

Edelweiss @ Tropicana Gardens
Jln PJU 3/21
₫ 13,983,748 /month
Listed on July 23, 2026
The Ridge @ KL East (Residensi Rabung KL Timur)
PERSIARAN MELATI KUARZA
₫ 15,890,623 /month
Listed on July 23, 2026
Menara Bangkok Bank | Berjaya Central Park
Jalan Ampang
₫ 127,124,986 /month
Listed on August 11, 2026

The Tropika Bukit Jalil
Jalan Jalil Perkasa 7
₫ 8,263,124,090
Listed on July 1, 2026

GENTING PERMAI PARK & RESORT
C-3-7, -, GENTING PERMAI PARK & RESORT
₫ 10,169,999 /month
Listed on August 5, 2026

Mawar Apartment
Taman Gohtong Jaya, Genting Highlands
₫ 2,033,999,776
Listed on August 5, 2026
Mutiara Oriental Condominium
Jalan Bukit Mayang 1/8, Taman Bukit Mayang Emas
₫ 4,245,974,532
Listed on June 8, 2026
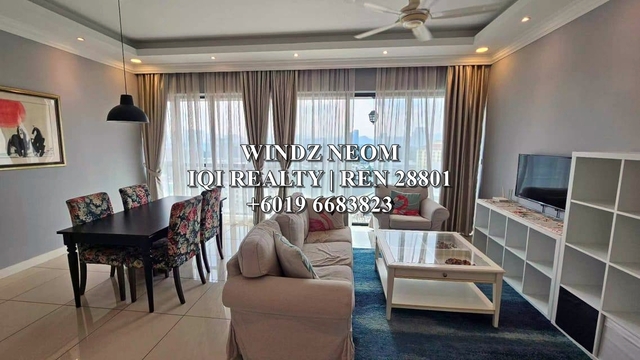
Setia Sky Residences
Jalan Tun Razak
₫ 6,356,249,300
Listed on April 7, 2026
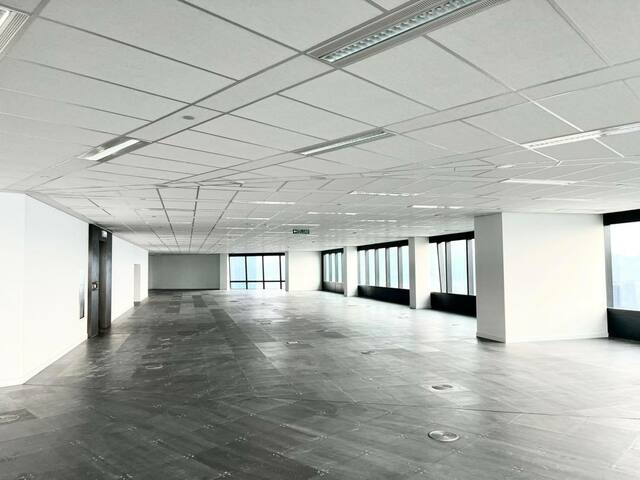
Merdeka 118 @ Warisan Merdeka 118
MERDEKA 118
₫ 1,201,331,118 /month
Listed on July 3, 2026

The Andes @ Bukit Jalil
Off Mutiara Bukit Jalil
₫ 8,898,749,020
Listed on March 11, 2025
Our newly launched projects
Discover the real estate properties in and around Kuala Lumpur, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Large land area
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from ₫ 92,137,138,853
Listed on January 23, 2026
 Located in Bukit Minyak
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₫ 7,651,652,907
Listed on January 23, 2026
 Located in Simpang Ampat
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from ₫ 31,876,590,240
Listed on January 23, 2026
 Located in Bukit Mertajam
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₫ 7,111,371,717
Listed on January 23, 2026
 Located in Bukit Mertajam
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from ₫ 5,199,411,927
Listed on January 23, 2026
 Large land area
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from ₫ 3,495,937,115
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
Hanoi Apartment Market Faces Resale Pressure Hanoi’s apartment market is entering a more cautious phase as resale pressure increases among investors who bought off-plan or during construction with short-term flipping strategies. After several years of strong price growth, market conditions have cooled. Capital gains are no longer guaranteed, while the end of mortgage grace periods is exposing some investors to higher floating interest rates and heavier repayment obligations. This is encouraging more owners to sell, with liquidity and debt reduction becoming a greater priority than maximising returns. According to market data cited in the report, asking prices at several Hanoi projects have already corrected from their previous peaks. Imperia Sola Park fell around 12.6%, Lumi Hanoi declined approximately 9.5%, while Kepler Land recorded an 8.6% correction. Market Shifts From Speculation to Liquidity The change marks an important shift in Vietnam’s residential market. Some leveraged investors are no longer holding properties in expectation of further short-term appreciation. Instead, they are looking to exit quickly, reduce debt exposure and, in some cases, accept losses. For genuine homebuyers and investors with stronger cash positions, this may create improved negotiating conditions in Hanoi’s secondary apartment market. Rather than competing in a rapidly rising market, buyers may now have greater scope to negotiate on properties where sellers are under financing pressure. Outlook Hanoi’s apartment market is likely to remain more selective and liquidity-driven in the near term. Resale pressure could continue to create opportunities for buyers who have sufficient cash and are willing to negotiate carefully. The key advantage is shifting towards financially prepared buyers, particularly those able to identify motivated sellers and acquire quality secondary-market units at prices below previous market peaks. The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
30 Jul, 2026
Vietnam Property Market Outlook 2026: Infrastructure Corridors Lead the Next Growth Cycle
Vietnam’s Housing Market Enters a Selective Reset Vietnam’s residential market entered August 2026 in a period of consolidation. Prices remain relatively firm, but transaction activity is slower as buyers become more selective and borrowing costs stay elevated. During Q2 2026, developers launched approximately 12,000 primary condominiums across the enlarged Ho Chi Minh City market and more than 4,000 units in Hanoi. However, luxury absorption remained below 30% in Ho Chi Minh City, while Hanoi’s take-up rate eased to around 20%. Inner-city primary prices reached approximately USD 5,400 to USD 9,500 per square metre. Pressure was more visible in the secondary market, where prices declined 5% to 8% in Ho Chi Minh City and by as much as 12% in parts of Hanoi. Floating mortgage rates of 13% to 16% are encouraging some owners to lower asking prices. However, the market has not experienced widespread distress, while the new land-price framework is helping maintain a floor under development costs and headline prices. Infrastructure Redirects Property Demand Vietnam has approximately 234 major infrastructure projects worth VND 3.4 quadrillion underway. These investments are shifting demand from crowded central districts towards better-connected suburban and regional corridors. In the south, growth is concentrating around the Ho Chi Minh City and Dong Nai corridor, supported by Long Thanh International Airport, new ring roads, expressways and Metro Line 1. Northern demand is moving towards Hanoi’s gateway districts and neighbouring Hung Yen and Bac Ninh. Da Nang is also showing stronger primary-market activity, supported by limited prime coastal supply. Outlook Vietnam’s next property cycle is expected to favour patience and careful asset selection rather than short-term speculation. With average gross rental yields near 3.85%, investment returns will depend increasingly on infrastructure-led capital appreciation. Legally clear projects with strong connectivity and genuine end-user demand should remain best positioned, particularly for buyers with sufficient holding power and a multi-year investment horizon. Download to see insights from other country marketsDownload
Vietnam Residential Market Enters a More Selective Cycle Vietnam’s residential market opened 2026 in a transition phase, with prices still rising but liquidity cooling. This suggests the market is moving away from easy speculative gains toward a more disciplined cycle. Residential prices rose around 12% year-on-year in Q1 2026, while liquidity fell nearly 40%. However, there was no sign of distress selling, pointing to a healthy reset rather than a sharp downturn. Primary condominium prices reached new highs across major cities. In Hanoi, average prices were around USD 3,950 per sqm, up 30% year-on-year. In post-merger Ho Chi Minh City, prices averaged around USD 3,900 per sqm, supported by new supply and limited premium stock. Supply also improved. Ho Chi Minh City recorded around 8,010 new condo launches, up 104% year-on-year. Yet affordability remains the key challenge, with much of the new supply priced above the level affordable to mass-market buyers. Strong Fundamentals, But Investors Are More Careful Vietnam’s underlying fundamentals remain supportive. The economy grew 8.02% in 2025, while real estate FDI reached USD 389.5 million in Q1 2026, representing around 7.2% of total inflows. However, investor behaviour is changing. Demand is now concentrating on projects with clear legal status, reliable construction progress and long-term value. Satellite locations such as Binh Duong and Ba Ria-Vung Tau are gaining attention as central city prices continue to stretch. Outlook Vietnam’s property market is expected to remain attractive, but more selective. With average gross rental yields at around 3.85%, the market is less of a pure income play and more of a capital appreciation and infrastructure-led growth story. Buyers with strong holding power, careful project selection and a long-term view are likely to be better positioned than short-term speculators. Download to see insights from other country marketsDownload
Vietnam's property market continues to present a mixed but encouraging picture in 2026. While Hanoi's retail property sector is undergoing a period of adjustment, Ho Chi Minh City's residential market remains resilient, supported by limited supply, strong demand, and improving infrastructure connectivity. The contrasting performance between the two cities highlights the importance of market selection as investors navigate Vietnam's evolving real estate landscape. Hanoi's Retail Market Faces Adjustment Hanoi's prime retail corridors continue experiencing pressure as changing consumer behaviour and the growth of e-commerce reshape demand for traditional street-front retail space. Vacancy levels have become more noticeable in several key commercial areas as landlords and tenants adjust to shifting market conditions. The correction has also impacted retail-linked residential assets, with demand softening compared to previous years. Rental rates for townhouses across several submarkets have declined from their recent peaks, reflecting a more cautious operating environment for retailers and property owners. Despite these short-term challenges, Hanoi remains an important commercial centre, and the current adjustment may create opportunities for well-capitalised investors focused on long-term value. Ho Chi Minh City Continues to Lead Residential Growth In contrast, Ho Chi Minh City's residential market remains one of Vietnam's strongest-performing sectors. Limited new supply, improving infrastructure, and sustained buyer demand continue supporting price growth across the city. Average apartment prices in central Ho Chi Minh City reached new highs during the first quarter of 2026, driven largely by high-end and luxury developments. The shortage of mid-market housing options has also contributed to upward pressure on prices. Growth is not limited to the city centre. Formerly independent areas such as Binh Duong and Ba Ria-Vung Tau continue benefiting from expanding infrastructure and stronger regional connectivity, supporting residential demand and investment activity throughout the wider metropolitan area. Infrastructure Continues to Support Long-Term Demand One of the strongest themes across Vietnam's property market remains infrastructure-led growth. Continued investment in transportation networks and urban expansion projects is improving accessibility between major economic centres and surrounding residential markets. As connectivity improves, suburban and emerging growth areas are becoming increasingly attractive to both homebuyers and investors seeking more affordable entry points and long-term appreciation potential. Outlook Vietnam's property market is expected to remain supported by urbanisation, infrastructure investment, and long-term housing demand. While Hanoi's retail sector may continue adjusting to changing consumer trends, Ho Chi Minh City's residential market is likely to remain resilient due to limited supply and strong buyer interest. For investors, opportunities increasingly lie in understanding the differing dynamics between cities and focusing on markets supported by strong economic and infrastructure fundamentals. Download to see insights from other country marketsDownload
Ready to get started?
Get in touch now.