Team Leader (Subsales) ∙ Elite
Lim Li Li
REN17713
Về Lim Li Li
Who Am I Lim Li Li (REN 17713) — Team Leader (Subsales) at IQI Realty Sdn Bhd, collaborating with CIL Group.A seasoned Real Estate Negotiator with 10+ years of experience in Kota Kinabalu, Sabah. Who I Help Property Buyers & Tenants: Individuals and families looking for residential homes or rental p... Who Am I Lim Li Li (REN 17713) — Team Leader (Subsales) at IQI Realty Sdn Bhd, collaborating with CIL Group.A seasoned Real Estate Negotiator with 10+ years of experience in Kota Kinabalu, Sabah. Who I Help Property Buyers & Tenants: Individuals and families looking for residential homes or rental properties.Property Owners & Sellers: Homeowners wanting to list, market, and sell properties at top market value.Investors & Developers: Local and international investors looking for commercial, industrial, or strategic land development opportunities. How I Help End-to-End Deal Execution: Handling full-suite sales, leasing, and negotiation for residential, commercial, industrial, and land properties.Strategic Land Matching: Connecting land parcels with investors and developers to unlock property appreciation and development value.Client-First Advisory: Providing market insights built on trust, integrity, and quality service. Why Follow Me Local Market Expertise: Access exclusive property insights, price trends, and high-ROI opportunities in Sabah.Proven Track Record: Guidance from a top-tier team leader with over a decade of real estate success.First-Hand Listings: Stay updated on current subsales, hot deals, and investment prospects before they hit the open market. Call or WhatsApp +6012 •••• ••38 to discuss your current property search, listing, or investment strategy.
6 năm tại IQI
256 giao dịch
16 bất động sản để bán
15 bất động sản cho thuê
Địa điểm Dịch vụ của Lim Li Li
Địa điểm Dịch vụ của Lim Li Li
Danh sách của tôi

1B/1Borneo/One Borneo
88400
₫ 2,515,626,779
Được liệt kê vào tháng 10 17, 2021

Jesselton Residences
Pusat Bandar Kota Kinabalu, 88000, Sabah
₫ 17,697,877 /tháng
Được liệt kê vào tháng 1 3, 2025
1 SULAMAN
A-11-09, 11 FLOOR TOWER A, 1 SULAMAN PLATINUM TOWER
₫ 12,641,341 /tháng
Được liệt kê vào tháng 12 3, 2025
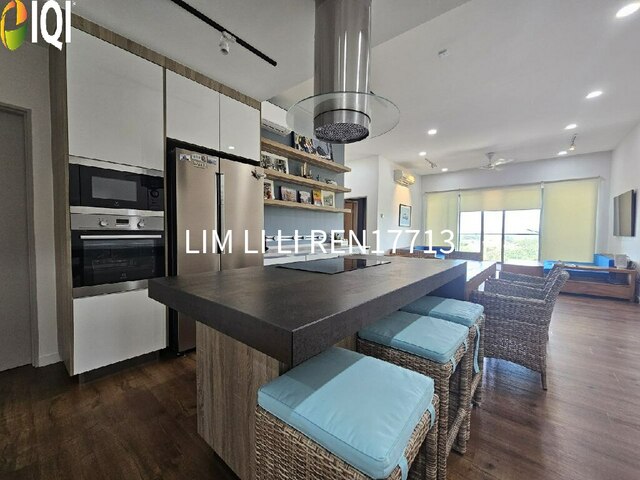
The Loft @ KK Times Square
KK Times Square, Kota Kinabalu
₫ 34,763,687 /tháng
Được liệt kê vào tháng 3 8, 2026
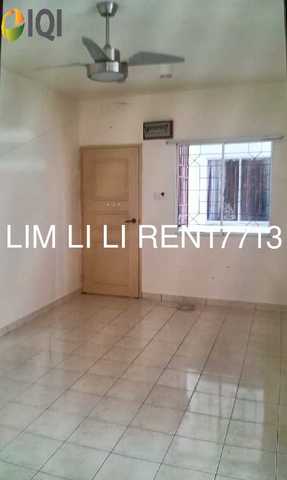
COUNTRY HEIGHT APARTMENT PH II
BLOK 2M TINGKAT 1 NO 7,JALAN BANTAYAN, COUNTRY HEIGHT APARTMENT PH II
₫ 1,769,787,684
Được liệt kê vào tháng 3 26, 2024
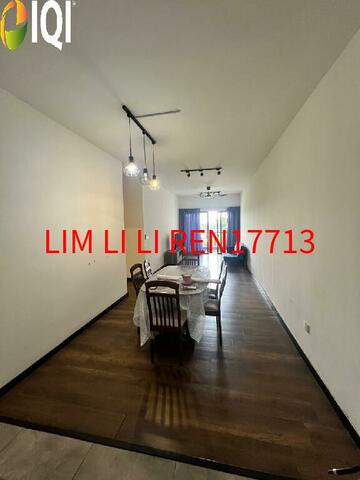
MAYA @ LIKAS KONDOMINIUM
UNIT NO B08-, KONDOMINIUM MAYA,LIKAS, MAYA @ LIKAS KONDOMINIUM
₫ 3,918,815,586
Được liệt kê vào tháng 5 27, 2026
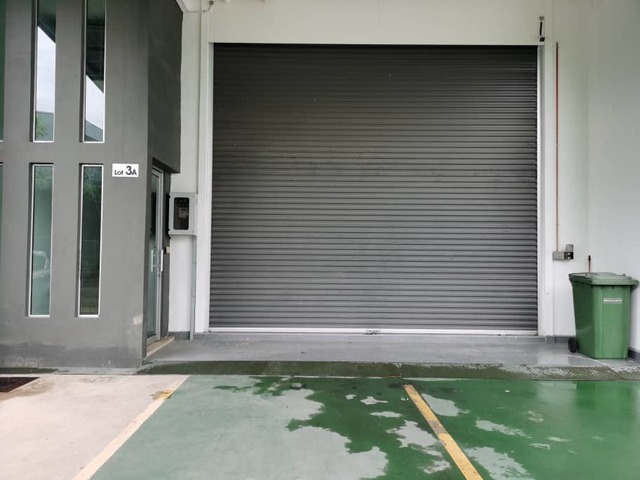
Kota Kinabalu Industrial Park - BUNDUSAN INDUSTRIAL PARK
jln penampang lama
₫ 10,745,139,510
Được liệt kê vào tháng 6 16, 2023
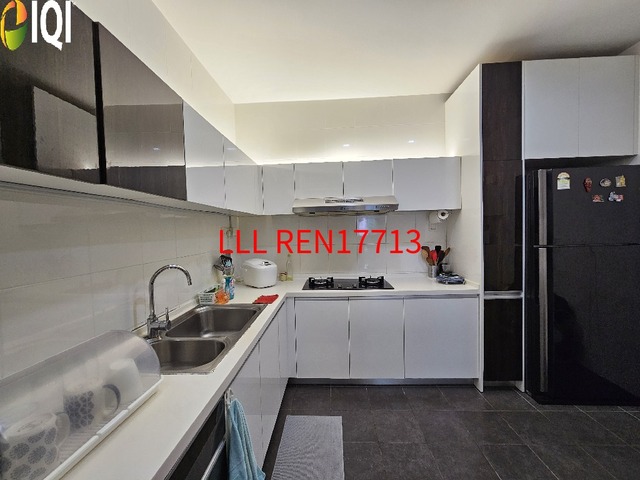
Tropicana Landmark
Jalan Bundusan
₫ 4,550,882,616
Được liệt kê vào tháng 12 10, 2025
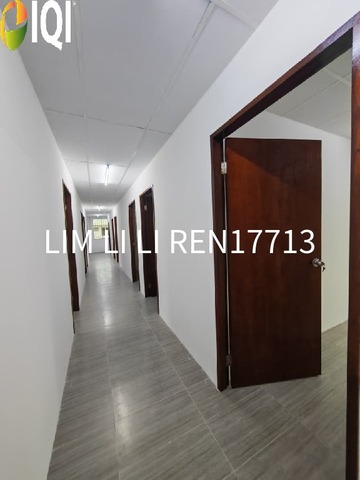
Kian Yap Kota Kinabalu
Lorong Perindustrian, 88450 Kota Kinabalu, Sabah
₫ 4,740,503 /tháng
Được liệt kê vào tháng 3 8, 2026
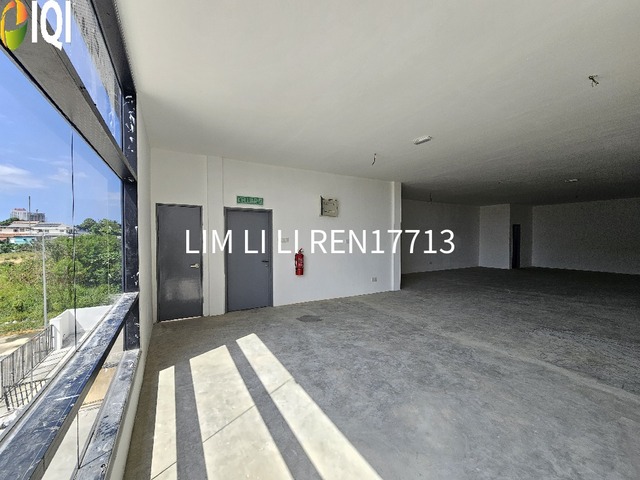
PLAZA INOVASI INDUSTRI
LOT 7 JLN PENAMPANG,PLAZA INOVASI INDUSTRI
₫ 47,405,027 /tháng
Được liệt kê vào tháng 2 21, 2026
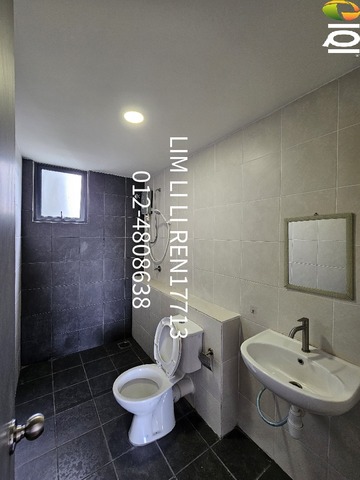
The Gardens Condominium
Lorong Taman Formosa 2, Taman Farmosa
₫ 3,792,402,180
Được liệt kê vào tháng 7 15, 2025

The Peak Vista
Jalan Signal Hill, Likas
₫ 10,618,726,104
Được liệt kê vào tháng 3 6, 2023
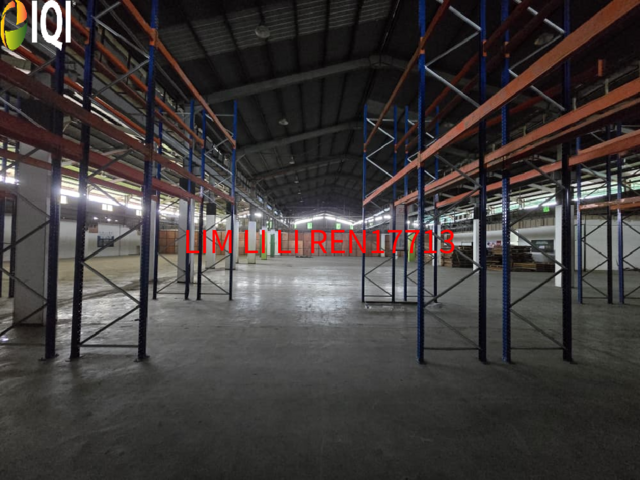
Kolombong/Bdc Industrial Estate
Jalan Kolombong, Kolombong/Bdc Industrial Estate, 88450 Kota Kinabalu, Sabah
₫ 505,653,624 /tháng
Được liệt kê vào tháng 9 9, 2026
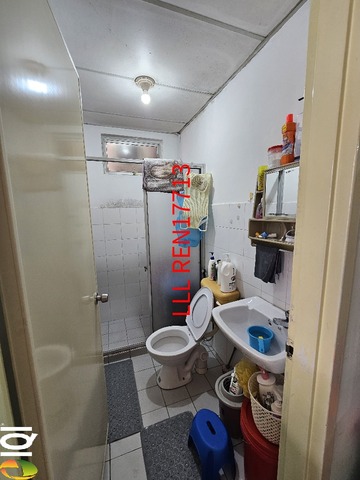
Beverly Hills 5
Beverly Hills Apartment, Kota Kinabalu, Sabah
₫ 2,275,441,308
Được liệt kê vào tháng 12 24, 2025

JESSELTON QUAY
JESSELTON QUAY
₫ 10,113,072 /tháng
Được liệt kê vào tháng 11 8, 2022
KAMPUNG TOMBORO
KAMPUNG TOMBORO
₫ 22,953,387,781
Được liệt kê vào tháng 1 3, 2026
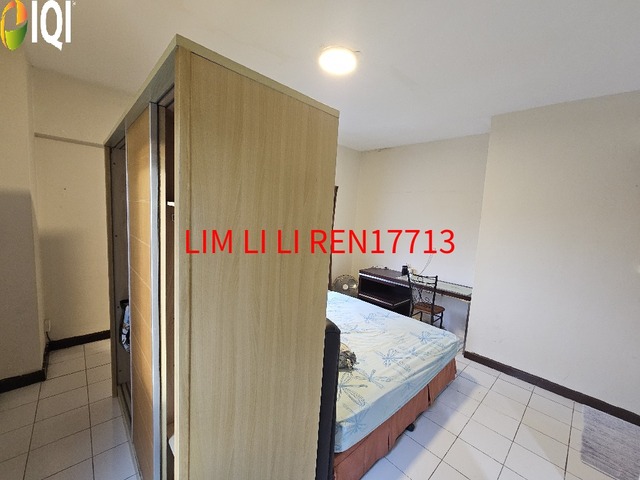
Likas Square
Lorong Likas Square, Jalan Istiadat, Kota Kinabalu
₫ 9,481,005 /tháng
Được liệt kê vào tháng 4 5, 2026

University Prime Condominium
Kota Kinabalu, 88400, Sabah
₫ 1,580,167,575
Được liệt kê vào tháng 10 31, 2024
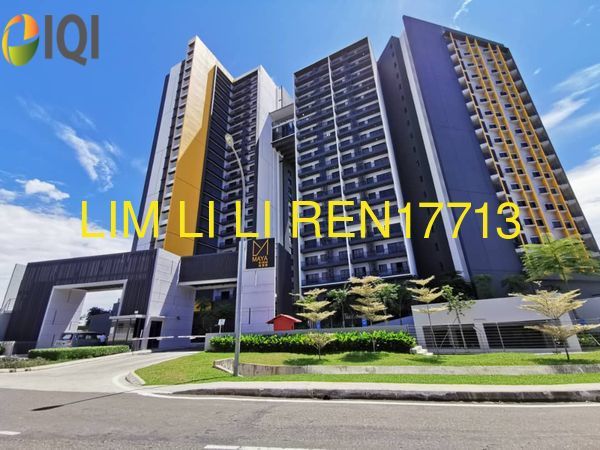
MAYA CONDO
MAYA CONDO
₫ 3,918,815,586
Được liệt kê vào tháng 12 29, 2021
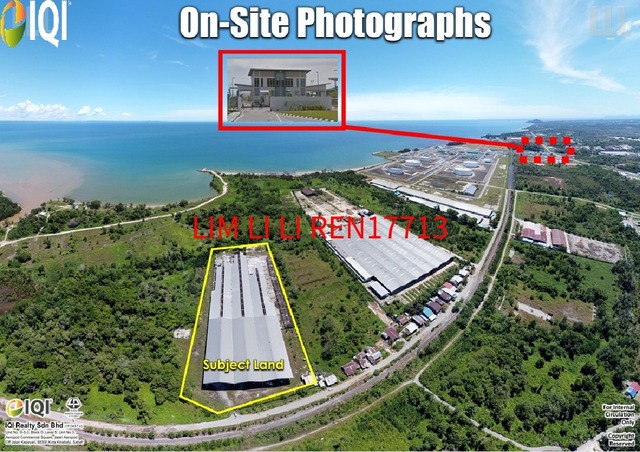
pekan lama kimanis
Pekan Lama Kimanis
₫ 189,620,109 /tháng
Được liệt kê vào tháng 4 13, 2026

PEAK SUITE
PEAK SUITE , 88300 KOTA KINABALU
₫ 3,779,760,839
Được liệt kê vào tháng 8 24, 2020
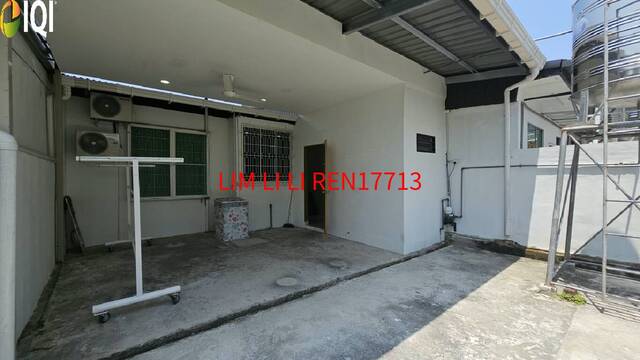
Taman Sentosa
Taman Sentosa
₫ 18,962,011 /tháng
Được liệt kê vào tháng 9 9, 2026
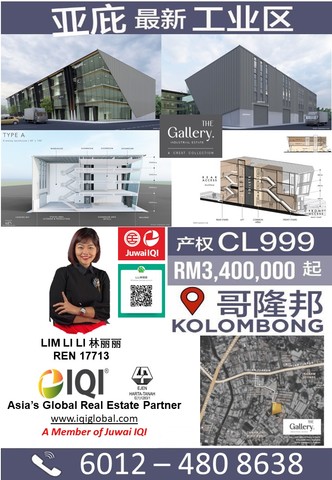
THE GALLERY
KOLOMBONG
₫ 32,425,038,639
Được liệt kê vào tháng 10 8, 2022
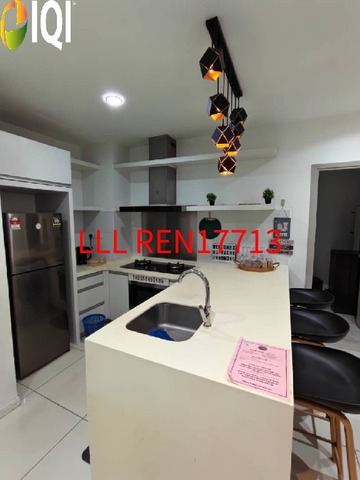
Sutera Avenue
Sutera Avenue, 88100 Kota Kinabalu, Sabah
₫ 17,065,810 /tháng
Được liệt kê vào tháng 12 25, 2025

BAY 21 LIKAS
Jalan Teluk Likas, 88400 Kota Kinabalu Sabah
₫ 5,688,603,270
Được liệt kê vào tháng 12 23, 2024
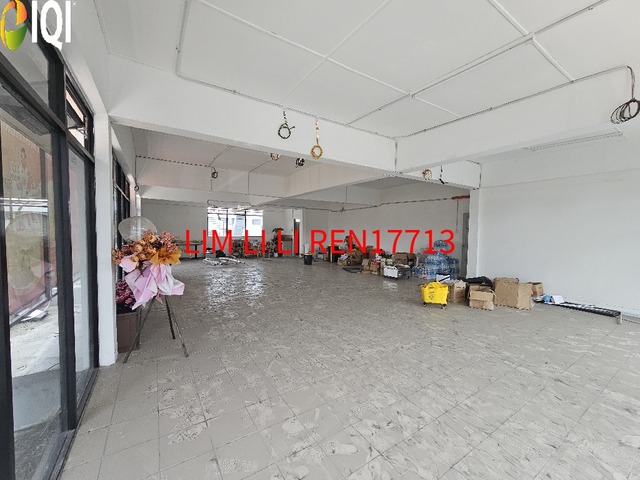
PLAZA KOLOMBONG
PLAZA KOLOMBONG
₫ 15,801,676 /tháng
Được liệt kê vào tháng 9 9, 2026
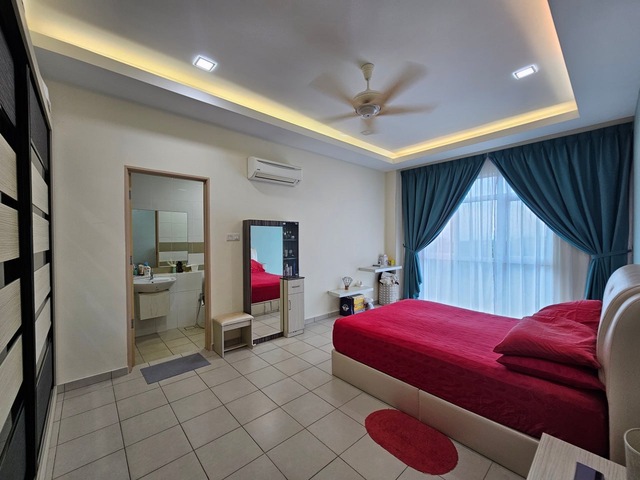
TAMAN KONDOMINIUM BUNDUSAN (TROPICANA LANDMARK)
UNIT NO 17-11, LORONG GOLF GARDEN, OFF JALAN BUNDUSAN, TAMAN KONDOMINIUM BUNDUSAN (TROPICANA LANDMAR
₫ 4,550,882,616 /tháng
Được liệt kê vào tháng 5 16, 2025
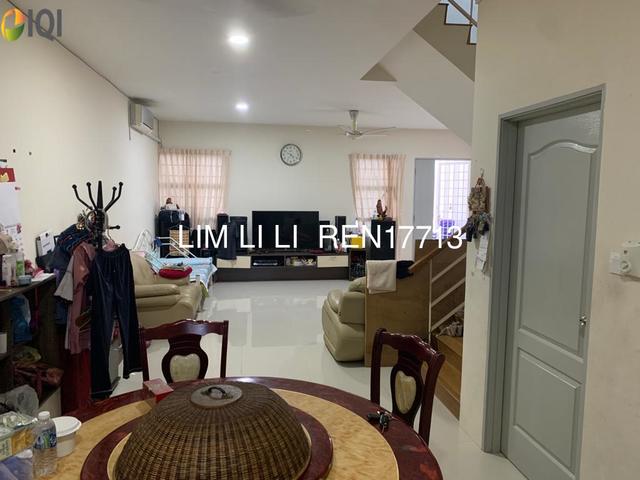
TMN PUTRA POGUN
TMN PUTRA POGUN
₫ 4,980,688,196
Được liệt kê vào tháng 2 28, 2023
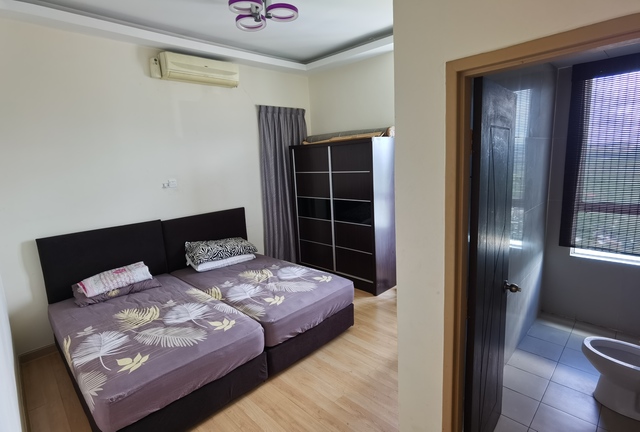
ONE BORNEO CONDO
ONE BORNEO CONDO
₫ 12,641,341 /tháng
Được liệt kê vào tháng 11 20, 2022
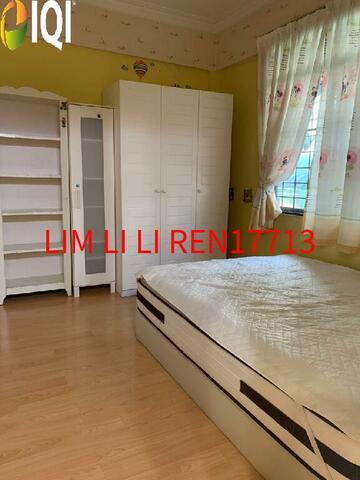
Indah Court
Taman Jaya, Likas, Kota Kinabalu
₫ 3,097,128,447
Được liệt kê vào tháng 4 6, 2026
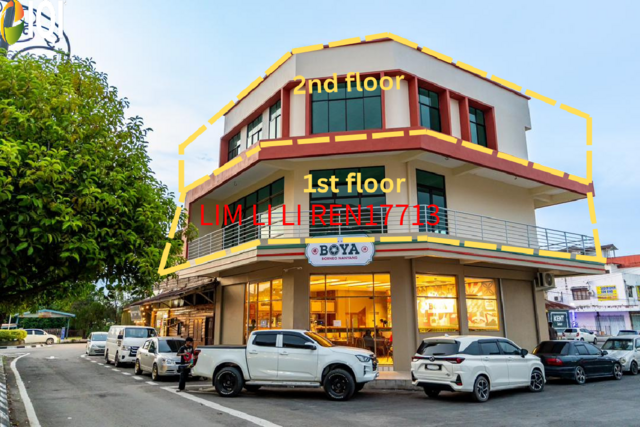
Jalan Keough, Tuaran
Shop Office, Jalan Keough, 89208 Tuaran, Sabah
₫ 6,320,670 /tháng
Được liệt kê vào tháng 7 12, 2026
Các dự án mới ra mắt của chúng tôi
Khám phá các bất động sản trong và xung quanh Kota Kinabalu, Malaysia. Mua căn hộ, nhà phố, biệt thự, văn phòng thương mại, cửa hàng và bán lại với 100% tự tin tại IQI Global.
 Diện tích đất lớn
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Bắt đầu từ ₫ 91,621,402,747
Được liệt kê vào tháng 1 23, 2026
 Nằm ở Bukit Minyak
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Bắt đầu từ ₫ 7,608,822,907
Được liệt kê vào tháng 1 23, 2026
 Nằm ở Simpang Ampat
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Bắt đầu từ ₫ 31,698,161,555
Được liệt kê vào tháng 1 23, 2026
 Nằm ở Bukit Mertajam
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Bắt đầu từ ₫ 7,071,565,932
Được liệt kê vào tháng 1 23, 2026
 Diện tích xây dựng lớn hơn
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Bắt đầu từ ₫ 5,170,308,305
Được liệt kê vào tháng 1 23, 2026
 Diện tích đất lớn
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Bắt đầu từ ₫ 3,476,368,665
Được liệt kê vào tháng 1 23, 2026
Máy tính thế chấp
Tính toán khoản thanh toán hàng tháng ước tính của bạn và lập kế hoạch chi tiêu hàng tháng một cách tốt.
Máy tính thế chấp chỉ mang tính tham khảo. Số tiền thực tế có thể khác.
Thanh toán hàng tháng
Gửi kết quả máy tính thế chấp cho tôi
Máy tính đủ điều kiện vay mua nhà
Tính toán số tiền vay tiềm năng của bạn và đánh giá khả năng mua nhà của bạn.
Lợi nhuận cho thuê
Tính toán lợi nhuận cho thuê tiềm năng và đánh giá hiệu suất đầu tư của bất động sản.
Kế hoạch tiết kiệm trả trước
Tạo kế hoạch tiết kiệm có cấu trúc và xác định số tiền cần tiết kiệm hàng tháng cho kế hoạch trả trước của bạn.
Máy tính phí giao dịch bất động sản Malaysia
Ước tính tổng phí giao dịch cho việc mua bất động sản Malaysia.
Blog & tin tức IQI
Các bài viết được tuyển chọn đặc biệt cho bản tóm tắt hàng ngày về tin tức bất động sản địa phương và toàn cầu của bạn.
5 Th10, 2026
Vietnam Property Market October 2026: Policy Reform Reshapes a Resilient but Selective Market
Policy Reform Takes Centre Stage Vietnam’s residential market is entering the final quarter of 2026 with policy, rather than pricing, driving the conversation. Resolution 21-NQ/TW is set to shape the next round of Land Law and housing amendments, including proposals linking apartment use to a building’s service life and placing greater reconstruction obligations on owners. The changes could also introduce heavier taxation on excess property profits and vacant or unused assets, while land allocation may increasingly favour commercial apartment supply. MBS Research expects some new apartment projects could shift toward 50–99-year tenures, although implementing rules have not yet been issued. Despite the uncertainty, activity remains substantial. Nearly 34,000 new homes were launched nationwide in Q2, with around 19,600 units sold, equivalent to an absorption rate of approximately 58%. Average primary apartment prices reached around VND 80 million per sqm, up 10% from 2025. Strong Economy Meets Financing Pressure Hanoi illustrates the market’s growing divide. Q2 sales fell 45% year-on-year, even as luxury-led launches pushed primary prices up 36% to about US$4,659 per sqm. Mortgage rates of 12–14% remain the biggest obstacle for first-time buyers. At the same time, Vietnam’s macroeconomic backdrop remains strong. GDP grew 8.39% year-on-year in Q2, while registered FDI reached US$40.63 billion in the first eight months, up 55.4%. Of this, US$5.32 billion was committed to real estate. Outlook Vietnam is likely to remain a selective, end-user-led market rather than enter a broad rally. High financing costs and new legal considerations will make cash strength, legal clarity and land-backed assets increasingly important. For buyers and investors, due diligence around ownership structure, land-use rights and project legality will matter as much as location and product quality. Vietnam, October 2026 The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
Hanoi Apartment Market Faces Resale Pressure Hanoi’s apartment market is entering a more cautious phase as resale pressure increases among investors who bought off-plan or during construction with short-term flipping strategies. After several years of strong price growth, market conditions have cooled. Capital gains are no longer guaranteed, while the end of mortgage grace periods is exposing some investors to higher floating interest rates and heavier repayment obligations. This is encouraging more owners to sell, with liquidity and debt reduction becoming a greater priority than maximising returns. According to market data cited in the report, asking prices at several Hanoi projects have already corrected from their previous peaks. Imperia Sola Park fell around 12.6%, Lumi Hanoi declined approximately 9.5%, while Kepler Land recorded an 8.6% correction. Market Shifts From Speculation to Liquidity The change marks an important shift in Vietnam’s residential market. Some leveraged investors are no longer holding properties in expectation of further short-term appreciation. Instead, they are looking to exit quickly, reduce debt exposure and, in some cases, accept losses. For genuine homebuyers and investors with stronger cash positions, this may create improved negotiating conditions in Hanoi’s secondary apartment market. Rather than competing in a rapidly rising market, buyers may now have greater scope to negotiate on properties where sellers are under financing pressure. Outlook Hanoi’s apartment market is likely to remain more selective and liquidity-driven in the near term. Resale pressure could continue to create opportunities for buyers who have sufficient cash and are willing to negotiate carefully. The key advantage is shifting towards financially prepared buyers, particularly those able to identify motivated sellers and acquire quality secondary-market units at prices below previous market peaks. The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
30 Th07, 2026
Vietnam Property Market Outlook 2026: Infrastructure Corridors Lead the Next Growth Cycle
Vietnam’s Housing Market Enters a Selective Reset Vietnam’s residential market entered August 2026 in a period of consolidation. Prices remain relatively firm, but transaction activity is slower as buyers become more selective and borrowing costs stay elevated. During Q2 2026, developers launched approximately 12,000 primary condominiums across the enlarged Ho Chi Minh City market and more than 4,000 units in Hanoi. However, luxury absorption remained below 30% in Ho Chi Minh City, while Hanoi’s take-up rate eased to around 20%. Inner-city primary prices reached approximately USD 5,400 to USD 9,500 per square metre. Pressure was more visible in the secondary market, where prices declined 5% to 8% in Ho Chi Minh City and by as much as 12% in parts of Hanoi. Floating mortgage rates of 13% to 16% are encouraging some owners to lower asking prices. However, the market has not experienced widespread distress, while the new land-price framework is helping maintain a floor under development costs and headline prices. Infrastructure Redirects Property Demand Vietnam has approximately 234 major infrastructure projects worth VND 3.4 quadrillion underway. These investments are shifting demand from crowded central districts towards better-connected suburban and regional corridors. In the south, growth is concentrating around the Ho Chi Minh City and Dong Nai corridor, supported by Long Thanh International Airport, new ring roads, expressways and Metro Line 1. Northern demand is moving towards Hanoi’s gateway districts and neighbouring Hung Yen and Bac Ninh. Da Nang is also showing stronger primary-market activity, supported by limited prime coastal supply. Outlook Vietnam’s next property cycle is expected to favour patience and careful asset selection rather than short-term speculation. With average gross rental yields near 3.85%, investment returns will depend increasingly on infrastructure-led capital appreciation. Legally clear projects with strong connectivity and genuine end-user demand should remain best positioned, particularly for buyers with sufficient holding power and a multi-year investment horizon. Download to see insights from other country marketsDownload
Vietnam Residential Market Enters a More Selective Cycle Vietnam’s residential market opened 2026 in a transition phase, with prices still rising but liquidity cooling. This suggests the market is moving away from easy speculative gains toward a more disciplined cycle. Residential prices rose around 12% year-on-year in Q1 2026, while liquidity fell nearly 40%. However, there was no sign of distress selling, pointing to a healthy reset rather than a sharp downturn. Primary condominium prices reached new highs across major cities. In Hanoi, average prices were around USD 3,950 per sqm, up 30% year-on-year. In post-merger Ho Chi Minh City, prices averaged around USD 3,900 per sqm, supported by new supply and limited premium stock. Supply also improved. Ho Chi Minh City recorded around 8,010 new condo launches, up 104% year-on-year. Yet affordability remains the key challenge, with much of the new supply priced above the level affordable to mass-market buyers. Strong Fundamentals, But Investors Are More Careful Vietnam’s underlying fundamentals remain supportive. The economy grew 8.02% in 2025, while real estate FDI reached USD 389.5 million in Q1 2026, representing around 7.2% of total inflows. However, investor behaviour is changing. Demand is now concentrating on projects with clear legal status, reliable construction progress and long-term value. Satellite locations such as Binh Duong and Ba Ria-Vung Tau are gaining attention as central city prices continue to stretch. Outlook Vietnam’s property market is expected to remain attractive, but more selective. With average gross rental yields at around 3.85%, the market is less of a pure income play and more of a capital appreciation and infrastructure-led growth story. Buyers with strong holding power, careful project selection and a long-term view are likely to be better positioned than short-term speculators. Download to see insights from other country marketsDownload
Sẵn sàng bắt đầu?
Liên hệ ngay bây giờ.