

Leader ∙ IRealty
Khaidir Bin Zakaria
REN33500
Về Khaidir Bin Zakaria
Khaidir Bin Zakaria is a registered Real Estate Negotiator (REN 33500) with the Board of Valuers, Appraisers, Estate Agents and Property Managers (LPEPH), Malaysia, with over five years of experience in residential, commercial, and new launch properties. He provides professional buyer and seller rep... Khaidir Bin Zakaria is a registered Real Estate Negotiator (REN 33500) with the Board of Valuers, Appraisers, Estate Agents and Property Managers (LPEPH), Malaysia, with over five years of experience in residential, commercial, and new launch properties. He provides professional buyer and seller representation, strategic property listings, and property management services. Khaidir also incorporates Shariah-compliant estate planning solutions and GeoAI-based market analysis to support informed, data-driven property decisions.
5 năm tại IQI
46 giao dịch
15 bất động sản để bán
10 bất động sản cho thuê
Địa điểm Dịch vụ của Khaidir Bin Zakaria
Địa điểm Dịch vụ của Khaidir Bin Zakaria
Danh sách của tôi

Sri Bukit Tunku Condominium, Kuala Lumpur
3, Lorong Tun Ismail, Kuala Lumpur, 50480 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
₫ 4,581,135,365
Được liệt kê vào tháng 11 20, 2025

Bungalow Land for Sale in Bayu Lakehomes, Mantin, Negeri Sembilan.
Jalan Bayu Meranti 1B
₫ 2,211,582,590
Được liệt kê vào tháng 12 8, 2023

MENARA TH PERDANA, Jalan Sultan Ismail
Jln Sultan Ismail, Chow Kit, 50250 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
₫ 90,990,827 /tháng
Được liệt kê vào tháng 11 19, 2025

3 Storey Twin Villa Sera @ Presint 8, Putrajaya
Presint 8, 62250 Putrajaya, Wilayah Persekutuan Putrajaya
₫ 63,181,755 /tháng
Được liệt kê vào tháng 11 19, 2025

YARA TWINVILLA, PRESINT 8, PUTRAJAYA
Jalan Presint 8, Putrajaya
₫ 20,852,064,420
Được liệt kê vào tháng 11 27, 2024

Bangunan Setia 1, Damansara Heights
Bukit Damansara, 50490 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
₫ 57,520,104 /tháng
Được liệt kê vào tháng 11 19, 2025

Alam Damai, Jalan Damai Jaya 1
Alam Damai, 56000 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
₫ 22,115,825,900
Được liệt kê vào tháng 11 24, 2025

Perdana Hills, Presint 11, Bandar Putrajaya
Jalan P11 A 6/1, Presint 11, 62300 Putrajaya, Wilayah Persekutuan Putrajaya
₫ 7,898,509,250
Được liệt kê vào tháng 11 21, 2025

Seksyen 23
Seksyen 23 40300 Shah Alam Selangor
₫ 259,071,103 /tháng
Được liệt kê vào tháng 11 11, 2025

CIMB Hub – Jalan Sultan Ismail Kuala Lumpur
Jln Sultan Ismail, Kuala Lumpur, 50250 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
₫ 16,428,899 /tháng
Được liệt kê vào tháng 11 19, 2025

Presint 8 Bandar Putrajaya
Jalan P8, Presint 8, 62000 Wilayah Persekutuan Putrajaya, Putrajaya
₫ 8,846,330,360
Được liệt kê vào tháng 11 20, 2025
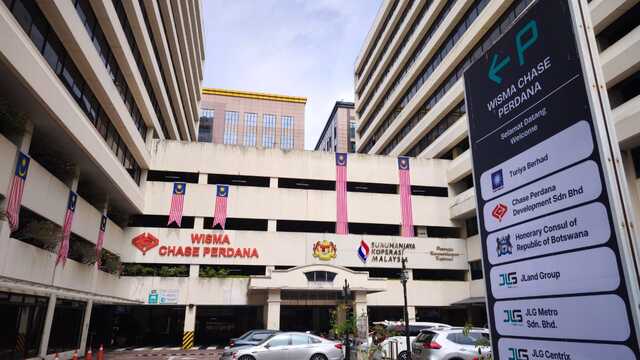
Wisma Chase Perdana
Changkat Semantan
₫ 556,055,051 /tháng
Được liệt kê vào tháng 8 27, 2026

Pangsapuri Putra Damai
Presint 11, 62300 Putrajaya, Wilayah Persekutuan Putrajaya
₫ 1,579,701,850
Được liệt kê vào tháng 11 19, 2025

Multi Level Warehouse Shah Alam Seksyen 33
Shah Alam Seksyen 33
₫ 1,017,327,991 /tháng
Được liệt kê vào tháng 11 26, 2025

Menara TH Selborn, Jalan Tun Razak, Kampung Baru
Jln Tun Razak, Kampung Baru, 50400 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
₫ 83,408,258 /tháng
Được liệt kê vào tháng 11 19, 2025

Menara Dungun, Damansara Heights
46, Jalan Dungun, Bukit Damansara, 50490 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
₫ 187,668,580 /tháng
Được liệt kê vào tháng 11 19, 2025

Denai Alam, Shah Alam
Denai Alam, 40160, Selangor
₫ 8,214,449,620
Được liệt kê vào tháng 11 21, 2025

KIARA VIEW, DESA SRI HARTAMAS
Desa Sri Hartamas
₫ 20,220,183,680
Được liệt kê vào tháng 11 19, 2024

Sejati Lakeside
Persiaran Bestari
₫ 6,634,747,770
Được liệt kê vào tháng 11 21, 2025

Bandar Kinrara, Puchong
Bandar Kinrara, 47180 Puchong, Selangor Darul Ehsan.
₫ 100,089,909,216
Được liệt kê vào tháng 11 20, 2025

Casablanca Alam Impian
Jln Hang Nadim 35/46L Alam Impian, 40470 Shah Alam, Selangor
₫ 9,983,715,692
Được liệt kê vào tháng 11 24, 2025

Cinta Condominium @ U-Thant
Jalan Madge Taman U Thant, 55000 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
₫ 94,782,111 /tháng
Được liệt kê vào tháng 11 27, 2025

Bandar Baru Enstek, Negeri Sembilan
Jalan Timur 5/1H Bandar Baru Enstek, 71760 Bandar Baru Enstek, Negeri Sembilan
₫ 2,590,711,034
Được liệt kê vào tháng 11 25, 2025

The RuMa Hotel and Residences
7, Jalan Kia Peng,
₫ 21,970,493,330
Được liệt kê vào tháng 11 19, 2024

Country Heights Damansara Kuala Lumpur
Country Heights Damansara Kuala Lumpur
₫ 91,622,707,300
Được liệt kê vào tháng 11 20, 2025
Các dự án mới ra mắt của chúng tôi
Khám phá các bất động sản trong và xung quanh Putrajaya, Malaysia. Mua căn hộ, nhà phố, biệt thự, văn phòng thương mại, cửa hàng và bán lại với 100% tự tin tại IQI Global.
 Nằm ở Kubang Semang
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Bắt đầu từ ₫ 91,594,399,043
Được liệt kê vào tháng 1 23, 2026
 Nằm ở Bukit Minyak
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Bắt đầu từ ₫ 7,606,580,348
Được liệt kê vào tháng 1 23, 2026
 Loại dự án công nghiệp
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Bắt đầu từ ₫ 31,688,819,111
Được liệt kê vào tháng 1 23, 2026
 Diện tích đất rộng rãi
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Bắt đầu từ ₫ 7,069,481,719
Được liệt kê vào tháng 1 23, 2026
 Nằm ở Bukit Mertajam
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Bắt đầu từ ₫ 5,168,784,453
Được liệt kê vào tháng 1 23, 2026
 Nằm ở Nibong Tebal
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Bắt đầu từ ₫ 3,475,344,070
Được liệt kê vào tháng 1 23, 2026
Máy tính thế chấp
Tính toán khoản thanh toán hàng tháng ước tính của bạn và lập kế hoạch chi tiêu hàng tháng một cách tốt.
Máy tính thế chấp chỉ mang tính tham khảo. Số tiền thực tế có thể khác.
Thanh toán hàng tháng
Gửi kết quả máy tính thế chấp cho tôi
Máy tính đủ điều kiện vay mua nhà
Tính toán số tiền vay tiềm năng của bạn và đánh giá khả năng mua nhà của bạn.
Lợi nhuận cho thuê
Tính toán lợi nhuận cho thuê tiềm năng và đánh giá hiệu suất đầu tư của bất động sản.
Kế hoạch tiết kiệm trả trước
Tạo kế hoạch tiết kiệm có cấu trúc và xác định số tiền cần tiết kiệm hàng tháng cho kế hoạch trả trước của bạn.
Máy tính phí giao dịch bất động sản Malaysia
Ước tính tổng phí giao dịch cho việc mua bất động sản Malaysia.
Blog & tin tức IQI
Các bài viết được tuyển chọn đặc biệt cho bản tóm tắt hàng ngày về tin tức bất động sản địa phương và toàn cầu của bạn.
5 Th10, 2026
Vietnam Property Market October 2026: Policy Reform Reshapes a Resilient but Selective Market
Policy Reform Takes Centre Stage Vietnam’s residential market is entering the final quarter of 2026 with policy, rather than pricing, driving the conversation. Resolution 21-NQ/TW is set to shape the next round of Land Law and housing amendments, including proposals linking apartment use to a building’s service life and placing greater reconstruction obligations on owners. The changes could also introduce heavier taxation on excess property profits and vacant or unused assets, while land allocation may increasingly favour commercial apartment supply. MBS Research expects some new apartment projects could shift toward 50–99-year tenures, although implementing rules have not yet been issued. Despite the uncertainty, activity remains substantial. Nearly 34,000 new homes were launched nationwide in Q2, with around 19,600 units sold, equivalent to an absorption rate of approximately 58%. Average primary apartment prices reached around VND 80 million per sqm, up 10% from 2025. Strong Economy Meets Financing Pressure Hanoi illustrates the market’s growing divide. Q2 sales fell 45% year-on-year, even as luxury-led launches pushed primary prices up 36% to about US$4,659 per sqm. Mortgage rates of 12–14% remain the biggest obstacle for first-time buyers. At the same time, Vietnam’s macroeconomic backdrop remains strong. GDP grew 8.39% year-on-year in Q2, while registered FDI reached US$40.63 billion in the first eight months, up 55.4%. Of this, US$5.32 billion was committed to real estate. Outlook Vietnam is likely to remain a selective, end-user-led market rather than enter a broad rally. High financing costs and new legal considerations will make cash strength, legal clarity and land-backed assets increasingly important. For buyers and investors, due diligence around ownership structure, land-use rights and project legality will matter as much as location and product quality. Vietnam, October 2026 The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
Hanoi Apartment Market Faces Resale Pressure Hanoi’s apartment market is entering a more cautious phase as resale pressure increases among investors who bought off-plan or during construction with short-term flipping strategies. After several years of strong price growth, market conditions have cooled. Capital gains are no longer guaranteed, while the end of mortgage grace periods is exposing some investors to higher floating interest rates and heavier repayment obligations. This is encouraging more owners to sell, with liquidity and debt reduction becoming a greater priority than maximising returns. According to market data cited in the report, asking prices at several Hanoi projects have already corrected from their previous peaks. Imperia Sola Park fell around 12.6%, Lumi Hanoi declined approximately 9.5%, while Kepler Land recorded an 8.6% correction. Market Shifts From Speculation to Liquidity The change marks an important shift in Vietnam’s residential market. Some leveraged investors are no longer holding properties in expectation of further short-term appreciation. Instead, they are looking to exit quickly, reduce debt exposure and, in some cases, accept losses. For genuine homebuyers and investors with stronger cash positions, this may create improved negotiating conditions in Hanoi’s secondary apartment market. Rather than competing in a rapidly rising market, buyers may now have greater scope to negotiate on properties where sellers are under financing pressure. Outlook Hanoi’s apartment market is likely to remain more selective and liquidity-driven in the near term. Resale pressure could continue to create opportunities for buyers who have sufficient cash and are willing to negotiate carefully. The key advantage is shifting towards financially prepared buyers, particularly those able to identify motivated sellers and acquire quality secondary-market units at prices below previous market peaks. The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
30 Th07, 2026
Vietnam Property Market Outlook 2026: Infrastructure Corridors Lead the Next Growth Cycle
Vietnam’s Housing Market Enters a Selective Reset Vietnam’s residential market entered August 2026 in a period of consolidation. Prices remain relatively firm, but transaction activity is slower as buyers become more selective and borrowing costs stay elevated. During Q2 2026, developers launched approximately 12,000 primary condominiums across the enlarged Ho Chi Minh City market and more than 4,000 units in Hanoi. However, luxury absorption remained below 30% in Ho Chi Minh City, while Hanoi’s take-up rate eased to around 20%. Inner-city primary prices reached approximately USD 5,400 to USD 9,500 per square metre. Pressure was more visible in the secondary market, where prices declined 5% to 8% in Ho Chi Minh City and by as much as 12% in parts of Hanoi. Floating mortgage rates of 13% to 16% are encouraging some owners to lower asking prices. However, the market has not experienced widespread distress, while the new land-price framework is helping maintain a floor under development costs and headline prices. Infrastructure Redirects Property Demand Vietnam has approximately 234 major infrastructure projects worth VND 3.4 quadrillion underway. These investments are shifting demand from crowded central districts towards better-connected suburban and regional corridors. In the south, growth is concentrating around the Ho Chi Minh City and Dong Nai corridor, supported by Long Thanh International Airport, new ring roads, expressways and Metro Line 1. Northern demand is moving towards Hanoi’s gateway districts and neighbouring Hung Yen and Bac Ninh. Da Nang is also showing stronger primary-market activity, supported by limited prime coastal supply. Outlook Vietnam’s next property cycle is expected to favour patience and careful asset selection rather than short-term speculation. With average gross rental yields near 3.85%, investment returns will depend increasingly on infrastructure-led capital appreciation. Legally clear projects with strong connectivity and genuine end-user demand should remain best positioned, particularly for buyers with sufficient holding power and a multi-year investment horizon. Download to see insights from other country marketsDownload
Vietnam Residential Market Enters a More Selective Cycle Vietnam’s residential market opened 2026 in a transition phase, with prices still rising but liquidity cooling. This suggests the market is moving away from easy speculative gains toward a more disciplined cycle. Residential prices rose around 12% year-on-year in Q1 2026, while liquidity fell nearly 40%. However, there was no sign of distress selling, pointing to a healthy reset rather than a sharp downturn. Primary condominium prices reached new highs across major cities. In Hanoi, average prices were around USD 3,950 per sqm, up 30% year-on-year. In post-merger Ho Chi Minh City, prices averaged around USD 3,900 per sqm, supported by new supply and limited premium stock. Supply also improved. Ho Chi Minh City recorded around 8,010 new condo launches, up 104% year-on-year. Yet affordability remains the key challenge, with much of the new supply priced above the level affordable to mass-market buyers. Strong Fundamentals, But Investors Are More Careful Vietnam’s underlying fundamentals remain supportive. The economy grew 8.02% in 2025, while real estate FDI reached USD 389.5 million in Q1 2026, representing around 7.2% of total inflows. However, investor behaviour is changing. Demand is now concentrating on projects with clear legal status, reliable construction progress and long-term value. Satellite locations such as Binh Duong and Ba Ria-Vung Tau are gaining attention as central city prices continue to stretch. Outlook Vietnam’s property market is expected to remain attractive, but more selective. With average gross rental yields at around 3.85%, the market is less of a pure income play and more of a capital appreciation and infrastructure-led growth story. Buyers with strong holding power, careful project selection and a long-term view are likely to be better positioned than short-term speculators. Download to see insights from other country marketsDownload
Sẵn sàng bắt đầu?
Liên hệ ngay bây giờ.
