Negotiator ∙ Vietnam
Nguyễn Thị Loan

เกี่ยวกับ Nguyễn Thị Loan
Leveraging market knowledge and negotiation skills to deliver exceptional results. Your real estate success is my priority. Ready to make your real estate dreams a reality? Let's chat. Your dream home awaits.
ลิงก์โซเชียล Nguyễn Thị Loan
ไม่มีลิงก์โซเชียล
รายการของฉัน
ไม่มีรายการในขณะนี้
โครงการที่เพิ่งเปิดตัวใหม่ของเรา
ค้นพบอสังหาริมทรัพย์ในและรอบๆ Vietnam, Vietnam ซื้ออพาร์ทเมนต์ บ้านเดี่ยว บังกะโล สำนักงานเชิงพาณิชย์ ร้านค้า และการขายต่อด้วยความมั่นใจ 100% ที่ IQI Global
 ชุมชนที่มีชื่อเสียง
Sanctuary Ho Tram
Ho Tram, Phuoc Thuan Ward, Xuyen Moc, Ba Ria, Vung Tau, Bà Rịa, BV, Vietnam
เริ่มจาก ฿ 21,747,000
ลงรายการเมื่อ พฤษภาคม 12, 2023
 สไตล์สิงคโปร์ทันสมัย
One Verandah
Bát Nàn, Phường Thạnh Mỹ Lợi, Quận 2, Thành phố Hồ Chí Minh, Vietnam
เริ่มจาก ฿ 5,272,000
ลงรายการเมื่อ พฤษภาคม 12, 2023
 ภูมิทัศน์สวน
Thủ Thiêm Zeit River
TP, Trần Bạch Đằng, Phường An Khánh, Quận 2, Thủ Đức, Thành phố Hồ Chí Minh, Vietnam
เริ่มจาก ฿ 16,475,000
ลงรายการเมื่อ กุมภาพันธ์ 27, 2023
 การวางตำแหน่งหรูหรา
Lancaster Legacy
230 Đ. Nguyễn Trãi, Phường Nguyễn Cư Trinh, Quận 1, Thành phố Hồ Chí Minh, Vietnam
เริ่มจาก ฿ 11,862,000
ลงรายการเมื่อ กุมภาพันธ์ 24, 2023
 บริหารโดยแอสคอตต์
King Crown Infinity
218 Đ. Võ Văn Ngân, Bình Thọ, Thủ Đức, Thành phố Hồ Chí Minh, Vietnam
เริ่มจาก ฿ 6,590,000
ลงรายการเมื่อ กุมภาพันธ์ 24, 2023
 อพาร์ตเมนต์โรงแรม
Ho Tram IXORA by Fusion
Đường Ven Biển, Phước Thuận, Xuyên Mộc, Bà Rịa - Vũng Tàu, Vietnam
เริ่มจาก ฿ 3,426,800
ลงรายการเมื่อ กุมภาพันธ์ 20, 2023
เครื่องคำนวณสินเชื่อบ้าน
คำนวณการชำระเงินรายเดือนโดยประมาณและวางแผนค่าใช้จ่ายรายเดือนของคุณให้ดี
เครื่องคำนวณสินเชื่อบ้านใช้สำหรับอ้างอิงเท่านั้น จำนวนจริงอาจแตกต่าง
การชำระเงินรายเดือน
ส่งผลลัพธ์เครื่องคิดเลขสินเชื่อบ้านให้ฉัน
เครื่องคำนวณสิทธิ์สินเชื่อบ้าน
คำนวณจำนวนเงินกู้ที่อาจได้รับและประเมินความสามารถในการซื้อบ้านของคุณ
ผลตอบแทนจากการเช่า
คำนวณผลตอบแทนจากการเช่าที่อาจเกิดขึ้นและประเมินประสิทธิภาพการลงทุนของอสังหาริมทรัพย์
แผนการออมเงินดาวน์
สร้างแผนการออมที่มีโครงสร้างและกำหนดจำนวนเงินที่ต้องออมรายเดือนสำหรับแผนการดาวน์ของคุณ
เครื่องคำนวณค่าธรรมเนียมการทำธุรกรรมอสังหาริมทรัพย์มาเลเซีย
ประมาณการค่าธรรมเนียมทำธุรกรรมทั้งหมดและงบประมาณอย่างแม่นยำสำหรับการซื้ออสังหาริมทรัพย์มาเลเซีย
บล็อกและข่าวสาร IQI
บทความที่คัดสรรมาโดยเฉพาะสำหรับการสรุปข่าวอสังหาริมทรัพย์ในประเทศและต่างประเทศของคุณ
Bangkok's Condominium Market Shows Stronger Activity Thailand's residential property market is experiencing changing supply conditions, with Bangkok's condominium sector showing notable differences between locations. In Q2 2026, Bangkok and five surrounding provinces recorded approximately 85,249 condominium units in housing supply. Low-rise housing represented a larger segment, with approximately 128,834 units. Meanwhile, regional condominium sales activity displayed strong momentum in selected areas. Sukhumvit condominium sales increased approximately 338.6%, highlighting considerable growth in transaction activity. The Bang Ya–Bang Bua Thong–Bang Kruai–Sai Noi corridor also recorded approximately 59% sales growth, reflecting demand beyond Bangkok's established central locations. However, strong sales growth in individual areas does not necessarily indicate uniform market recovery. Location and Inventory Shape Investment Decisions Thailand's broader residential sector continues to demonstrate mixed market conditions. The national condominium market recorded approximately 214,083 transactions in Q2 2026, while overall condominium supply increased 19.5% year-on-year. Total transaction activity remained weaker, declining approximately 6.6% annually. This contrast between rising supply and softer overall transactions reinforces the need for careful property selection. Monthly condominium absorption rates also varied significantly between locations. Sukhumvit recorded an absorption rate of approximately 5.2% per month, compared with 3.3% in the Bang Ya–Bang Bua Thong–Bang Kruai–Sai Noi corridor. For property buyers and investors, transport access, employment centres, shopping facilities, healthcare services and overall neighbourhood convenience remain important demand drivers. Outlook Thailand's residential property market offers opportunities in locations supported by genuine end-user demand. However, inventory levels, project positioning, transport connectivity and absorption rates will remain critical considerations as developers and buyers navigate changing supply conditions. The contents of this article were contributed by Somsak Chutisilp, Head of IQI Thailand. Download to see insights from other country marketsDownload
5 ต.ค., 2026
Thailand Property Market October 2026: Luxury Condominiums Lead Bangkok’s Selective Growth
Luxury Segment Drives Bangkok Condominium Activity Downtown Bangkok recorded more new condominium launches in H1 2026 than during the same period a year earlier, with luxury and super-luxury developments emerging as the main drivers of new supply. Completed condominium projects achieved an average sales rate of 93%, led by the luxury segment at 95%. Projects still under construction recorded a lower average sales rate of 52%, although the super-luxury segment significantly outperformed at 85%. The figures suggest that buyers are becoming more cautious, but demand remains strong for premium developments offering the right combination of location, product quality and brand strength. This reinforces the increasingly selective nature of Bangkok’s upper-end property market. Foreign Buyer Demand and Branded Residences Gain Momentum Foreign participation is becoming a more important component of central Bangkok condominium demand. Thai buyers accounted for 68% of purchases, while foreign buyers represented 32%—well above the average 18% foreign-buyer share recorded between 2021 and 2025. In the super-luxury segment, the leading overseas buyers came from Japan, the United Kingdom, Taiwan and Russia. Branded residences are also becoming an increasingly important market driver, strengthening international recognition and helping developments differentiate themselves through reputation, service and perceived value. Outlook Thailand’s premium residential market is likely to remain selective but resilient, with the strongest demand focused on well-located, differentiated projects. As competition intensifies, success in the luxury and super-luxury segments will depend less on price alone and more on brand, product quality, location and overall value. The contents of this article were contributed by Somsak Chutisilp, Head of IQI Thailand. Download to see insights from other country marketsDownload
Rama IX Leads Condominium Interest Despite a broader property market slowdown, housing demand in Bangkok remains active, with buyers and renters continuing to search online for well-connected and affordable locations. Rama IX emerged as the most discussed condominium location, accounting for 42% of online mentions. Its appeal is driven by convenient travel, access to rail services, proximity to workplaces and prices viewed as more accessible than those in central Bangkok. Sukhumvit ranked second with 24% of condominium interest, supported by strong transport links, urban rail access and comprehensive amenities. One-bedroom units were particularly popular. Other locations drawing attention included Don Mueang at 14%, Ekkamai at 11% and Vibhavadi Rangsit at 9%. In Don Mueang and Vibhavadi Rangsit, buyers showed notable interest in one-bedroom units priced at no more than THB2 million. Bang Na Dominates Landed Housing Demand For detached houses and townhouses, Bang Na clearly led the market conversation with a 75% share. Buyers were attracted by transport convenience, surrounding amenities and the area’s residential environment. The next most discussed locations were Rama II at 9%, Rama IX and Thonglor at 6% each, and Phatthanakan at 4%. The results suggest that buyers continue to prioritise connectivity, affordability and everyday convenience when choosing where to live. Outlook Bangkok’s residential demand is likely to remain highly location-specific, with well-connected areas offering better value continuing to attract attention. For condominiums, Rama IX stands out as a key affordability and connectivity play, while Bang Na remains the strongest landed housing choice among online buyers and renters. The market may be softer overall, but demand remains visible where transport access, amenities and pricing align with buyer needs. The contents of this article were contributed by Somsak Chutisilp, Head of IQI Thailand. Download to see insights from other country marketsDownload
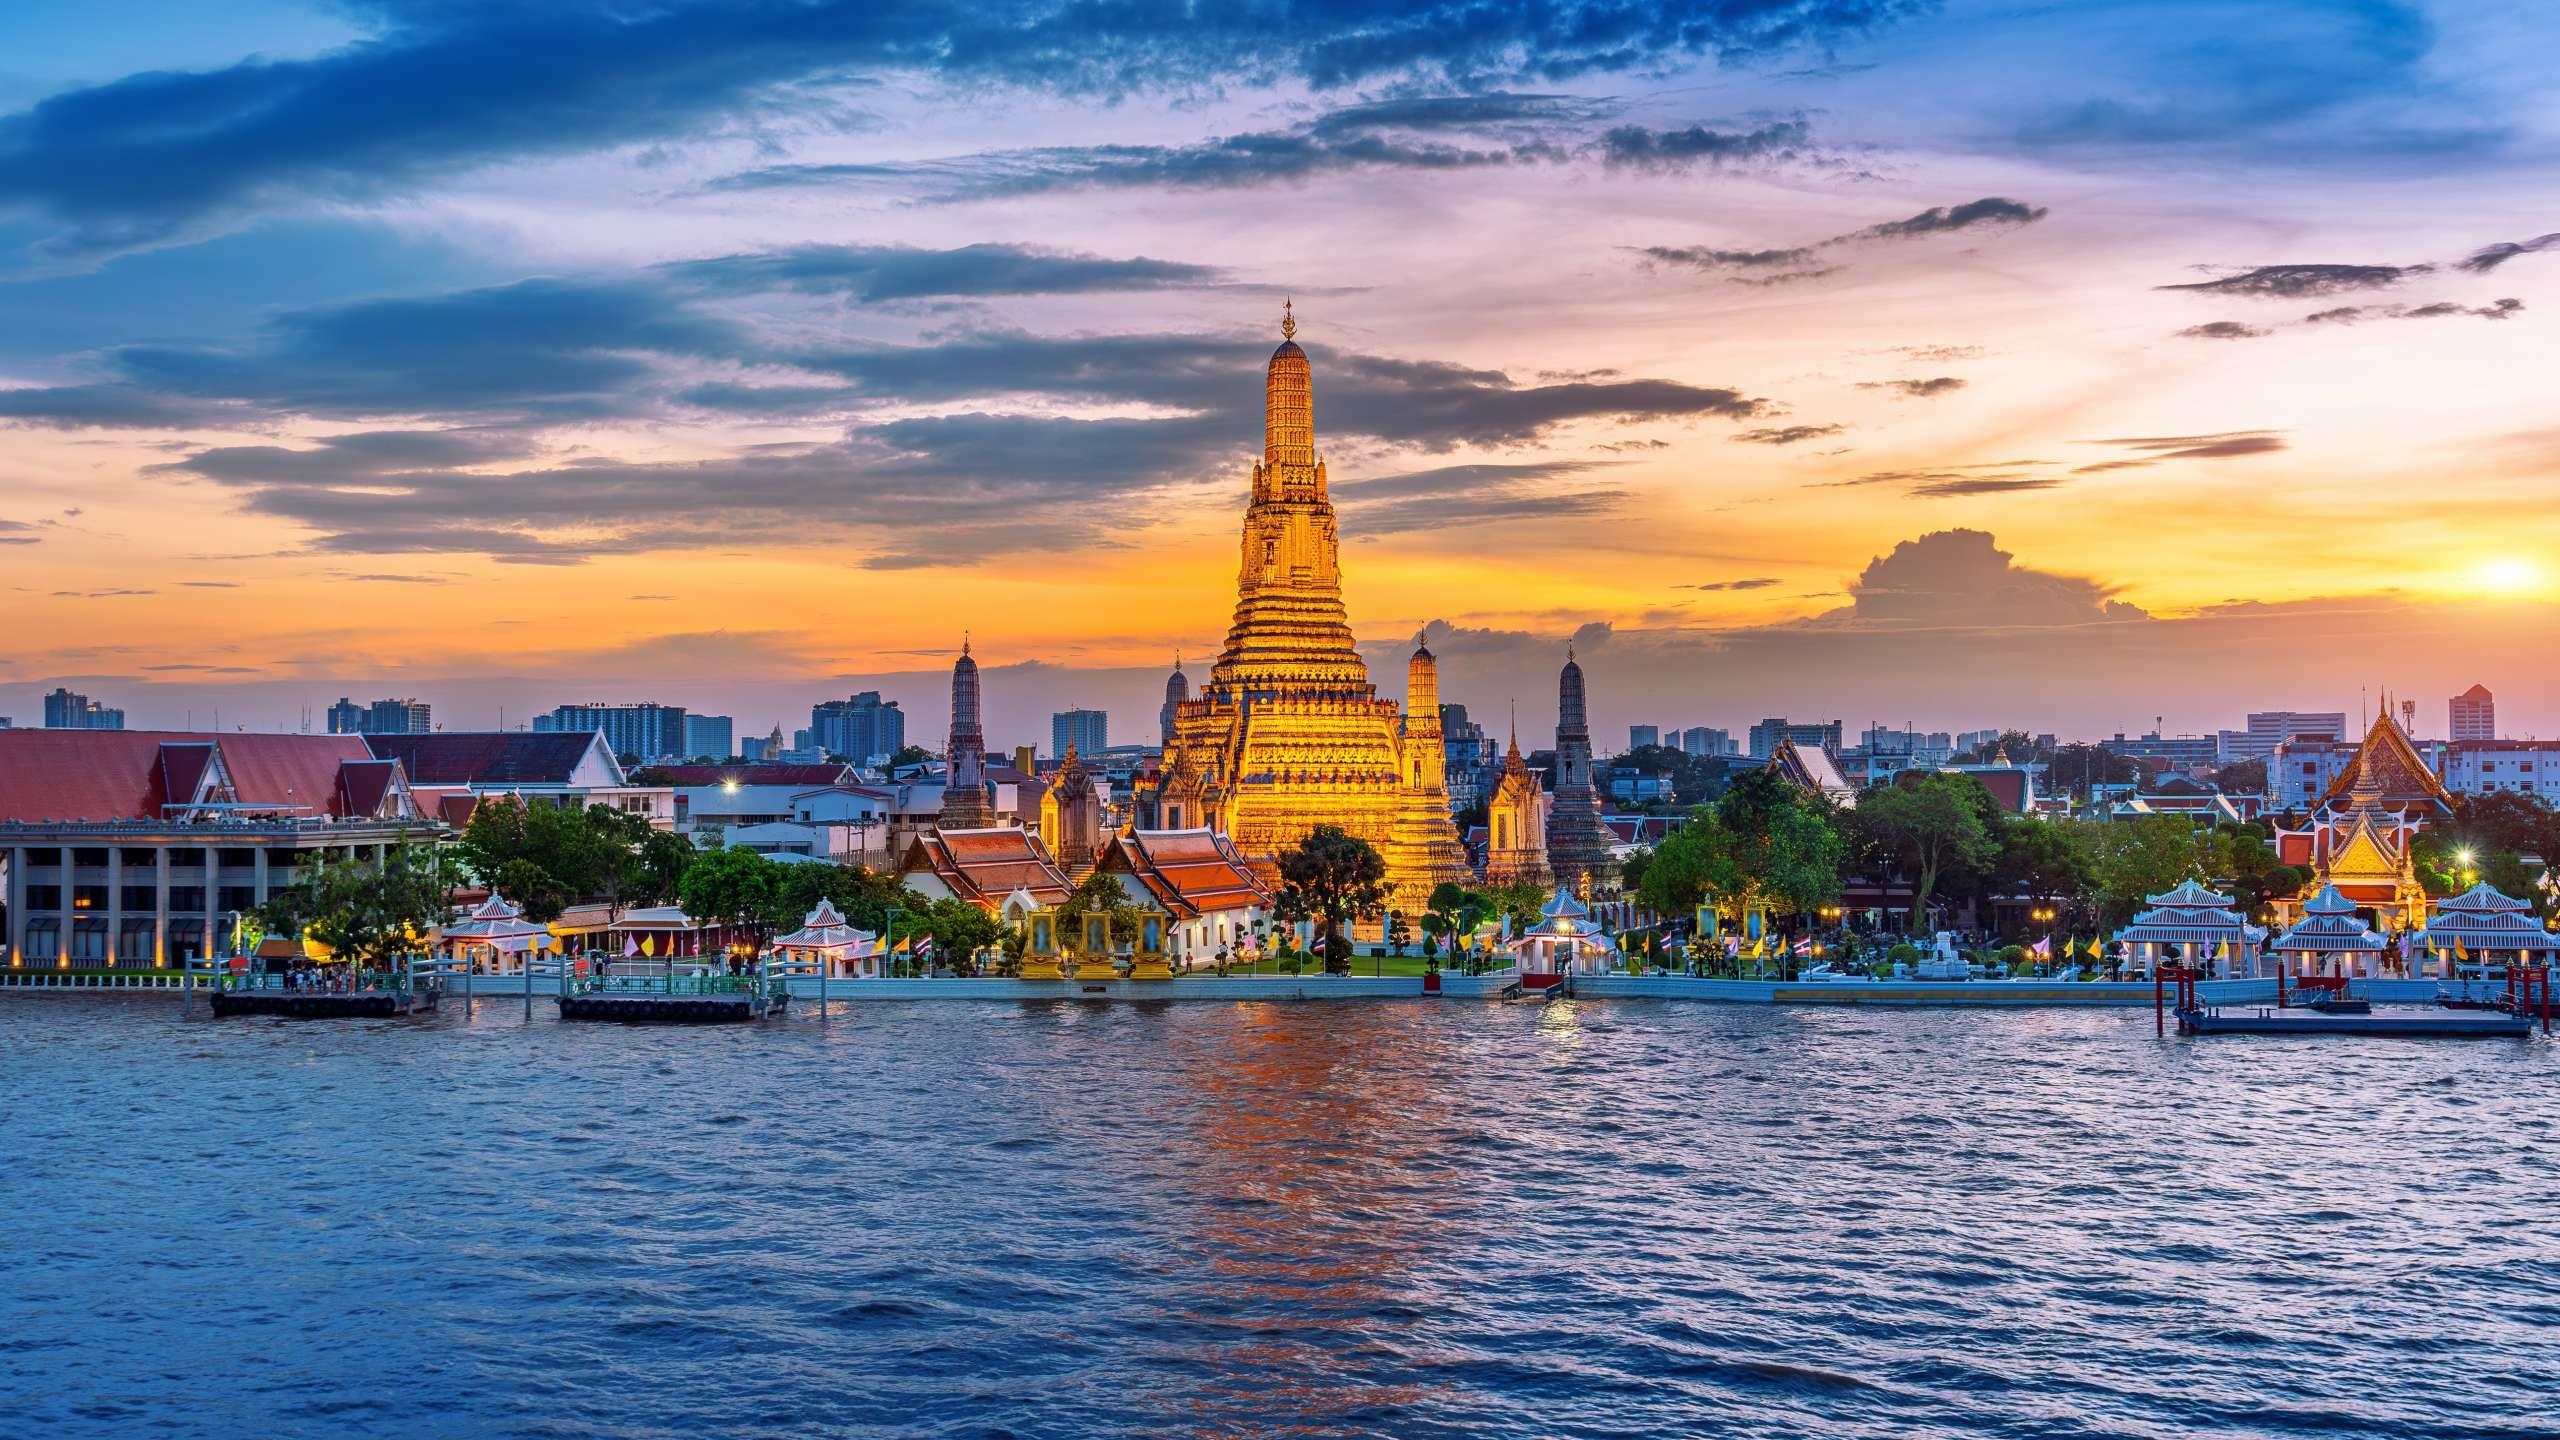
Bangkok Retail Market Enters a New Phase Bangkok’s retail property market is evolving as developers place greater emphasis on transit-oriented locations, experiential concepts and asset repositioning. Total retail supply reached 9.27 million square metres in Q1 2026, recording only a marginal 0.12% quarter-on-quarter decline. This reflects a relatively stable market despite wider economic uncertainty and a fresh pipeline of new space. Retail development is becoming increasingly divided between neighbourhood-focused community malls and larger shopping centres connected to mass-transit networks. Another 300,000 square metres of retail space is scheduled for completion during 2026, increasing competition among existing and upcoming projects. Occupancy Improves as Tenant Demand Shifts Bangkok’s overall retail occupancy rate rose to 89% in Q1 2026, compared with 85% a year earlier and around 84% throughout much of 2024. Demand remains strongest among luxury brands, food and beverage operators, wellness providers and experience-led tenants. Higher-performing malls are allocating more space to leisure, lifestyle services and community activities that encourage repeat visits. CBD shopping mall rents averaged 2,852 baht per square metre per month, above the northern fringe at 2,230 bahtand the eastern fringe at 2,300 baht. Community malls remained more affordable, with average CBD rents of 1,755 baht per square metre, compared with 1,200 baht in the northern fringe and 1,250 baht in the eastern fringe. Outlook Competition may place pressure on average occupancy as consumers become more selective about where they spend their time and money. Projects combining strong transit access, distinctive experiences and a clear market identity are expected to perform best. Retail centres that respond to changing consumer habits through wellness, dining, entertainment and community-focused concepts should remain better positioned as new supply enters the Bangkok market. Download to see insights from other country marketsDownload
พร้อมที่จะเริ่มหรือยัง?
ติดต่อเราตอนนี้