

Team Leader (Subsales) ∙ United
Stephanie Yap
REN20525
Team Leader (Subsales) ∙ United
Stephanie Yap
REN20525
About Stephanie Yap
Leveraging market knowledge and negotiation skills to deliver exceptional results. Your real estate success is my priority. Ready to make your real estate dreams a reality? Let's chat. Your dream home awaits.
4 years at IQI
135 transactions
104 properties on sale
58 properties on rent
Contact Stephanie Yap
Stephanie Yap Social Links
No social links available.
Stephanie Yap's Service Locations
Stephanie Yap's Service Locations
My Listings
Gravit8 @ Klang South
Jalan Bayu Laut
QAR 1,958 /month
Listed on September 2, 2026
Taman Sentosa
Jalan Dato Yusof Shahbudin 30
QAR 845 /month
Listed on August 26, 2026

Taman Sentosa
Jalan Dato Abdul Hamid 16A
QAR 363,038
Listed on September 23, 2024
Laman Impian Bandar Botanic Klang
Bandar Botanic
QAR 1,335 /month
Listed on August 26, 2026
Canary Garden @Bandar Bestari
Bandar Bestari KSL
QAR 1,494,864
Listed on August 11, 2026
Taman Menara Maju, Klang
LORONG MANICKAVASAGAM
QAR 389,732
Listed on August 14, 2026
Kiara East
Jalan 3/18A Taman Mastiara
QAR 425,324
Listed on February 27, 2026

Jalan Setia Utama U13/37M
Jalan Setia Utama U13/37M
QAR 1,067,760
Listed on April 8, 2025
Vista Bayu Apartment, Taman Bayu Perdana
Jalan Batu Unjur 9
QAR 1,068 /month
Listed on April 15, 2026
Taman Perindustrian Pandamaran
Pandamaran
QAR 4,983 /month
Listed on August 14, 2026

Taman Sutera
43000 Kajang
QAR 4,894 /month
Listed on September 22, 2025
Taman Bayu Perdana
Jalan Batu Unjur
QAR 444,900
Listed on July 1, 2025
Bandar Puteri Klang
Jalan Sanggul
QAR 516,084
Listed on May 23, 2024
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
QAR 249,126
Listed on March 9, 2026
Kondo Idaman Cheng Hua
Jalan Sungai Jati
QAR 302,532
Listed on October 4, 2026

Golden Villa Apartment
Jln Temenggung 37, Taman Sentosa Perdana
QAR 204,654
Listed on April 16, 2024
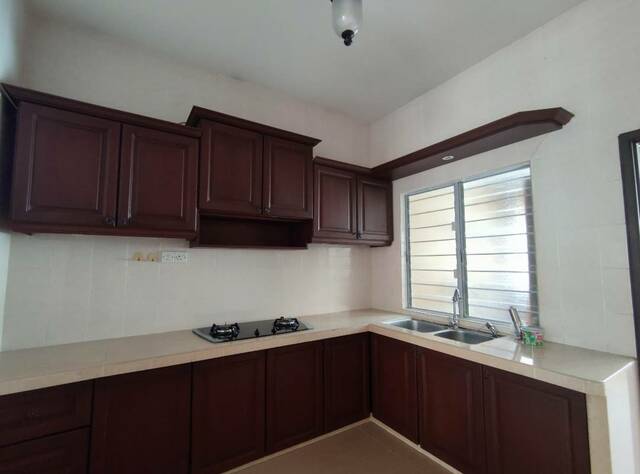
Bandar Botanic
Jalan Kiara
QAR 604,174
Listed on January 9, 2026
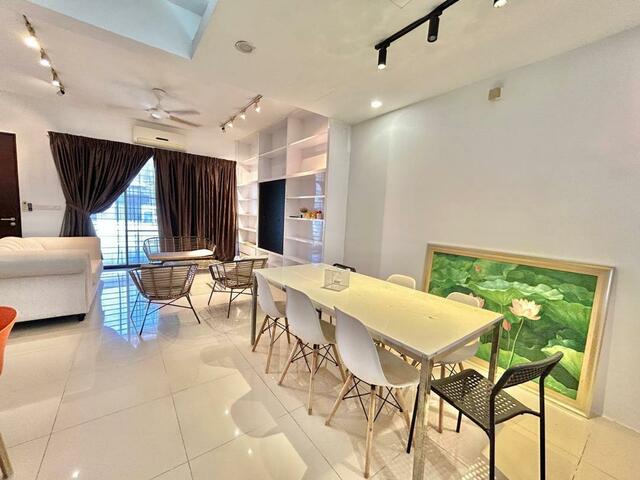
Ken Rimba
Jalan Lengkuas, Rimba Jaya
QAR 578,352
Listed on December 14, 2025
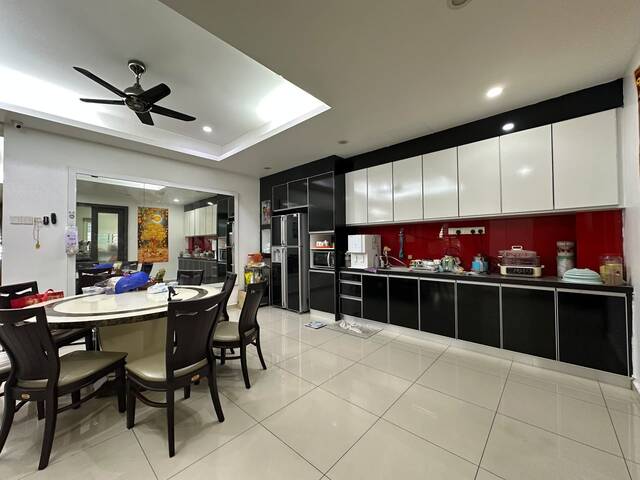
Bandar Parklands
Lorong Delima 16 Bukit Tinggi 3
QAR 1,421,900
Listed on September 10, 2026

Vista Indah Putra
Jalan Batu Unjur 8, 42000, Selangor
QAR 240,246
Listed on November 20, 2024
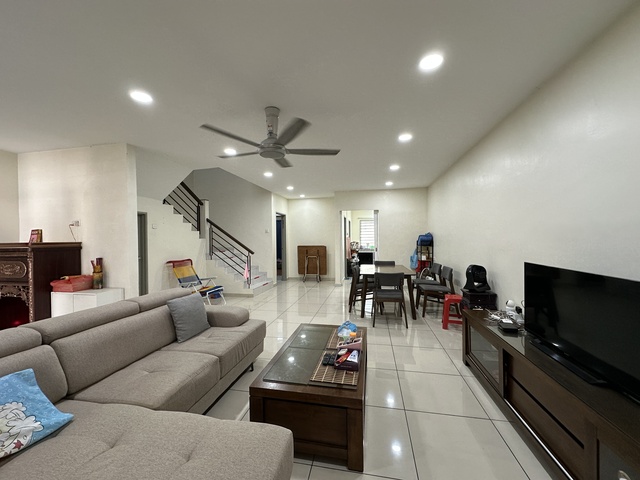
Taman Sri Jaromas
Jalan 3/4 Zinnia
QAR 516,084
Listed on May 9, 2026
Bandar Bukit Tinggi 1 Shop Apartment
Lorong Batu Nilam 1B
QAR 177,958
Listed on March 31, 2026
Bandar Puteri Klang
Jalan Pending
QAR 565,023
Listed on October 19, 2025
Bandar Puteri Klang
Jalan Gelang
QAR 532,100
Listed on January 12, 2026

Bandar Puteri Klang
Jalan Pending
QAR 516,066
Listed on February 20, 2025
Avenue Crest
Section 22, Batu Tiga, Shah Alam
QAR 186,858
Listed on March 30, 2026
Taman Riveria Perdana
Lorong Riveria 4
QAR 1,246 /month
Listed on September 19, 2026
Avenue Crest
Section 22, Batu Tiga, Shah Alam
QAR 1,068 /month
Listed on December 2, 2025
Setia City Residences @ Setia City
Jalan Setia Dagang AH U13/AH
QAR 667,348
Listed on December 2, 2025
SS2 Petaling Jaya
Jalan SS2
QAR 15,127 /month
Listed on September 14, 2026
Taman Telok
Jalan Dendang
QAR 1,068 /month
Listed on April 4, 2026
Bandar Bukit Tinggi
Lorong Batu Nilam 15
QAR 1,424 /month
Listed on April 20, 2026
Tropicana Aman Bayan Residences
Jalan Aman Bayan, Bandar Tropicana Aman, 42500 Telok Panglima Garang
QAR 783,024
Listed on September 20, 2026
Taman Perwira
Jalan Wira 4
QAR 240,246
Listed on September 4, 2026

Taman Sentosa
Jalan Dato Abdul Hamid 16
QAR 476,043
Listed on February 15, 2025
Merak Kayangan Court
Jalan Kapas
QAR 6,674 /month
Listed on September 17, 2025
Asteria Apartment @ Bandar ParkLand
BANDAR Parklands Bukit Tinggi
QAR 979 /month
Listed on October 7, 2026

Bandar Puteri Klang
Jalan Sanggul
QAR 578,192
Listed on June 23, 2023
Bandar Bukit Tinggi
Lorong Batu Nilam 14
QAR 516,084
Listed on February 5, 2026

Bandar Puteri Klang
Jalan Pending
QAR 578,352
Listed on November 22, 2024
Bandar Botanic
Persiaran Botanic
QAR 1,067,742
Listed on September 23, 2025
Gravit8 @ Klang South
Kota Bayuemas
QAR 1,157 /month
Listed on August 21, 2026
Prima Bayu
Jalan Batu Unjur 9
QAR 275,820
Listed on November 9, 2025

Eco Majestic
Lingkaran Eco Majestic
QAR 1,067,760
Listed on June 4, 2025
Telok Panglima Garang
Jalan Pahlawan 1
QAR 2,047 /month
Listed on December 14, 2025
Kota Bayuemas
Jalan Bayu Impian
QAR 1,602 /month
Listed on September 4, 2026

Desa Idaman, Taman Puchong Prima
Taman Puchong Prima Puchong
QAR 400,232
Listed on October 13, 2025
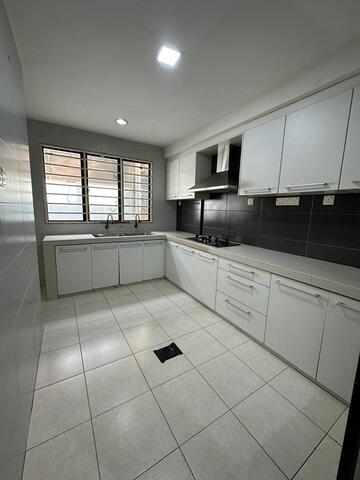
Puchong Hartamas
Puchong
QAR 1,049,964
Listed on October 9, 2026

Residensi Alami
Jalan Tinju 13/50, 40100, Selangor
QAR 400,410
Listed on April 28, 2025
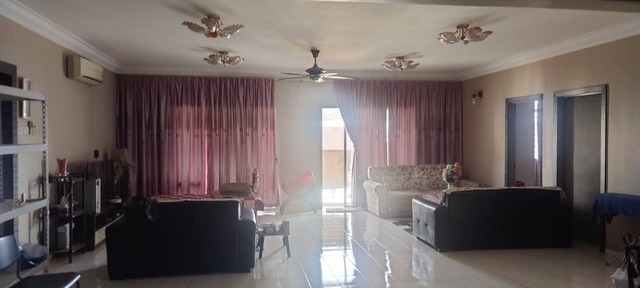
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
QAR 416,426
Listed on November 16, 2025
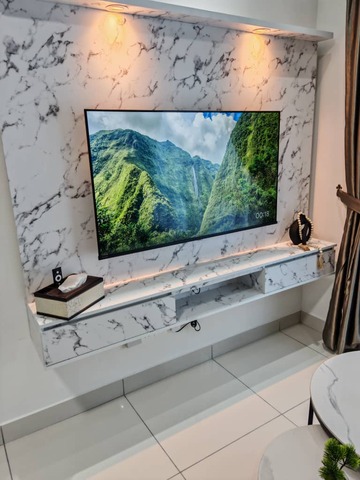
MIRAI Residence (Residensi Meriah)
Persiaran Kajang 2, Kajang
QAR 1,513 /month
Listed on October 8, 2026
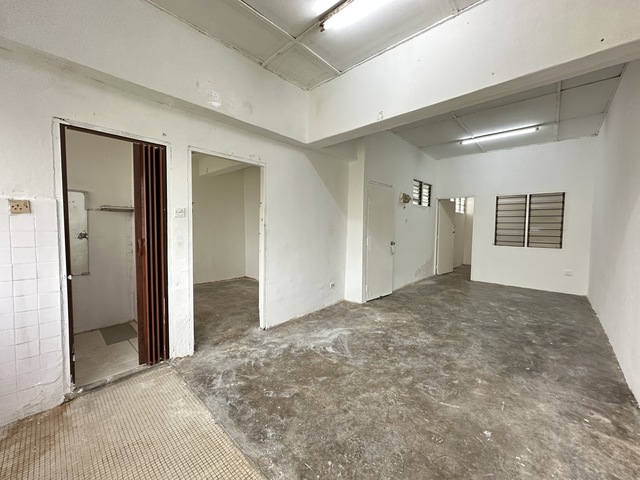
Taman Orkid Desa
Jalan 15a/142, Taman Orkid Desa
QAR 623 /month
Listed on September 4, 2026

Apartment Hijau Ria
Jalan 2/1, Taman Kepong Indah
QAR 256,262
Listed on February 25, 2025
Bandar Botanic
Jalan Akasia
QAR 2,669 /month
Listed on August 21, 2026
Bandar Puteri Klang
Jalan Kerongsang
QAR 431,553
Listed on November 13, 2025
Andira Park
Lebuh Bukit Puchong
QAR 711,840
Listed on November 10, 2025

Bandar Parklands
Lorong Kristal 5
QAR 960,984
Listed on September 11, 2026
Skyvilla, D Island Residence
Persiaran Utara
QAR 1,290 /month
Listed on April 16, 2026
Bandar Bestari
Klang, Selangor
QAR 1,602 /month
Listed on May 23, 2024
Vista Bayu Apartment, Taman Bayu Perdana
Jalan Batu Unjur 9
QAR 1,557 /month
Listed on December 5, 2025

Taman Sentosa Perdana
Lorong Temenggung 39
QAR 511,635
Listed on October 21, 2024

Taman Lembah Maju
Jalan Maju 2/7
QAR 258,024
Listed on November 21, 2024
Sri Nervillia Apartment (Pangsapuri Sri Nervillia)
Jalan Anggerik Nervillia 31/166, Kota Kemuning
QAR 756 /month
Listed on July 22, 2025
TAMAN PERWIRA, TPG
JALAN WIRA 2,TAMAN PERWIRA, TPG
QAR 4,004 /month
Listed on July 27, 2026
Bandar Putera
Jalan Kebun Nenas 2
QAR 2,225 /month
Listed on August 1, 2026
Laman Impian Bandar Botanic Klang
Bandar Botanic Klang
QAR 1,424 /month
Listed on August 26, 2026
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
QAR 1,335 /month
Listed on September 20, 2026
Taman Sentosa
Jalan Hulubalang 27
QAR 1,068 /month
Listed on September 18, 2026
Persiaran Anggerik Aranda
Persiaran Anggerik Aranda
QAR 1,067,760
Listed on October 14, 2025
Bandar Bukit Tinggi
Lorong Batu Nilam 11
QAR 667,332
Listed on September 2, 2026

Taman Sentosa
Jalan Dato Yusof Shahbudin 1
QAR 416,426
Listed on December 6, 2024
Bandar Botanic
Akasia
QAR 2,491 /month
Listed on July 3, 2026
Asteria Apartment @ Bandar ParkLand
Bandar Parklands Klang
QAR 1,157 /month
Listed on June 15, 2026
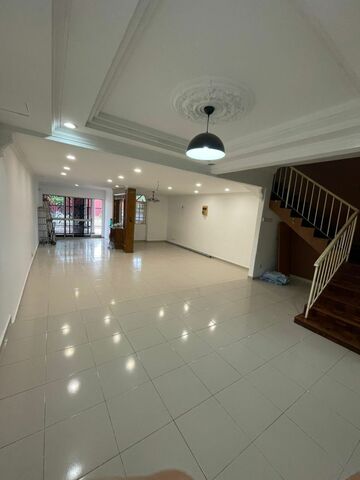
Taman Palm Grove
Leboh Siput
QAR 551,658
Listed on October 30, 2025
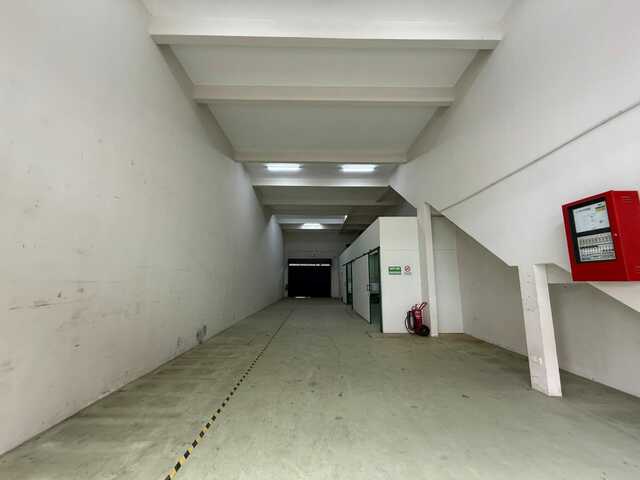
Kesas 32 Industrial Park
Jalan Sungai Jeluh 32/201
QAR 6,851 /month
Listed on April 5, 2026
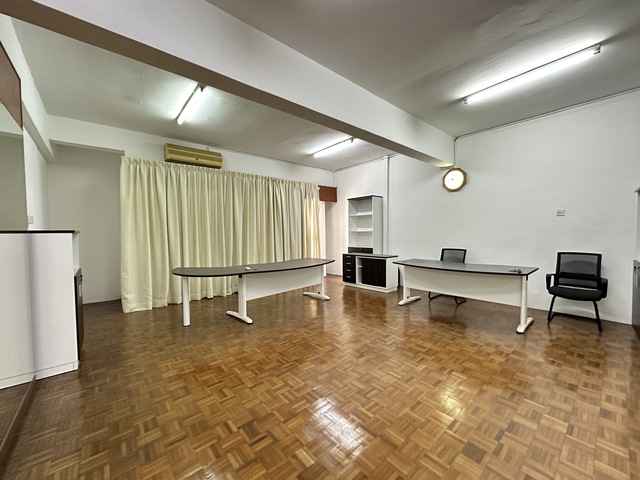
BAYU PERDANA
Jalan Batu Unjur 1
QAR 1,602 /month
Listed on April 5, 2026
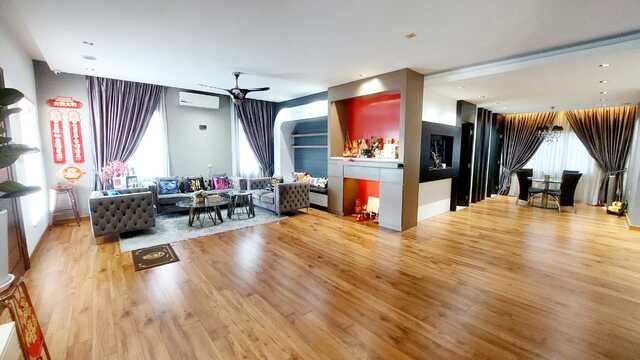
Taman Raja Nong
JALAN RAJA NONG
QAR 800,820
Listed on August 21, 2026

Taman Sentosa
Jalan Dato Abdul Hamid 18
QAR 462,696
Listed on November 22, 2024
Trefoil Service Residence, Setia City
Jalan Setia Dagang AH U13/AH, Setia City
QAR 1,068 /month
Listed on August 13, 2026
BAYU PERDANA
Jalan Batu Unjur 1
QAR 712 /month
Listed on April 5, 2026
Pangsapuri Intan
Jalan Bukit Permai, Taman Bukit Permai
QAR 211,772
Listed on June 24, 2025
Jalan Bunga Pekan Banting
Jalan Bunga Pekan Banting
QAR 3,381 /month
Listed on August 18, 2026
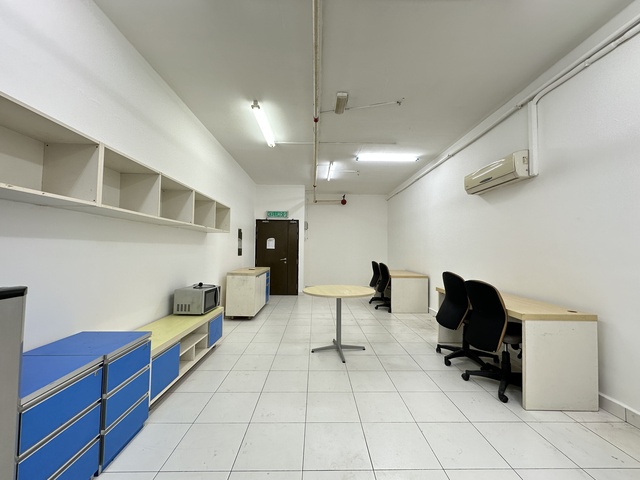
Avenue Crest
Section 22, Batu Tiga, Shah Alam
QAR 934 /month
Listed on April 16, 2026
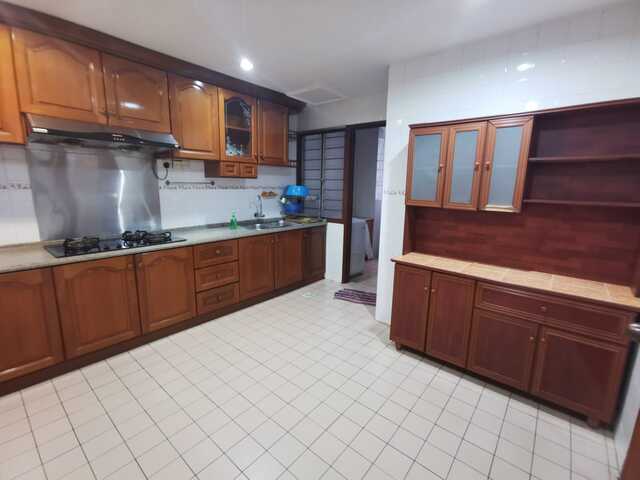
Dynasty Condominium
Jalan Batu Tiga Lama
QAR 1,602 /month
Listed on August 19, 2026
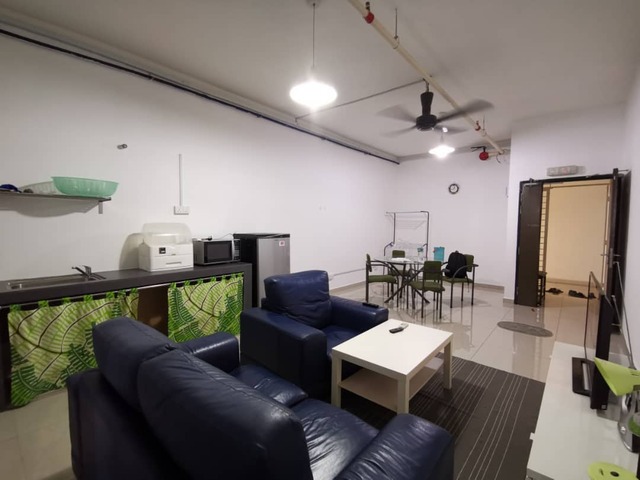
Avenue Crest
Section 22, Batu Tiga
QAR 1,157 /month
Listed on April 6, 2026

Taman Sungai Besi Indah
Jalan Sb Indah 1/5
QAR 354,140
Listed on June 17, 2025
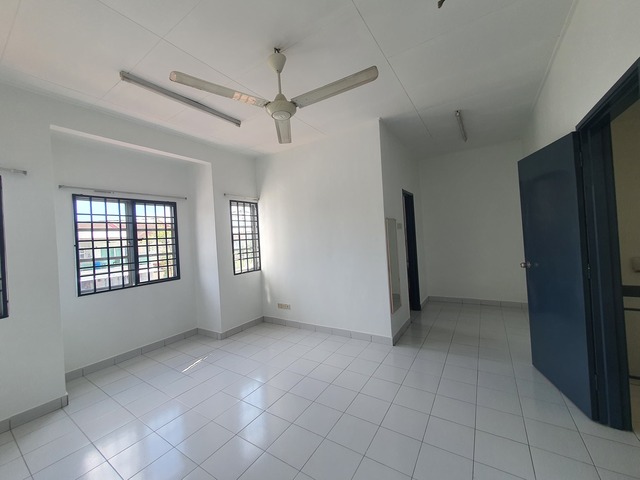
Bandar Puteri Klang
Jalan Kerongsang
QAR 516,084
Listed on March 30, 2026
Bandar Botanic
Persiaran Botanic
QAR 2,669 /month
Listed on October 9, 2026

Bayu Tinggi
Jalan Bayu Tinggi Klang, Selangor
QAR 1,290,210
Listed on April 22, 2025
Bandar Puteri Klang
Jalan Pending
QAR 444,882
Listed on January 19, 2026
Parkhill Residence
Jalan Teknologi 1
QAR 480,492
Listed on March 30, 2026
Endah Villa Condominium
Jalan 2/149B, Taman Sri Endah
QAR 1,424 /month
Listed on August 24, 2026

Saujana Damansara
Desa Riang, 47830, Selangor
QAR 133,470
Listed on June 27, 2024
Bandar Botanic
Jalan Jenaris
QAR 1,049,964
Listed on March 12, 2026
Bangsar Hill Park
13, Lorong Maarof 1, Bangsar, 59000 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
QAR 5,561 /month
Listed on September 30, 2025
Residensi Heliks (Helix2 @ PJ South)
Jalan PJS 5/30, Taman Medan, Kampung Ghandi
QAR 2,180 /month
Listed on September 10, 2026
Gravit8 @ Klang South
Jalan Bayu Laut
QAR 1,602 /month
Listed on August 14, 2026

Impiria Residensi
Lorong Batu Nilam 16A/KS06, Bandar Bukit Tinggi 2
QAR 551,676
Listed on June 10, 2025
Teluk Pulai
Tepi Sungai
QAR 627,309
Listed on September 22, 2025
Ten Kinrara
Jalan BK 5a
QAR 609,513
Listed on July 4, 2025

Trifolis Apartment
Jalan Batu Nilam 36/KS6, 41200, Selangor
QAR 298,083
Listed on April 15, 2025
Vista Lavender Apartment
Bandar Kinrara
QAR 1,602 /month
Listed on August 26, 2026
Impiria Residensi, Bandar Bukit Tinggi 2
Lorong Batu Nilam 16A/KS06
QAR 2,936 /month
Listed on August 13, 2026
Taman Melawis (Taman Heng Luen)
Jalan Emas; Jalan Besi
QAR 489,390
Listed on November 14, 2025
Green Residence
Jalan Sayang 1, Taman Rasa Sayang
QAR 1,780 /month
Listed on April 20, 2026
Bandar Bukit Tinggi 1 Apartment
Jalan Batu Nilam 15
QAR 177,942
Listed on April 21, 2026

Taman Sentosa
Jalan Temenggung 37
QAR 676,248
Listed on November 20, 2024
Taman Selat Damai
Off Jalan Jeti Pandamaran
QAR 1,245 /month
Listed on April 6, 2026

Taman Bayu Perdana
Jalan Batu Unjur
QAR 444,010
Listed on February 25, 2025
Trifolis Apartment
Jalan Batu Nilam 36/KS6
QAR 1,290 /month
Listed on August 2, 2026

Livia @ Bandar Rimbayu
Jalan Fauna 3
QAR 845,310
Listed on October 28, 2024
Golden Villa Apartment
Jln Temenggung 37, Taman Sentosa Perdana
QAR 164,613
Listed on December 5, 2025

AraTre' Residences
Jalan PJU 1a/4a, Ara Damansara, 47301, Selangor
QAR 689,595
Listed on March 4, 2025
Taman Perindustrian Pandamaran
Sobena Jaya Pandamaran
QAR 12,457 /month
Listed on August 14, 2026
Bandar Parklands
Lorong Delima 4
QAR 667,332
Listed on September 4, 2026
La Vista
Jalan Tempua 2, Bandar Puchong Jaya
QAR 400,392
Listed on June 24, 2025
Bandar Bukit Tinggi
Lorong Batu Nilam 11
QAR 532,100
Listed on April 22, 2024
The Havre
Lebuhraya Bukit Jalil
QAR 444,882
Listed on August 29, 2025
Bandar Puteri Klang
Jalan Kerongsang 7
QAR 683,366
Listed on March 31, 2026
AraTre' Residences
Jalan PJU 1a/4a, Ara Damansara, 47301, Selangor
QAR 694,044
Listed on March 24, 2025
BANDAR BOTANIC, KLANG
Jalan Mahogani 1
QAR 5,784 /month
Listed on July 8, 2026
Bandar Putera
Jalan Kebun Nenas
QAR 756,241
Listed on April 16, 2026

Taman Melawis (Taman Heng Luen)
Jalan Loyang; Jalan Emas; Jalan Besi
QAR 444,882
Listed on October 29, 2024
Pangsapuri Kasuarina
Bandar Botanik, Klang
QAR 1,246 /month
Listed on April 23, 2026
NCT Smart Industrial Park
Kuala Langat
QAR 29,808 /month
Listed on August 24, 2026

Taman Sejati 5
Lorong Bendahara
QAR 440,451
Listed on June 10, 2025
Bandar Botanic
Jalan Cassia
QAR 462,696
Listed on March 16, 2026

Kekwa Apartment @ Putra Perdana
Bulatan Putra Perdana, Taman Putra Perdana, 47100, Selangor
QAR 142,368
Listed on March 6, 2025
Central Residence, Sungai Besi
Jalan Sungai Besi
QAR 347,022
Listed on June 19, 2025
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
QAR 1,157 /month
Listed on August 21, 2026
Vista Bayu Apartment, Taman Bayu Perdana
Jalan Batu Unjur 9
QAR 249,144
Listed on January 16, 2026
ARANDA NOVA @ CAMERON SQUARE
A-5-5, THE RETREAT, CAMERON SQUARE@ARANDA NOVA
QAR 352,361
Listed on August 18, 2026
Pangsapuri Kasuarina
Bandar Botanik, Klang
QAR 235,797
Listed on August 18, 2026

Teluk Pulai
Jalan Teluk Pulai
QAR 742,983
Listed on April 8, 2025
Millenium Place @ Millenium Square
Jalan 14/1, Seksyen 14
QAR 444,882
Listed on December 29, 2025
La Vista
Jalan Tempua 2, Bandar Puchong Jaya
QAR 400,410
Listed on June 19, 2025

Riana South
Persiaran Alam Damai, 56000, Kuala Lumpur
QAR 605,064
Listed on May 27, 2025
Taman Sri Jaromas
Jalan 3/14
QAR 790,142
Listed on October 8, 2025
Orchis Apartment, Bandar Parklands
Bandar Parklands
QAR 258,042
Listed on August 24, 2026

Putra Heights
Jalan Putra Bistari
QAR 692,264
Listed on April 24, 2025
Waltz Residences @ Paradigm Garden City
Jalan Awan Besar
QAR 702,942
Listed on November 27, 2025
Bandar Puteri Klang
Lorong Gelang
QAR 523,202
Listed on January 8, 2026

GEO Bukit Rimau
Jalan Sungai Burung
QAR 2,225 /month
Listed on March 19, 2025
Prima Ria
Jalan Dutamas Raya
QAR 373,698
Listed on November 3, 2025
Edelweiss @ Tropicana Gardens
Kota Damansara
QAR 694,026
Listed on September 18, 2026
Taman Millenium, Sentosa
Jalan Hulubalang 37a
QAR 115,656
Listed on December 5, 2025
TRIO by Setia
Bukit Tinggi Klang
QAR 1,691 /month
Listed on October 8, 2026
Prima Bayu
Jalan Batu Unjur 9
QAR 302,514
Listed on April 22, 2026

Pangsapuri Palma
Jalan Palma Raja 3/KS6, Bandar Botanic, Klang, 41200, Selangor
QAR 137,919
Listed on August 29, 2024
Laman Impian Bandar Botanic
Bandar Botanic Klang
QAR 329,226
Listed on September 4, 2026
Taman Klang Indah
Jalan Samarinda
QAR 1,424 /month
Listed on August 2, 2026
Laman Impian @ Bandar Botanic
Botanic Klang
QAR 293,545
Listed on August 18, 2026
Bandar Bukit Tinggi
Lorong Batu Nilam 6
QAR 1,691 /month
Listed on April 29, 2026
Bandar Parklands
Jalan Delima 4
QAR 621,970
Listed on July 20, 2026

Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur, 41200, Selangor
QAR 229,568
Listed on May 20, 2025
Robin @ Bandar Rimbayu
Jalan Fauna 3
QAR 542,778
Listed on August 18, 2026
Taman Sri Jaromas
Jalan 3/10
QAR 489,390
Listed on October 8, 2025
Taman Klang Indah
Lorong Samarinda 11F
QAR 578,352
Listed on April 5, 2024
Taman Telok
Jalan Dendang
QAR 391,494
Listed on February 3, 2026
Taman Sri Andalas
Jalan Sri Damak
QAR 1,602 /month
Listed on March 25, 2024
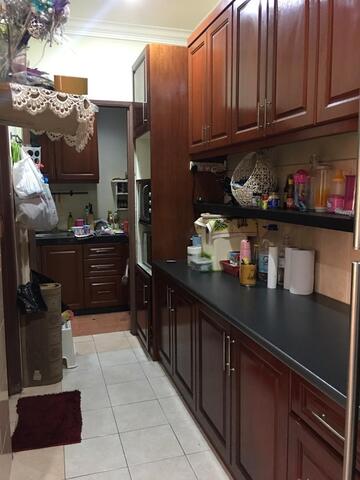
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
QAR 311,430
Listed on August 17, 2026
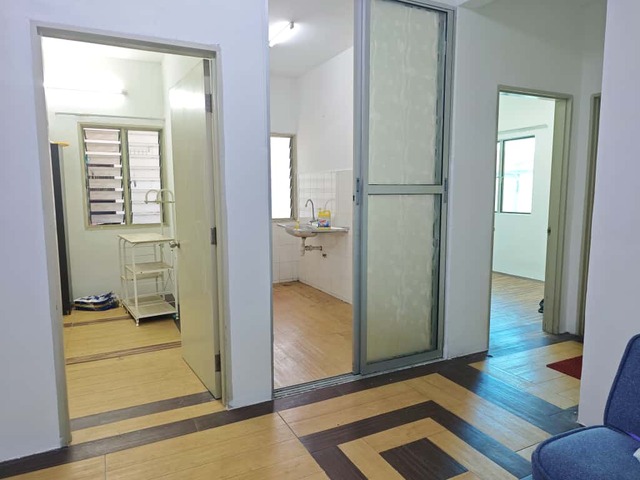
Pangsapuri Akasia, Bandar Botanic
Persiaran Kasuarina
QAR 204,654
Listed on March 12, 2026
Our newly launched projects
Discover the real estate properties in and around Selangor, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Large land area
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from QAR 12,898,114
Listed on January 23, 2026
 Varied built-up sizes
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from QAR 1,071,141
Listed on January 23, 2026
 Located in Simpang Ampat
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from QAR 4,462,347
Listed on January 23, 2026
 Spacious land area
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from QAR 995,508
Listed on January 23, 2026
 Larger built-up area
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from QAR 727,856
Listed on January 23, 2026
 Large land area
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from QAR 489,390
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
8 Oct, 2026
Foreigner’s Guide To Buying Property In Malaysia
Yes, foreigners can buy a home in Malaysia, and own it outright in their own name. In most states you need to spend at least RM1 million, get state consent, and pay 8% stamp duty on the transfer. In return, you get one of the most open property markets in Asia. No Singapore-style 60% surcharge. No 49% building quota like Thailand. No requirement to hold a visa before you buy. This guide covers what foreigners can and cannot buy, the 2026 minimum prices by state, what the purchase really costs, the steps from offer to keys, and where MM2H fits in. TL;DR Foreigners can buy residential property in Malaysia, freehold or leasehold, registered in their own name. Every purchase needs state authority consent. Minimum prices are set by each state. Kuala Lumpur is RM1,000,000. Selangor is RM2,000,000. Penang Island is RM1,000,000 for condos and RM3,000,000 for landed homes. Some states start at RM500,000. Foreigners cannot buy low-cost or medium-cost housing, Bumiputera quota units, or Malay Reserved Land. From 1 January 2026, foreign buyers pay a flat 8% stamp duty on the transfer of residential property. On a RM1,000,000 home that is RM80,000, against RM24,000 for a Malaysian. Malaysian banks typically lend foreigners 60% to 70% of the property value. Selling within five years attracts 30% Real Property Gains Tax for foreigners, falling to 10% from year six. MM2H is not required to buy, but it gives a renewable long-stay pass. Silver starts at a USD150,000 fixed deposit and a RM600,000 home, subject to the state's own minimum price. In this guideCan Foreigners Buy Property in Malaysia?How Much Do Foreigners Need to Spend? Minimum Prices by StateHow to Buy a Home in Malaysia as a Foreigner: 7 StepsHow Much Does It Really Cost a Foreigner to Buy?Should You Buy Through MM2H?Why Foreigners Choose Malaysia: Experts and Our TakeFAQ Can Foreigners Buy Property in Malaysia? Yes. A foreigner can buy a condo, a serviced apartment or, in many states, a landed house, and hold the title in their own name. Freehold is available too. Foreign buyers have certainty of ownership as their names are registered as the owners of the properties. Datuk Peter S K Yap, partner, Amin, Yap & Co, speaking to EdgeProp, 28 July 2026 What foreigners cannot buy Low-cost and medium-cost housing, as defined by each state Units allocated under the Bumiputera quota in a development Malay Reserved Land Properties below the state's minimum price for foreigners Agricultural land, and in some states, auctioned property or individual landed titles Buying land rather than a home has its own rules. See our guide on whether foreigners can buy land in Malaysia. How Malaysia compares with its neighbours Rule for foreign buyersMalaysiaSingaporeThailandOwn a condo in your own nameYesYesYes, within a 49% foreign quota per buildingOwn landed propertyYes in most states, with consent and higher minimumsGenerally no, without government approvalNo freehold land ownershipExtra purchase tax8% flat stamp duty on residential transfers60% Additional Buyer's Stamp DutyStandard transfer feesLong-stay visa linked to propertyMM2H, from USD150,000 fixed depositNoSeparate visa schemes Of the three, Malaysia is the most open to foreigners owning a landed home, with published price thresholds by state. Considering Thailand too? Our guide to buying in Thailand covers its rules. How Much Do Foreigners Need to Spend? Minimum Prices by State Each state sets its own minimum purchase price for foreigners. It is the first number to check, because it decides which homes you can even look at. StateLanded (RM)Strata, condo (RM)Kuala Lumpur1,000,0001,000,000Putrajaya and Labuan1,000,0001,000,000Selangor (zones 1 to 3)2,000,0002,000,000Johor2,000,000 (designated international zones)1,000,000Penang Island3,000,0001,000,000Penang mainland1,000,000500,000Melaka1,000,000500,000Negeri Sembilan1,000,000600,000Sabah1,000,000600,000Kedah600,000 (1,000,000 in Langkawi)600,000Perak1,000,0001,000,000Perlis500,000500,000Sarawak500,000 to 600,000, by division500,000 to 600,000, by division Source: iProperty foreign buyer guide, 2026. Thresholds change and some apply only to certain zones or title types. Meeting the minimum does not guarantee state consent. Confirm with your lawyer before you commit. The spread is wide. A foreigner can buy a condo in Melaka or mainland Penang for half of what Kuala Lumpur requires, and a quarter of Selangor's entry point. Not every buyer realises this. Datuk Ho Hon Sang, the former president of the Real Estate and Housing Developers' Association (Rehda), put it simply to EdgeProp in July 2026: "There are still certain states with lower minimum thresholds." Already over RM1 million in KL? Browse completed homes that meet the foreign buyer threshold, ready to view. Browse subsale homes → How to Buy a Home in Malaysia as a Foreigner: 7 Steps The process mirrors what Malaysians follow, with one extra gate: state consent. A subsale purchase usually takes three to six months from signing to completion. Step 1: Confirm the state minimum and restrictions Before viewing anything, check the threshold for that state and property type, and confirm the unit is not a Bumiputera lot or low or medium-cost housing. Your agent and lawyer can verify this against the title. Step 2: Appoint a Malaysian lawyer Your lawyer runs the title search, drafts the Sale and Purchase Agreement (SPA), applies for state consent and handles stamp duty. Choose one before you pay a deposit. Most are not aware of the detailed costing and timelines. Jeremiah R Gurusamy, partner, Ramesh Dipendra Jeremiah Law, on foreign buyers, EdgeProp, 28 July 2026 Step 3: Arrange financing, if you need it Malaysian banks do lend to foreigners, typically 60% to 70% of the property value. Expect to show overseas income documents, tax returns and bank statements. Some banks lend more for strong profiles or MM2H participants. Many foreign buyers secure an approval in principle before making an offer. Estimate your instalment below. Estimates for guidance only. Rates and margins for foreign borrowers vary by bank. Step 4: Make an offer and pay the earnest deposit For a subsale, you sign a letter of offer and pay an earnest deposit of usually 2% to 3%, held by the agent or lawyer as stakeholder. For a new launch, the developer collects 10% when the SPA is signed. Step 5: Sign the SPA and pay the balance deposit You sign the SPA and top up the deposit to 10% of the price. The SPA should be made conditional on state consent, so your deposit is protected if consent is refused. Step 6: Obtain state authority consent Your lawyer submits the application to the state land office. Approval can take one to two months or longer, depending on the state, and some states charge a fee or levy. This is the step that most often stretches the timeline. Step 7: Pay stamp duty and the balance, then complete Once consent is granted, the 8% stamp duty on the transfer is paid, your bank releases the loan, and the balance goes to the seller. The title is then registered in your name at the land office. How Much Does It Really Cost a Foreigner to Buy? The price is only the start. Here is what a foreigner pays on a RM1,000,000 KL condo in 2026, compared with a Malaysian buyer. Cost itemForeign buyer (RM)Malaysian buyer (RM)Stamp duty on transfer80,000 (8% flat)24,000 (1% to 3% tiers)Legal fee on the SPA11,25011,2508% service tax on legal fee900900State consent fee or levyVaries by stateNot requiredExtra costs, cash purchase92,150 (about 9.2%)36,150 (about 3.6%) Legal fees follow the Solicitors' Remuneration Order 2023 scale (1.25% on the first RM500,000, 1% on the next), before disbursements. Malaysian figure assumes no first-time buyer exemption. Calculated by IQI, not a quote. With state charges and disbursements, lawyers put the all-in acquisition cost for a foreign cash buyer at about 10% to 11% of the price. Borrowing adds more. With a 70% loan of RM700,000, add about RM8,910 in legal fees and service tax on the loan agreement and RM3,500 in loan stamp duty. Your cash outlay before keys becomes roughly RM404,560, including the RM300,000 down payment. The 8% rate drew concern when it was announced. Rehda's then president, Datuk Ho Hon Sang, told The Sun in October 2025 that it "may be seen as a deterrent for investors seeking to establish a base in Malaysia". What you pay when you sell Held forRPGT, foreignerRPGT, Malaysian citizenTax on a RM200,000 gain, foreignerYears 1 to 530%30% to 15%RM60,000Year 6 onwards10%0%RM20,000 A foreign owner never reaches 0%, however long the home is held. If you plan to rent it out meanwhile, our rental income tax guide explains how foreign landlords are taxed. Should You Buy Through MM2H? You do not need MM2H to buy a home in Malaysia. But buying a home does not give you the right to live here. Malaysia My Second Home (MM2H) does, with a renewable long-stay pass for you and your dependants. Under MM2H, you must buy a home after approval and hold it for 10 years, unless you upgrade to a more valuable one. The state's foreign buyer minimum still applies, so a Silver participant buying in KL still needs to spend RM1,000,000. MM2H tierFixed depositPass termMinimum home priceMinimum ageSilverUSD150,0005 years, renewableRM600,00025GoldUSD500,00015 years, renewableRM1,000,00025PlatinumUSD1,000,00020 years, renewableRM2,000,00025SEZ/SFZ (Forest City, Johor)USD65,000 (age 21 to 49) or USD32,000 (age 50+)10 years, renewableSet for the development21 Source: Ministry of Tourism, Arts and Culture (MOTAC), via IQI's MM2H series. Up to 50% of the fixed deposit can be withdrawn after approval for property, education or medical costs. Participants under 50 must spend 90 days a year in Malaysia. Check mm2h.gov.my for the latest terms. MM2H has never offered citizenship or permanent residency. It is a long-stay pass, and it is booming. Juwai IQI's Kashif Ansari told Malay Mail in September 2026: "Some think that MM2H is losing its appeal, but the reality is quite the opposite." He noted that only 1,900 applicants were approved across 2021, 2022 and 2023 combined, while "in 2025, more than 3,000 visas and 9,000 participants obtained approval." Where you come from shapes the decision. Read our market-by-market guides: MM2H Europe: is living in Malaysia worth it for Europeans in 2026? MM2H UAE: is living in Malaysia better than Dubai? MM2H China: are Chinese buyers taking over Malaysian property? Why Foreigners Choose Malaysia: Experts and Our Take Foreigners account for only about 1% of residential transactions by volume, according to NAPIC's Property Market Report 2025. But the buyers who do come are changing. Chinese citizens were the most active group in the first half of 2025, investing RM835 million in residential property, about 51% of the foreign total. More of them are buying to live, not to flip. Malaysia offers good schools, an attractive lifestyle, an admirable culture, and a predictable path to residency through MM2H. Kashif Ansari, Co-Founder and Group CEO, Juwai IQI, Malay Mail, 1 September 2026 Ansari has also described Malaysia as offering the comfort and quality wealthy buyers want "without the visa headaches, capital controls or high price tags they face elsewhere" (Malay Mail, 15 April 2025). The 8% stamp duty has made demand more selective, not made it vanish. Foreign demand is not disappearing, it is becoming more disciplined. Adrian Yeoh, executive director, Knight Frank Property Hub, EdgeProp, 28 July 2026 From the authorI will be honest. I think Malaysia is one of the best places in Asia for a foreigner who wants a relaxed life at a price that still makes sense.Life here moves at a gentler pace. You can live in a city with good hospitals, international schools and an airport that connects you to the region, and still be an hour from a beach, a rainforest or the cool air of the highlands.Then there is the culture. Malay, Chinese, Indian and indigenous communities live side by side, and you feel it every day. In one day you can have nasi lemak for breakfast, dim sum for lunch and banana leaf rice for dinner, and none of it will cost you much.The history is everywhere too. Walk the shophouse streets of George Town or Melaka, both UNESCO World Heritage cities, and you are walking through centuries of trade between East and West.It is not perfect. KL traffic tests your patience and the humidity takes getting used to. But for value, variety and the way people welcome you, there is so much here worth exploring, and owning a home is the best way to do it properly. FAQ Can a foreigner buy a house in Malaysia? Yes. Foreigners can buy residential property in Malaysia, including freehold homes, and register it in their own name. Every purchase needs state authority consent, must meet the state's minimum price for foreigners, and cannot be low-cost or medium-cost housing, a Bumiputera quota unit or Malay Reserved Land. What is the minimum price a foreigner can pay for property in Malaysia? It depends on the state. Kuala Lumpur sets RM1,000,000, Selangor RM2,000,000, and Penang Island RM1,000,000 for condos and RM3,000,000 for landed homes. Some states are lower, with strata homes from RM500,000 in Melaka, mainland Penang and Perlis. Thresholds change, so confirm with a lawyer before buying. How much stamp duty do foreigners pay in Malaysia in 2026? From 1 January 2026, non-citizens who are not permanent residents, and foreign companies, pay a flat 8% stamp duty on the transfer of residential property. On a RM1,000,000 home that is RM80,000. A Malaysian buyer pays tiered rates of 1% to 4%, or RM24,000 on the same home. Can foreigners get a home loan in Malaysia? Yes. Malaysian banks lend to foreigners, typically 60% to 70% of the property value, depending on the bank, the buyer's income and the property. Expect to provide overseas income documents, tax returns and bank statements. Do I need MM2H to buy property in Malaysia? No. Any foreigner can buy property that meets the state's rules. MM2H is a separate long-stay pass programme. It requires participants to buy a home, with minimum prices of RM600,000 for Silver, RM1,000,000 for Gold and RM2,000,000 for Platinum, and the state's own foreign buyer minimum still applies. Does buying property in Malaysia give me residency? No. Owning property does not give you a visa, permanent residency or citizenship. To live in Malaysia long term, you need a pass such as MM2H, which is renewable but does not lead to citizenship or permanent residency. How long does it take for a foreigner to buy property in Malaysia? A subsale purchase usually takes three to six months from signing the Sale and Purchase Agreement to completion. State authority consent alone can take one to two months or longer, depending on the state. Buying from overseas? Make every step count. From finding the right property to getting the keys, an IQI agent can guide you through the process. Leave your details and speak with a local IQI agent today. [custom_blog_form] Liked what you read? Read related articles here: MM2H Europe: Is Living in Malaysia Worth It for Europeans in 2026? First-Time Home Buyer Guide Malaysia 2026: From Savings to Keys 5 Simple Steps To Buy Land in Malaysia Can Foreigners Buy Land in Malaysia? Buying Property in Malaysia: A Step-by-Step Guide (2026) Sources EdgeProp, Malaysia remains one of Asia's most accessible property markets for foreign buyers in 2026, 28 July 2026 Malay Mail, Juwai IQI: Malaysia among top destinations for Chinese property buyers, 1 September 2026 Malay Mail, Malaysia said to be fourth top choice for China's ultra-rich homebuyers, 15 April 2025 The Sun, Rehda welcomes housing initiatives, cautious on higher stamp duty for foreigners, 11 October 2025 Skrine, Proposed amendments to the Stamp Act, 24 November 2025 iProperty, Foreigners buying property in Malaysia: complete guide, 2026 Global Law Experts, A 2025 to 2026 guide to buying residential property in Malaysia for foreigners, updated 17 April 2026 MOTAC, MM2H guidelines, updated 10 February 2026 Conventus Law, The Solicitors' Remuneration Order 2023
8 Oct, 2026
Pakistan Real Estate Market Insights 2026
TL;DRPakistan’s real estate market in 2026 offers strong residential demand and potentially higher returns from selected commercial properties. Annual property turnover is estimated at PKR 7.1 trillion, or 6.7% of GDP, while the national average gross apartment rental yield was 6.53% in Q3 2025. In Karachi, DHA detached houses yield about 3.36%–5.50%, compared with 8.00%–13.00% for Grade-A commercial properties along Shahrah-e-Faisal, making location and property type key factors for investors. A plot in Karachi, an apartment in Islamabad and a shop in Lahore can all sit under the Pakistan real estate label, but they behave like cousins at a wedding: related, not identical. Residential property follows household demand, affordability and rent; commercial property depends more on business demand, footfall and occupancy. This guide compares both sides of the market using concrete 2026 figures, not one-size-fits-all hype. Key Takeaways The Karachi property market recorded about 16.6% year-on-year house-price growth in June 2026. The national gross rental yield in Pakistan, on average, for apartments stood at 6.53% in Q3 2025. In February 2026, average house prices stood at approximately PKR 83.6 million in Islamabad, PKR 77.7 million in Karachi, and PKR 52.1 million in Lahore. In the Pakistan commercial real estate market, Grade-A commercial properties along Shahrah-e-Faisal can generate gross yields of 8.00% to 13.00%, compared with 3.36% to 5.50% for detached houses in DHA Karachi. Pakistan’s residential mortgage market was estimated at only about 0.5% of GDP in 2025, making limited access to financing a major constraint on the Pakistan housing market. Get Updated on Pakistan Market1. What makes Pakistan an attractive real estate Investment Destination?2. How is Pakistan's economy performing right now?3. What is happening in Pakistan's property market in 20264. How much can you earn from property investment in Pakistan?5. Where are the best places to invest in Pakistan right now?6. What do experts say about the market?7. Can foreigners buy property in Pakistan? What are the rules?8. Frequently Asked Questions (FAQs) 1. What makes Pakistan an attractive real estate Investment Destination? Pakistan’s main attraction is a large housing market, ongoing household formation, undersupplied urban housing, and commercial demand driven by expanding cities. The opportunity is not simply “property prices will rise.” Structural changes are driving residential demand and commercial activity and can last much longer than a speculative cycle. Global Property Guide reported a population of 241.5 million in the 2023 census and 38.34 million households, while its PMRC-based analysis estimated roughly 36.24 million residential units nationally. The same analysis calculated a basic shortage of about 2.10 million units under a one-household-per-unit methodology. That shortage should not be confused with every larger housing shortage headline in Pakistan. Milkiyat’s coverage of National Housing Policy 2025 cited an estimated shortage of around 13 million units, but also noted that the calculation method was not disclosed. The difference matters because one figure measures a basic unit shortfall while broader estimates can include affordability, quality and other housing deficiencies. Residential demand also has a strong overseas link. Dawn reported that Pakistan received US$41.6 billion in workers’ remittances in FY2025-26 and that households receiving foreign remittances accounted for about 29% of measured construction and home-improvement spending despite representing fewer than one in ten households. That creates a natural base for the Pakistan property market for overseas investors, particularly in new homes, apartments and managed residential projects. The commercial side benefits differently from urbanization in Pakistan's real estate trends. More occupied housing creates customers for shops, offices, services and mixed-use projects. Commercial property therefore works best where residential density becomes real occupancy, not merely where large numbers of plots have been sold on paper. For investors, that distinction is crucial. Residential property can benefit simply from a large pool of households needing somewhere to live. Retail, office and mixed-use assets need those households to live, work and spend within the catchment before commercial rents become sustainable. 2. How is Pakistan's economy performing right now? Pakistan’s economy provides a more stable backdrop than during its most volatile recent periods, but Pakistan real estate investment is still operating in a relatively expensive financing environment. That affects residential buyers who need mortgages and commercial investors who rely on leverage or compare property yields with financial returns. IQI Global listed the policy rate at 11.50%, inflation at 11.70%, foreign-exchange reserves at US$22.04 billion, and PKR/USD at 278.16. Economic indicatorReported figureResidential impactCommercial impactPolicy rate11.50%Mortgage affordability remains difficultDebt-funded acquisitions face a higher hurdle rateInflation11.70%Construction and household budgets remain sensitiveFit-out, replacement and operating costs matter moreForex reservesUS$22.04BGreater macro stability can help buyer confidenceStability helps long-horizon business planningPKR/USD278.16Foreign-currency buyers evaluate local prices differentlyOverseas capital can compare Pakistan yields with other markets Source: IQI Global The practical effect of the housing market rate environment is simple: a property can look affordable in cash terms while being much less affordable when financed. Global Property Guide estimated residential mortgages at roughly 0.5% of GDP in 2025, so formal mortgage lending remains small relative to the size of the property economy. For commercial property, higher borrowing costs raise the return an investor needs to justify using debt. IQI Global described KIBOR plus roughly 150–300 basis points as a factor limiting leveraged and speculative buying. This favors buyers with patient capital. In residential markets, that means focusing more on actual rental demand and delivery quality. In commercial markets, it means paying closer attention to rental yield, vacancy risk, and whether a business tenant can realistically support the asking rent. 3. What is happening in Pakistan's property market in 2026 The Pakistan real estate market outlook for 2026 is positive in some segments but highly uneven. Residential prices are rising in several markets, apartment demand is growing in major cities, and completed projects are attracting attention. Commercial opportunities are increasingly tied to occupied catchments, transit, retail activity, and mixed-use development rather than speculative land alone. Business Recorder reported that residential prices in major cities had risen by an estimated 10%–15% over the preceding weeks as investor demand strengthened. That was a short-period market estimate rather than a national price index, so it should not be treated as a guaranteed annual growth rate. a. How are residential prices and yields comparing by city? Global Property Guide’s February and Q3 datasets show why Pakistan property prices need to be compared city by city rather than through one national average. CityAvg. house price, Feb. 2026Avg. apartment price, Feb. 2026Avg. gross apartment yield, Q3 2025IslamabadPKR 83.6MPKR 25.5M7.01%KarachiPKR 77.7MPKR 27.0M6.50%LahorePKR 52.1MPKR 23.8M5.87%RawalpindiPKR 35.0MPKR 12.1M6.73% Source: Global Property Guide The table shows why Islamabad property market pricing cannot be read the same way as Lahore or Rawalpindi. Islamabad had the highest average house price among these cities, while its apartment yield average was also the strongest of the four in the Q3 2025 dataset. The Karachi property market offers another pattern. Apartment prices were the highest of the four cities in February 2026, while its commercial micro-markets show much wider income potential depending on property type. B. What is happening in commercial property? IQI Global 2026 Karachi analysis shows the spread clearly. Grade-A commercial property on Shahrah-e-Faisal was shown at 8.00%–13.00% gross rental yields, while residential yields ranged from 3.36%–5.50% for DHA detached houses, 4.00%–6.50% for Clifton luxury apartments and 4.50%–6.00% for Bahria Town Karachi villas. Karachi segmentProperty typeGross yield rangeShahrah-e-FaisalGrade-A commercial8.00%–13.00%Gulshan/JauharMid-rise homes6.50%–8.20%Scheme 33Suburban homes5.50%–7.20%CliftonLuxury apartments4.00%–6.50%Bahria Town KarachiVillas4.50%–6.00%DHA KarachiDetached houses3.36%–5.50% Source: IQI Global This does not mean Pakistan's commercial real estate market assets automatically beat homes. A commercial shop with weak footfall can sit empty longer than a well-priced apartment. The higher yield is compensation for factors such as vacancy, tenant concentration, and location risk. These properties look attractive, but they need your first step. Let us guide you on this Pakistan property-buying journey! Approach IQI Now! C. Why are high-rise and mixed-use projects gaining attention? Higher land values and denser cities make high-rise apartment developments in Pakistan a practical response to urban growth. Apartments also suit buyers who want security, amenities, and easier property management, especially when they live abroad. For commercial investors, mixed-use developments in Pakistan can concentrate residents, offices, and retail demand in one location. Their success still depends on real occupancy. A glossy ground-floor retail plan is not the same thing as customers walking past the door every afternoon. A current Grade A office space Pakistan occupancy figure for Islamabad or Lahore is not established here, so no office-occupancy percentage is presented. The commercial analysis therefore focuses on property types for which usable 2026 pricing, yield or market evidence is available. 4. How much can you earn from property investment in Pakistan? Returns from property investment come from two places: income while you own the property and any capital gain when you sell it. Residential and commercial property can provide both, but the balance is different. For residential investors, Global Property Guide recorded national apartment gross yields between 3.16% and 12.9% in Q3 2025, with a national average of 6.53%. For commercial investors, UnionDevelopers described 6%–10% gross yields as a typical benchmark for established commercial real estate locations. That range is broadly consistent with IQI Global’s stronger Karachi commercial examples, although individual properties can perform very differently. A useful calculation is straightforward. UnionDevelopers used a PKR 15 million purchase generating PKR 1.2 million in annual rent as an example of an 8% gross rental yield. PKR 1.2 million annual rent ÷ PKR 15 million purchase price = 8% gross yield. Gross yield is not your take-home return. Residential owners may face maintenance, vacancy, and management costs; commercial property owners may also face longer vacancy periods, fit-out issues, and tenant-specific expenses. Purchase taxes, transfer costs, and eventual selling costs further reduce total returns. Capital appreciation can materially change the picture. IQI Global put Clifton residential pricing at PKR 15.6 crore with 16% year-on-year appreciation. The same IQI Global snapshot showed net yields for DHA Phase 8 commercial property at 11%–13%. These numbers show why “Which is better, residential or commercial?” has no universal answer. Residential property typically offers a larger pool of occupiers and buyers, while well-located commercial assets can generate more income. The right comparison is net return after vacancy, expenses, taxes, and financing, not the biggest percentage in a sales brochure. 5. Where are the best places to invest in Pakistan right now? The best cities for real estate investment in Pakistan 2026 depend on whether the investor wants rental income, capital preservation, active value creation, or a longer development play. Islamabad, Karachi, Lahore, and Rawalpindi each offer a different mix. a. Islamabad: premium residential pricing and planned growth Islamabad suits investors who want exposure to apartments in Pakistan and established residential demand in a planned urban environment. Global Property Guide recorded an average house price of PKR 83.6 million and an apartment price of PKR 25.5 million in February 2026, with an average apartment gross yield of 7.01% in Q3 2025. For commercial property, Islamabad’s growth case is more closely tied to mixed-use development, offices, retail and the expansion of populated residential communities. Investors should distinguish a building with functioning tenants from an off-plan project whose future footfall exists only in a projection. B. Karachi: scale plus strong commercial yield pockets Karachi offers one of Pakistan's clearest residential-versus-commercial contrasts in the property market. Global Property Guide recorded average February 2026 prices of PKR 77.7 million for houses and PKR 27 million for apartments. On the retail real estate market and broader commercial side, yield depends heavily on the business corridor. IQI Global put Shahrah-e-Faisal Grade-A commercial at 8%–13% gross yield while several residential segments sat below that range. If you are interested in Karachi property, approach our team now for more information! Approach IQI Now! C. Lahore: deep residential demand and an active commercial market Lahore remains a major property market for homebuyers and investors alike. Global Property Guide recorded average February 2026 prices of PKR 52.1 million for houses and PKR 23.8 million for apartments. Commercial investors in Lahore need to look beyond the word “commercial” on a site plan. Retail property performance in Pakistan depends on actual nearby residents, road visibility, parking, utilities, and commercial-use approval. The same logic applies to offices: businesses pay for accessibility and usable space, not simply a prestigious project name. D. Rawalpindi: lower residential entry prices with urban-growth potential Rawalpindi had a lower average residential property entry point than Islamabad in Global Property Guide’s February 2026 dataset: PKR 35 million for houses and PKR 12.1 million for apartments. Its Q3 2025 average apartment gross yield was 6.73%. The commercial plots in Pakistan case depends on development becoming an occupied catchment. Road projects and new communities may improve accessibility, but a commercial asset still needs businesses and customers before theoretical appreciation turns into usable income. CityResidential caseCommercial caseBest suited toIslamabadPremium pricing, strong apartment yieldsMixed-use, retail and office demand as communities densifyStability and managed residential assetsKarachiLarge market with varied residential segmentsStrong yield pockets in established commercial corridorsIncome-focused investors comfortable with micro-market differencesLahoreBroad residential choice and apartment growthRetail, commercial plots and mixed-use opportunitiesInvestors seeking a deep local marketRawalpindiLower average entry prices than IslamabadGrowth linked to populated new corridorsBuyers balancing entry cost and longer-term expansion The practical lesson is that capital appreciation in Pakistan property decisions should start with the micro-market. A strong city cannot rescue a weak building, and a fashionable housing scheme cannot guarantee a profitable shop. 6. What do experts say about the market? Junaid Hamid, Head of lQl Karachi Pakistan Junaid Hamid, Head of IQI Karachi Pakistan, highlighted an 11.50% policy rate, 11.70% inflation, US$22.04 billion in foreign-exchange reserves and an exchange rate of PKR 278.16 per US dollar. For both residential property and commercial assets, He describes a market where macro stability has improved, but capital remains expensive. He also put the citywide gross residential yield at 6.67%, while Grade-A Shahrah-e-Faisal commercial property was shown at 8%–13%. The gap supports a value-led approach: compare actual income by asset type instead of assuming all Pakistan property offers the same return. Gohar Ali Khan of Business Recorder reported that Pakistan property prices in major cities rose by an estimated 10%–15% over the preceding weeks. That points to stronger sentiment, but a short-term jump should not be extrapolated into a multi-year forecast for either residential or commercial assets. Delivery quality is another recurring issue in Pakistan real estate investment. Aqib H Shah, Chief Commercial Officer of One Homes, said after completion of its Lahore residential project: “If it can be done in New York, London or Dubai, it can be done in Pakistan.” For investors, the takeaway is broader than luxury housing: developer execution matters as much for an apartment tower as for a retail or mixed-use project. The combined view is less exciting than a “prices only go up” headline, which is probably a good thing. Demand in Pakistan's residential real estate market is substantial, and commercial yields can be compelling in the right location, but financing costs, documentation, and project quality still separate investable assets from speculative ones. 7. Can foreigners buy property in Pakistan? What are the rules? Foreign nationals working or residing in Pakistan can buy or rent property, but foreign property ownership transactions in Pakistan require specific legal formalities involving the Board of Investment and the Trade Development Authority of Pakistan. That statement should not be stretched into “every foreigner can freely buy every property.” The exact approval path can vary, so anyone buying residential property should verify the title, transferability, project approval, taxes, and any applicable authority requirements before paying a deposit. A foreign buyer considering commercial property should perform the same ownership checks and also confirm lawful commercial land use. A shop, office, or commercial plot is not safe merely because it is marketed for business use. For either segment, a practical Pakistan property due diligence guide starts with six checks: ownership record, registry or title, project or land-use approval, NOC status where applicable, outstanding dues, and litigation or encumbrances. Developer delivery history matters particularly for off-plan residential towers and mixed-use commercial developments. Current rules for using a Roshan Digital Account real estate route are not established here, so no claim is made about whether a specific RDA structure can fund a residential or commercial purchase. Likewise, no current minimum investment is stated for a Pakistan long-term residency program. Foreign buyers should use a qualified property lawyer and tax adviser before completing a transaction. The same caution applies to overseas Pakistanis: familiarity with the country does not eliminate risks and returns related to title, approvals, payment records, or project delivery. Thinking about buying property in Pakistan? Leave your worries behind and let IQI guide you step by step toward owning your dream home! Approach IQI Now! Pakistan is not one property market but a collection of residential and commercial property micro-markets. The 2026 opportunity is strongest where real demand, legal clarity, infrastructure, and realistic yields overlap. Residential assets offer depth and housing-led demand; commercial assets can offer higher income in the right catchment. Investors should compare city, asset type, financing cost and exit liquidity before treating any headline return as a forecast. 8. Frequently Asked Questions (FAQs) a. What is the outlook for Pakistan's real estate market in 2026? The forecast for Pakistan's real estate market is constructive but uneven. Residential demand remains supported by housing needs and urban growth, while commercial returns depend more heavily on tenant demand and location. Business Recorder reported an estimated 10%–15% residential price increase over several weeks in major cities, but that short-period figure is not a nationwide annual forecast. b. What is Pakistan's average gross rental yield? Global Property Guide calculated a 6.53% national average rental yield for apartments in Pakistan in Q3 2025, with individual properties ranging from 3.16% to 12.9%. Commercial yields can be higher in strong business locations, but the range depends heavily on vacancy and tenant demand. c. Which city in Pakistan has the best residential rental yield? Among Karachi, Lahore, Islamabad and Rawalpindi, Global Property Guide recorded Islamabad’s Q3 2025 average apartment rental yield at 7.01%, compared with 6.73% in Rawalpindi, 6.50% in Karachi and 5.87% in Lahore. This comparison applies to apartments, not every residential or commercial asset in those cities. d. Which is better in Pakistan, residential or commercial property? Residential vs commercial property investment in Pakistan depends on the goal. Residential property generally suits investors who prioritize a broad occupier market and simpler resale, while well-positioned commercial assets can produce higher rental income but expose the owner to greater location, vacancy, and tenant risk. e. What are the best cities for property investment in Pakistan? Islamabad, Karachi, Lahore, and Rawalpindi offer different combinations of property prices, yields, and entry costs. Global Property Guide mentioned that average house prices ranged from PKR 35 million in Rawalpindi to PKR 83.6 million in Islamabad among these four cities. Commercial investors should then narrow the choice to actual business corridors and occupied catchments. f. Can foreigners buy property in Pakistan? Foreign nationals working or residing in Pakistan may buy or rent property, subject to legal formalities. Buyers should verify current requirements, title, approvals, transferability, and taxes before purchasing either residential or commercial real estate. g. What should investors check before buying property in Pakistan? Before investing in Pakistan real estate, verify ownership, title or registry records, NOC and planning approvals where applicable, land use, transferability, outstanding dues, tax position, and litigation. Commercial buyers should additionally test footfall and tenant demand; residential buyers should assess completion status, livability, and realistic rent. Explore residential and commercial opportunities in Pakistan with IQI Global and speak with a local property professional before making your next move. [custom_blog_form] References Delmendo, L. C. (2026, March). Pakistan's residential property market analysis 2026. Global Property Guide. Retrieved fromhttps://www.globalpropertyguide.com/asia/pakistan/price-history FinanceWire. (2026, October 4). One Homes completes One Canal Road in Lahore, a new benchmark for luxury real estate delivery in Pakistan. markets.businessinsider.com. Retrieved fromhttps://markets.businessinsider.com/news/currencies/one-homes-completes-one-canal-road-in-lahore-a-new-benchmark-for-luxury-real-estate-delivery-in-pakistan-1036595589 Hamid, J. (2026, August). Pakistan stability, reform and yield-drive growth. IQI Global. Retrieved fromhttps://iqiglobal.com/blog/wp-content/uploads/2026/07/Juwai-IQI-Newsletter-August-2026-15.pdf Hamid, J. (2026, October). Pakistan: Resilience in a high-rate market. IQI Global. Retrieved fromhttps://iqiglobal.com/blog/wp-content/uploads/2026/10/Juwai-IQI-Newsletter-October-2026-15.pdf Iqbal, A. (2026, June 9). Commercial real estate in Pakistan: A complete investor’s guide for 2026. UnionDevelopers. Retrieved fromhttps://www.uniondevelopers.com/blog/commercial-real-estate-in-pakistan/ Khan, A. H. (2026, October 4). Why Pakistan saves in plots. Dawn. Retrieved fromhttps://www.dawn.com/news/2033860 Khan, G. A. (2026, July 28). Property demand, prices surge across Pakistan’s major cities. Brecorder. Retrieved fromhttps://www.brecorder.com/news/40432214/property-demand-prices-surge-across-pakistans-major-cities Khan, M. (2026, October 6). Pakistan launches National Housing Policy 2025, first update in nearly 25 years. Milkiyat.com. Retrieved fromhttps://milkiyat.com/articles/pakistan-launches-national-housing-policy-2025-first-update-in-nearly-25-years One Homes. (2026, February 5). Pakistan property market predictions for 2026 and beyond. onehomes.com. Retrieved fromhttps://onehomes.com/blog/pakistan-property-market-predictions-for-2026-and-beyond One Homes. (2026, July 13). High ROI real estate zones in Pakistan (2026). onehomes.com. Retrieved fromhttps://onehomes.com/blog/best-high-roi-property-investment-areas-in-pakistan
New launch got the showroom and the free gifts. But a subsale property gets you something better: a real unit you can walk into, a real neighbourhood you can check, and keys in months, not years. Whether you're buying for own stay or eyeing a unit to renovate and flip, the process is the same. And honestly, it's not that complicated once you know the steps. This guide walks you through buying a second-hand house in Malaysia in 7 steps, what to check before you sign anything, what it really costs, and the maths every flipper needs to see first. TL;DR Subsale means buying a property from an existing owner, not from the developer. You pay a 2% to 3% earnest deposit when your offer is accepted, then top up to 10% when you sign the SPA. The bank lends based on the lower of the price or the bank's valuation. If the valuation comes in low, you top up the gap in cash. Completion is usually 3 months from the SPA, plus a 1-month extension if needed. Leasehold titles can take longer. First home up to RM500,000? You pay zero stamp duty until 31 December 2027. Flipping within 3 years means 30% RPGT on your gain, plus possible loan lock-in penalties. Do the maths first. What's inside this guideTL;DRWhat Is a Subsale Property?How to Buy a Subsale Property in Malaysia: 7 StepsStep 1: Set Your Budget and Check Your Loan EligibilityStep 2: Find the Right Subsale PropertyStep 3: Make an Offer and Pay the Earnest DepositStep 4: Get the Best Home LoanStep 5: What Should You Check Before Signing the SPA for a Subsale House?Step 6: Sign the SPA and Loan AgreementStep 7: Completion and Getting Your KeysCan You Buy an Under-Construction Property on Subsale?Thinking of Flipping a Subsale House? Do the Maths FirstFrequently Asked Questions What Is a Subsale Property? A subsale property is a property bought from an existing owner, not from a developer. Some people also call it a secondary market, resale or second-hand house. It can be a 20-year-old terrace in PJ or a condo that was completed last year. As long as you're buying from the current owner, it's subsale. Subsale vs new launch: which one suits you? FactorSubsaleNew launchWhat you seeThe actual unit, neighbours, traffic and allA showroom and a brochureMove-in timeAround 3 to 6 monthsOften 2 to 4 years if still under constructionCash upfront10% deposit plus feesLower, developers often absorb some feesPrice checkCompare with actual transacted prices nearbyDeveloper's price, rebates and packagesDefectsNo developer warranty, so inspect carefullyDeveloper fixes defects during the Defect Liability PeriodRent or flipCan rent or renovate almost immediatelyWait for completion first Need a home now, or want to start earning rent fast? Subsale usually wins. Want more time to save? A new launch buys you that time. How to Buy a Subsale Property in Malaysia: 7 Steps The 7 steps to buying a subsale property in Malaysia, from budget to keys Set your budget and check your loan eligibility Find the right subsale property Make an offer and pay the earnest deposit Get the best home loan Check everything before you sign the SPA Sign the SPA and loan agreement Completion and getting your keys Step 1: Set Your Budget and Check Your Loan Eligibility Don't start with listings. Start with what the bank will actually lend you. For your first two homes, banks usually finance up to 90% of the price. From your third housing loan onwards, Bank Negara caps it at 70%. So for most buyers, prepare at least 10% in cash, plus another 3% to 5% for fees. Banks also check your DSR (Debt Service Ratio), which is how much of your gross salary already goes to debt repayments. Keep it under 60% to 70% to be safe. Check how much you can borrow here: Estimates for guidance only. Actual figures depend on the bank's assessment, current rates, and your full financial profile. Planning to renovate? Many buyers cap their reno budget at about 10% of the property value, especially for own stay. Flippers need to be stricter, more on that later. Not sure how banks read your profile? See how DSR affects your home loan and how to check your CCRIS report. Step 2: Find the Right Subsale Property Listings are for shortlisting. The real decision happens when you go and see the unit. Location first: commute in actual jam, LRT or MRT access, schools, clinics, your daily kopi spot. Transacted prices: what similar units in the same block actually sold for, not just what sellers are asking. Building condition: lifts, corridors, car park, and how well the management is running the place. Tenure: freehold or leasehold, and how many years are left on the lease. For flippers: is there demand from buyers or tenants in this area, and how long do units take to sell? Go at different times of day. A quiet Sunday morning can feel very different from a weekday evening with lorries outside. Want to know where prices are heading? See the latest Malaysia subsale price data, or browse subsale homes on IQI. Not sure what to check during a subsale viewing? Save these tips from a real estate agent before your next visit. View on Threads Step 3: Make an Offer and Pay the Earnest Deposit Found the one? You make an offer through a Letter of Offer to Purchase (OTP), sometimes called a booking form. Once the seller accepts, you pay an earnest deposit of about 2% to 3% of the price. This shows you're serious and takes the unit off the market. Before you sign the OTP, check these: Who holds the deposit. Ideally the agent or lawyer holds it as stakeholder, not the seller directly. What happens if your loan is rejected. A good OTP refunds your deposit in that case. How long you have to sign the SPA, usually 14 to 21 days. What stays with the unit: aircond, built-in wardrobes, kitchen cabinets, water heaters, curtains. Write everything down. If it's not in writing, it didn't happen. Buyers usually don't pay the agent's commission on a subsale. The seller does, typically 2% to 3%. Step 4: Get the Best Home Loan Apply to at least two or three banks. Even a 0.1% rate difference adds up to thousands over a 30 to 35 year loan. Compare more than the interest rate: Lock-in period and early settlement penalty (very important for flippers) Flexi, semi-flexi or term loan Margin of financing offered on your profile Legal fee subsidies or zero-moving-cost packages Bank value vs market value: why it matters The bank sends a valuer to check what the property is worth. It then lends based on the lower of the purchase price or that valuation. Example: you agree to buy at RM600,000, but the bank values it at RM550,000. At 90%, the bank lends RM495,000 instead of RM540,000. That RM45,000 gap? You top up in cash. So ask your agent for a realistic valuation range before you commit, especially if you're stretching the budget. How much is the monthly installment? Plug in the price, rate and tenure to see what you'll pay each month: Estimates for guidance only. Actual figures depend on the bank's assessment, current rates, and your full financial profile. Compare packages in our latest house loan interest rates and flexi vs semi-flexi vs fixed loans. Found a subsale unit but not sure the price is right? An IQI agent checks recent transacted prices in the same area, gives you a realistic valuation range, and helps you negotiate before you pay a single sen. Free, and no pressure. Talk to a local IQI agent before you make your offer Or browse now: subsale homes on IQI. Step 5: What Should You Check Before Signing the SPA for a Subsale House? This is the step most first-timers rush. Subsale homes don't come with a developer's defect warranty, so whatever problem you miss now becomes your problem later. Run through this checklist with your lawyer and agent before you sign the Sale and Purchase Agreement (SPA): Paperwork checks Land search (carian rasmi): confirms the registered owner, the title type and whether the property is charged to a bank. Seller's identity matches the name on the title. Title status: has the individual or strata title been issued, or is it still under the master title? Restrictions: Bumiputera lot, leasehold consent requirements, or caveats on the title. Remaining lease, if leasehold. Short leases can make it harder to get a loan or sell later. Outstanding bills: quit rent (cukai tanah), assessment (cukai pintu), maintenance fees and sinking fund. Ask for the latest statements. Renovation approvals for landed homes, especially extensions. Illegal extensions can become your headache. Physical checks Water leaks, damp walls and ceiling stains Cracks in walls and floors Wiring, DB box and power points Water pressure, piping and toilets Roof and gutters for landed homes Windows, doors and grilles Agreement checks List of fixtures and fittings that come with the unit Any known defects you've agreed on, in writing Loan condition: the SPA should protect you if your loan doesn't get approved Completion period and extension terms Learn more about why property valuation matters and the difference between leasehold and freehold. Step 6: Sign the SPA and Loan Agreement Once everything checks out, you sign the SPA and top up your deposit to 10% of the price. Your lawyer holds this as stakeholder. You'll also sign the loan agreement with your bank. Then the lawyers handle the rest: Stamping the SPA and loan agreement Preparing the Memorandum of Transfer (MOT), the document that moves the property into your name Getting state consent if the property is leasehold or has restrictions Redeeming the seller's existing bank loan, if any How much does it cost to buy a subsale property? CostHow muchDeposit10% of the price (2% to 3% earnest plus the balance at SPA)Stamp duty on the MOT1% on the first RM100,000, 2% up to RM500,000, 3% up to RM1,000,000, 4% aboveStamp duty on the loan agreement0.5% of the loan amountLegal fees (SPA and loan)1.25% on the first RM500,000 and 1% on the next RM7 million, for each agreement, plus disbursementsValuation feeOften paid upfront and sometimes refunded or absorbed by the bank Worked example: on a RM450,000 subsale with a 90% loan, MOT stamp duty is RM8,000 and loan stamp duty is RM2,025. Legal fees come to about RM5,625 for the SPA and RM5,060 for the loan agreement. First home and priced up to RM500,000? Malaysian first-time buyers pay zero stamp duty on both the MOT and loan agreement until 31 December 2027. That saves this buyer RM10,025. Get a full estimate with the property transaction fees calculator, and see the hidden fees most buyers forget. Step 7: Completion and Getting Your Keys The SPA gives a completion period, usually 3 months, with a possible 1-month extension. Late payment interest usually applies during the extension. During this time, the bank releases the loan amount. Part of it pays off the seller's old loan, and the rest goes to the seller. Once full payment is made, you get vacant possession, which simply means the seller moves out and hands you the keys. Your lawyer also settles the apportionment. That just means splitting bills like quit rent, assessment and maintenance fees fairly between you and the seller, up to the handover date. Before taking the keys, do a final walk-through. Check that the unit is in the agreed condition and the fixtures are still there. How long does a subsale purchase take? StageTypical timingOffer accepted, earnest deposit paidDay 0Loan approval1 to 3 weeksSPA signed, deposit topped up to 10%Within 14 to 21 daysCompletion period3 months, plus 1-month extension if neededLeasehold or restricted titleLonger, as state consent is needed Can You Buy an Under-Construction Property on Subsale? Can or not? Yes. If the original buyer wants to sell before the project is completed, you can buy their unit on subsale. The difference is that there's no title to transfer yet. Instead, the original buyer's rights under the developer's SPA are transferred to you through a deed of assignment. The developer must give consent, and usually charges an admin fee. You take over the remaining progressive payments to the developer. Your bank will check the developer, the project progress and the original SPA. You still get the developer's Defect Liability Period once the unit is completed. It can be a good way to get into a popular project at today's price. Just make sure your lawyer checks the developer's consent conditions first. Thinking of Flipping a Subsale House? Do the Maths First Buy low, renovate, sell high. Sounds simple, right? In Malaysia, the costs of buying, holding and selling eat into your profit fast. Here's what flippers need to factor in: RPGT (Real Property Gains Tax): 30% on your gain if you sell within 3 years, 20% in year 4, 15% in year 5 and 0% from year 6 for Malaysian citizens. Loan lock-in: many home loans charge an early settlement penalty, often around 2% to 3% of the loan, if you sell within the first few years. Financing limits: from your third housing loan onwards, banks lend up to 70% only. Holding costs: loan interest, maintenance fees, quit rent and assessment every month until it sells. Selling costs: agent's commission (with SST) and your own lawyer's fees as the seller. RPGT retention: the buyer holds back 3% of your sale price until your RPGT is settled. Worked example: buy at RM400,000, sell at RM500,000 a year later Assume a second property, 90% loan at 4.2%, RM30,000 renovation, sold after 12 months at RM500,000. ItemAmountPrice gain (RM500,000 minus RM400,000)+RM100,000Buying costs (stamp duty, legal fees, valuation)About RM19,500RenovationRM30,000Holding costs for 12 months (interest, maintenance, taxes)About RM20,500Selling costs (agent fee with SST, seller's legal fee)About RM19,750Early settlement penalty (2% of loan)About RM7,200RPGT at 30% (after exemption)About RM8,500Net resultAbout RM5,400 loss Yes, you read that right. Rugi. A RM100,000 jump in price can still end in a loss once every cost is counted. Flips work when you buy well below market, not when you hope prices rise. Smart flippers also pick loans without heavy lock-ins, keep renovations to what buyers actually pay for, and often rent the unit out while waiting for a better time to sell. Figures are rounded estimates for illustration. RPGT, penalties and fees depend on your loan, your timing and your full situation, so get advice from a tax agent and your bank. Renovating to sell? See home improvements that actually add value. Own stay or flip, buy your subsale with someone who knows the area. An IQI agent helps you spot fairly priced units, checks the paperwork, coordinates the lawyer and bank, and walks you from offer to keys. Speak to an IQI agent for free, personalised advice. Frequently Asked Questions What does subsale mean in Malaysia? Subsale means buying a property from an existing owner rather than from a developer. It is also called a resale, secondary market or second-hand property, and can be anything from an old terrace house to a recently completed condo. How much deposit do I need for a subsale property? Usually 10% of the price. You pay an earnest deposit of about 2% to 3% when your offer is accepted, then the balance to 10% when you sign the SPA. Set aside another 3% to 5% for stamp duty, legal fees and valuation. Do I pay agent fees when buying a subsale property? Usually not. In a typical subsale, the seller pays the agent's commission, commonly 2% to 3% of the price. Confirm this in writing before you sign the offer. Do first-time buyers pay stamp duty on a subsale house? Malaysian first-time buyers purchasing a home priced up to RM500,000 are exempt from stamp duty on both the MOT and the loan agreement, for SPAs signed until 31 December 2027. This applies to subsale homes too. Looking at a subsale home and want a second pair of eyes before you sign? Our IQI agents will check the price, the paperwork and the process with you. Leave your details below and we'll get in touch. [custom_blog_form] Related Reading: Buying Property in Malaysia: A Step-by-Step Guide (2026) First-Time Home Buyer Guide Malaysia 2026 Malaysia Subsale Prices: Latest Data Latest House Loan Interest Rates Hidden Fees First-Home Buyers Should Know Sources: https://edgeprop.my/content/bank-negara-imposes-maximum-loan-value-ltv-ratio-70-3rd-home-loan https://www.stashaway.my/r/real-property-gains-tax-rpgt-malaysia
Buying a house under RM300K in KL is hard, but the route is the same one every first-time buyer in Malaysia follows: check your finances, use the incentives you qualify for, shortlist and inspect, secure the unit, get the loan, sign the agreements, then collect your keys. What changes at this budget is how tight each step gets. This guide shows exactly where. Most first-timers discover the squeeze the same way. A stable job, decent savings, RM300,000 to spend. Then the listings load, and the prices do not match the promise. You are not imagining it. Below is what RM300K realistically buys in Greater KL in 2026, what it costs on top of the price tag, and a seven-step plan built for this budget. TL;DR / Key Takeaways Buying a house under RM300K in KL is possible, but mostly through government schemes or older subsale units in peripheral Greater KL. Kuala Lumpur's average house price was RM819,848 in the Property Market Report 2025. Yet 14,201 unsold completed homes nationwide are priced at RM300,000 and below. Plan for about 3% to 5% in upfront costs on top of the 10% down payment. First-time buyers pay the lower end because stamp duty is waived on homes up to RM500,000 until 31 December 2027. Banks typically cap your Debt Service Ratio (DSR) at 40% to 70% of net income. Check eCCRIS and CTOS before you apply. For new launches under the Housing Development Act, developers may not legally collect a booking fee. Subsale buyers usually pay a 2% to 3% earnest deposit. New homes come with a 24-month defect liability period from the date you receive the keys. Realistic Guide for First-Time BuyersTL;DR / Key TakeawaysIs It Really Possible to Buy a House Under RM300K in KL?KL's Property Market Under RM300K in 2026Why "Affordable" Homes Still Feel Out of ReachWhere to Find a Home Under RM300K in Greater KLHow to Buy a House as a First-Time Buyer on a RM300K Budget: 7 StepsThe Broader Picture: Addressing KL's Affordability ChallengeLocal Expert Insight: What Do The Professionals Say?FAQ Is It Really Possible to Buy a House Under RM300K in KL? Yes, but not in central Kuala Lumpur, and rarely for a new home on the open market. The realistic routes are government housing schemes and older subsale apartments in mature, peripheral parts of Greater KL. Expect trade-offs on location, size or building age, and budget for the full cost of ownership, not just the price. KL's Property Market Under RM300K in 2026 The gap is wide. According to the Property Market Report 2025, the national average house price is RM502,922. Kuala Lumpur averages RM819,848 and Selangor RM567,505. Malaysia's median house price-to-income ratio stood at 4.2 in 2024. Housing is considered affordable at three times household income or below, which is why the market has been rated "seriously unaffordable" since 2014. The primary issue remains pricing relative to income. Financing exposes the gap while income growth determines how severe it becomes over time. Assoc Prof Dr Muhammad Najib Razali, Universiti Teknologi Malaysia, speaking to The Sun, 26 May 2026 The overhang paradox Here is the twist. Cheap homes are not selling out. NAPIC data for Q1 2026 shows 32,801 completed homes worth RM16.37 billion still unsold nationwide, 3,733 of them in Kuala Lumpur. 14,201 of those unsold units, or 43.3%, are priced at RM300,000 and below, together worth RM2.77 billion. So the problem is not a lack of sub-RM300K homes. It is that many of them are the wrong product, in the wrong place, for buyers who cannot get financing. Our NAPIC Q1 2026 breakdown has the full picture. Why "Affordable" Homes Still Feel Out of Reach Three barriers sit between a RM300,000 price tag and a set of keys: the cash you need upfront, the loan you need approved, and whether the home actually works for your life. What it really costs upfront to buy a RM300,000 home The 10% down payment is only the start. Legal fees, stamp duty, valuation and loan insurance typically add another 3% to 5% of the price, depending on whether you qualify for the first-time buyer exemption. Here is the breakdown for a RM300,000 subsale home with a 90% loan of RM270,000. Cost itemStandard (RM)First-time buyer (RM)Down payment (10%)30,00030,000Legal fee, Sale and Purchase Agreement (1.25%)3,7503,750Legal fee, loan agreement (1.25%)3,3753,3758% service tax on legal fees570570Stamp duty, Memorandum of Transfer5,0000Stamp duty, loan agreement (0.5%)1,3500Valuation fee (estimate)1,0001,000Extra upfront costs15,045 (5.0%)8,695 (2.9%)Total cash before keys45,04538,695 Legal fees follow the Solicitors' Remuneration Order 2023 scale, before disbursements. Stamp duty on the transfer is 1% on the first RM100,000 and 2% on the next RM400,000. The first-time buyer column assumes the full exemption on transfer and loan instruments for homes up to RM500,000, extended to 31 December 2027 under Budget 2026. Two items are not in the table because they vary so much. MRTA (Mortgage Reducing Term Assurance) is a single premium that is often financed into the loan. MLTA (Mortgage Level Term Assurance) usually costs more, but the cover stays with you if you refinance or sell. Get quotes for both before your loan offer arrives. After you move in, maintenance fees, sinking fund, quit rent, assessment and parking keep coming every month. Our guide to the stamp duty waiver extended to 2027 explains who qualifies for the exemption. Financing hurdles and loan rejection Loan approval is where many sub-RM300K purchases collapse. Units get booked by eager buyers, the bank says no, and the home goes back into unsold stock. Banks judge you on your Debt Service Ratio (DSR), the share of your net income already going to debt repayments. PTPTN, a car loan and credit card balances all count. So do late payments recorded in CCRIS, Bank Negara's Central Credit Reference Information System. Young professionals and gig workers are the most likely to fail on DSR or documentation, not on salary alone. Work out your DSR before you start viewing. It tells you how much room you actually have. Estimates for guidance only. Each bank applies its own DSR limits and income recognition rules. Freelancer or e-hailing driver? Read our guide on how gig workers get a home loan approved. Location vs product: what you can expect To hit the price, some developers build hyper-dense, shoebox layouts with poor workmanship and limited parking. Others build on cheap land far from jobs, with weak public transport. Faced with a long, costly commute, many buyers decide to keep renting near work instead. A home is only affordable if the commute is too. Where to Find a Home Under RM300K in Greater KL Central KL, Damansara and most of PJ are out of range for this budget. Widen the search to government schemes and the subsale market in mature, peripheral districts. Government housing schemes Residensi Wilayah (formerly RUMAWIP): units capped at RM300,000, for Malaysians aged 21 and above who were born in, live in or work in Kuala Lumpur, Putrajaya or Labuan. Single applicants may earn up to RM10,000 a month, married couples up to RM15,000. There is a 10-year moratorium on open-market resale. Apply via the official Residensi Wilayah portal. Rumah Selangorku: Selangor's scheme, with prices capped by unit type and household income. CNA reported a 27-year-old administrative assistant buying a new Shah Alam unit for RM290,000 under the scheme, completing in late 2028. See our Rumah Selangorku application guide. PR1MA: the federal affordable-housing builder, with projects across the country and prices that vary widely by location. Schemes come with ballots, waiting lists and allocations that may not suit your workplace. Compare them all in our first-home schemes guide. The subsale market Outside the schemes, the subsale market is your main hunting ground. At this budget that usually means: Older leasehold apartments and flats in parts of Kepong, Jalan Klang Lama, Cheras and Setapak. Expect renovation costs and check the remaining lease. Smaller condominiums built 15 to 20 years ago in less developed parts of Greater KL. Low-cost apartments with basic facilities, priced for specific income groups. Property options under RM300K: KL and Greater KL compared AreaTypical propertyIndicative priceEst. monthly repaymentProsConsKepongOlder apartment or flatRM200K to RM300KRM800 to RM1,200Established amenities, some MRT accessOlder buildings, trafficJalan Klang LamaOlder apartment or flatRM230K to RM300KRM920 to RM1,200Close to the city, good connectivityCongestion, high densityCheras (selected zones)Older apartment, Residensi WilayahRM200K to RM300KRM800 to RM1,200Wide amenities, MRT and LRT accessQuality varies a lot by zoneSetapakOlder apartment or flatRM220K to RM300KRM880 to RM1,200Near universities, LRT accessOlder infrastructureShah AlamNew apartment under Rumah SelangorkuRM240K to RM290KRM960 to RM1,160Newer unit, scheme pricingFurther from KL, limited supply Prices are indicative and vary by building. Repayments assume a 90% loan at 4% a year over 35 years. Verify current listings and your bank's rate before deciding. How to Buy a House as a First-Time Buyer on a RM300K Budget: 7 Steps These are the same steps every first-time buyer in Malaysia follows. Here they are tuned for a RM300K budget in Greater KL. For the full general process, see our complete guide to buying a house in Malaysia. Step 1: Check your financial readiness Start with your Debt Service Ratio: your total monthly debt repayments, including the new home loan, divided by your net monthly income. Most Malaysian banks cap DSR somewhere between 40% and 70% of net income. The exact limit depends on the bank and your income level, and lower earners can face the tighter end. For comfort, aim to keep the home loan instalment itself within 30% to 40% of your income. Here is how that plays out on a RM300,000 home with a 90% loan at 4% over 35 years, which comes to about RM1,195 a month. Net monthly income RM4,000RM a monthCar loan650PTPTN200New home loan1,195Total commitments and DSR2,045 (51%) At 51%, this buyer passes a 60% or 70% cap but fails a 40% one. Clearing the car loan first would drop the DSR to 35%. Then check your credit record. Request your free report from Bank Negara's eCCRIS, and a CTOS report, which also picks up non-bank records. Settle any arrears, including PTPTN, before you apply, because banks see your last 12 months of repayment behaviour. Estimates for guidance only. Actual eligibility depends on the bank's full credit assessment. Step 2: Use the incentives you qualify for At this budget, incentives are not a bonus. They are the plan. Stamp duty exemption: first-time buyers pay no stamp duty on the transfer or loan agreement for homes up to RM500,000 until 31 December 2027. On RM300,000, that saves RM6,350. Scheme eligibility: check Residensi Wilayah and Rumah Selangorku rules against your income, age and where you work, then register early. Ballots take time. Step 3: Shortlist and inspect properly Visit each area at peak hour, not just on a Sunday afternoon. Time the commute to work and check the nearest MRT or LRT on MyRapid. For older subsale units, look past the paint. Check plumbing, wiring and water seepage, ask the management office for a statement of outstanding maintenance fees, and confirm how many years remain on the lease. A cheap unit with 40 years left on the lease is much harder to finance and resell. Step 4: Secure the property with a booking How you secure the unit depends on what you are buying. Property typeWhat you pay to secure itNew launch under the Housing Development ActNo booking fee should be collected. Regulation 11(2) of the Housing Development (Control and Licensing) Regulations 1989 bars any payment outside the Sale and Purchase Agreement. The developer collects 10% when you sign it.Subsale (secondary market)An earnest deposit of usually 2% to 3% (RM6,000 to RM9,000 on RM300,000) with a signed letter of offer, held by the agent or lawyer as stakeholder. The balance to 10% is paid when the agreement is signed.Government schemeYou register and apply through the scheme portal. Units are allocated by ballot or merit, then you proceed to the agreement. If a developer does take a "booking fee", get an official receipt. The Federal Court ruled in PJD Regency Sdn Bhd v Tribunal Tuntutan Pembeli Rumah (2021) that compensation for late delivery is counted from the date that fee was paid, not from the date you signed. Step 5: Apply for a home loan Apply to two or three banks at once. Approval terms, margins and rates can differ more than you expect. Salaried buyers typically need: NRIC (both sides) Latest three months' payslips Latest EPF statement Three to six months of bank statements showing your salary credited Latest EA form or Form BE The letter of offer or booking form for the property Self-employed and gig workers should add their SSM registration, six months of bank statements and the latest tax return with proof of payment. With a complete file, banks have reported taking an average of 2 to 9 working days to process a housing loan, according to the Association of Banks in Malaysia. Missing documents are the most common cause of delay. Once you have an approval in principle, project your real monthly repayment. Estimates for guidance only. Actual figures depend on the bank's rate and your full financial profile. Step 6: Sign the legal agreements Three documents do the heavy lifting. Sale and Purchase Agreement (SPA): the contract between you and the seller or developer. It sets the price, payment schedule and completion date. Loan agreement: your contract with the bank, signed after the loan offer is accepted. Memorandum of Transfer (MOT): transfers the title to your name on a subsale where an individual or strata title exists. If the title has not been issued yet, a Deed of Assignment is used instead. A subsale usually completes within three months of the SPA, with a one-month extension if needed. A new launch is paid in stages as construction progresses, with your bank releasing the loan against each billing. Step 7: Collect your keys and protect yourself For a subsale, inspect the unit again before the balance is released, and make sure utility and maintenance accounts are settled to the handover date. For a new launch, vacant possession starts your 24-month defect liability period under the Housing Development Act. Report defects in writing with photos. The developer then has 30 days to fix them, at no cost to you. The Broader Picture: Addressing KL's Affordability Challenge Malaysia's housing challenge is no longer just a race for raw volume; it's a structural issue of product mismatch, location flaws, and financing barriers (thestar.com.my, 2026). Experts and bodies like Bank Negara Malaysia (BNM) and the National House Buyers Association (HBA) have consistently called for a coordinated recovery roadmap (thestar.com.my, 2026; Bank Negara Malaysia, 2017). Calls for Change & Policy Directions Recommendations include: Build-Then-Sell (BTS) Framework: HBA advocates for this model, where buyers pay 10% upfront and 90% upon completion, curbing speculative launches and ensuring products align with demand (thestar.com.my, 2026). Modernizing Credit Underwriting: Commercial banks are urged to create flexible credit scoring for gig-economy workers and expand shared-equity models (thestar.com.my, 2026). Integrated Data Bank: HBA has called for the Housing and Local Government Ministry to implement a comprehensive, centralized big data bank for real-time supply and demand metrics (thestar.com.my, 2026; Bank Negara Malaysia, 2017). This would move policymaking beyond "arbitrary government quotas" to data-driven planning. The government maintains it must "strike a balance" to ensure home prices appreciate at a "healthy" rate, as existing homeowners do not want their property values to decline (channelnewsasia.com, 2026). The focus is also on attracting foreign investment to create high-income jobs, hoping that increased incomes will naturally make housing more affordable (channelnewsasia.com, 2026). However, the Khazanah Research Institute (KRI) argued in 2024 that "no amount of wage increment… can realistically keep pace with Malaysia’s rapid house price escalation" (channelnewsasia.com, 2026). Local Expert Insight: What Do The Professionals Say? “Malaysia’s affordability challenge is not driven by a single factor but by the interaction between pricing, income, financing, land cost and market structure,”Universiti Teknologi Malaysia, Assoc Prof Dr Muhammad Najib Razali Assoc. Prof. Dr. Muhammad Najib Razali, specializing in property economics and finance. He emphasizes that "the primary issue remains pricing relative to income. Financing exposes the gap while income growth determines how severe it becomes over time.” (thesun.my, 2026). "while schemes exist, the true challenge lies in their integration with urban planning. A home that's 'affordable' on paper but located an hour from any job hub with no public transport connectivity isn't truly affordable in terms of daily living costs and quality of life."IQI property consultant Exploring current property listings under your budget is a great next step. Take a look at available properties in Kuala Lumpur and Greater KL that might fit your criteria and continue your journey towards homeownership. Explore KL Properties under RM300K → FAQ Is it possible to buy a house under RM300K in central KL? It is largely unrealistic to find new or prime properties under RM300K in central Kuala Lumpur. Options are primarily limited to government affordable housing schemes (like Residensi Wilayah) or very old, often small, sub-sale apartments located in less central, mature districts of Greater KL. What are the best government housing schemes for first-time buyers in KL? Key government housing schemes for first-time buyers in KL/Greater KL include Rumah Selangorku (for Selangor), Residensi Wilayah (for Federal Territories), and PR1MA. Each has specific eligibility criteria and often involves balloting or waiting lists, so thorough research is essential. How much down payment do I need for a RM300K house in KL? Typically, you need a 10% down payment, which would be RM30,000 for a RM300K house. Additionally, you must budget for other upfront costs such as legal fees, stamping fees, and valuation fees, which can add another 5-10% to your initial outlay. Is a property under RM300K in KL a good investment? Investing in properties under RM300K in KL requires careful consideration. These properties, often in peripheral areas or older, may experience slower capital appreciation and stagnant rental yields due to factors like property overhang and location mismatch. It's crucial to evaluate long-term potential against recurring costs. What are the hidden costs of buying property in KL? Beyond the purchase price and down payment, hidden costs include legal fees for the Sale and Purchase Agreement, stamp duty for the Memorandum of Transfer (MOT), valuation fees, Mortgage Reducing Term Assurance (MRTA)/Mortgage Level Term Assurance (MLTA), and potentially property agent fees. Ongoing costs also include monthly maintenance fees, sinking funds, quit rent, and assessment rates. Looking for expert guidance on navigating the KL property market for your first home? Connect with a property expert today for personalized advice and explore suitable options. [custom_blog_form] Continue Reading: Understanding the Debt Service Ratio (DSR) in Malaysia & How It Affects Your Home Loan A Guide to Rumah Selangorku: Eligibility and Application Property Investment Outside KL: Opportunities Beyond the Capital First-Time Home Buyer Malaysia: Grants & Incentives Explained Sources: channelnewsasia.com. (2026, March 11). IN FOCUS: Why have Malaysia’s homes remained ‘seriously unaffordable’ for a decade and counting?. Retrieved from https://www.channelnewsasia.com/asia/malaysia-house-price-affordable-developer-wage-5980991 thesun.my. (2026, May 26). Malaysia’s housing affordability crisis driven by price-income gap: Expert. Retrieved from https://thesun.my/news/malaysias-housing-affordability-crisis-driven-by-price-income-gap-expert/ thestar.com.my. (2026, June 20). Why RM300,000 homes remain unsold. Retrieved from https://www.thestar.com.my/business/business-news/2026/06/21/why-rm300000-homes-remain-unsold Bank Negara Malaysia. (2017). Affordable Housing: Challenges and the Way Forward. BNM Quarterly Bulletin (Bank Negara Malaysia). Retrieved from N/A Narquith. (n.d.). Evaluating My Affordability on My First House. Reddit / r/MalaysianPF. Retrieved from https://www.reddit.com/r/MalaysianPF/comments/14t00n1/evaluatingmyaffordabilityonmyfirsthouse/ Reddit. (2024, July 2). Does Malaysian No longer afford to buy a house? : r/malaysia. Retrieved from https://www.reddit.com/r/malaysia/comments/1dyujo6/doesmalaysiannolongeraffordtobuyahouse/ tomkokotom. (2023, January). Is this house too expensive? Any rule of thumb?. Reddit. Retrieved from https://www.reddit.com/r/MalaysianPF/comments/10q0gc6/isthishousetooexpensiveanyruleofthumb
Ready to get started?
Get in touch now.