

Team Leader (Subsales) ∙ United
Stephanie Yap
REN20525
Team Leader (Subsales) ∙ United
Stephanie Yap
REN20525
About Stephanie Yap
Leveraging market knowledge and negotiation skills to deliver exceptional results. Your real estate success is my priority. Ready to make your real estate dreams a reality? Let's chat. Your dream home awaits.
4 years at IQI
133 transactions
116 properties on sale
56 properties on rent
Contact Stephanie Yap
Stephanie Yap Social Links
No social links available.
Stephanie Yap's Service Locations
Stephanie Yap's Service Locations
My Listings

Asteria Apartment @ Bandar ParkLand
Bandar Parklands Klang
RM 1,300 /month
Listed on June 15, 2026
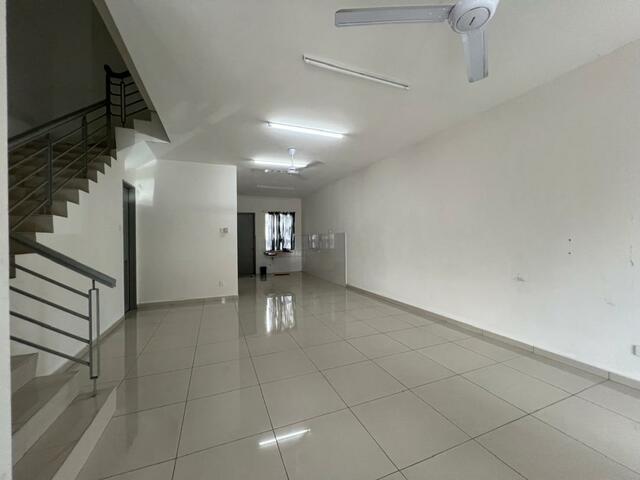
Taman Sri Jaromas
Jalan 3/10
RM 550,000
Listed on October 8, 2025
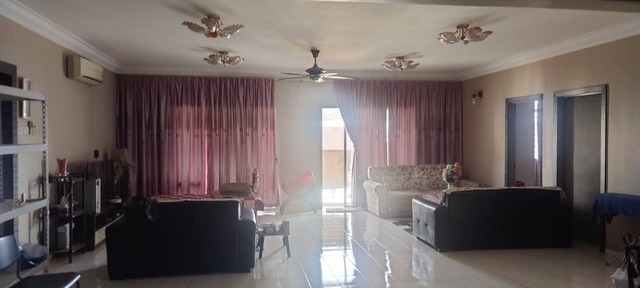
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
RM 468,000
Listed on November 16, 2025
Sri Nervillia Apartment (Pangsapuri Sri Nervillia)
Jalan Anggerik Nervillia 31/166, Kota Kemuning
RM 850 /month
Listed on July 22, 2025
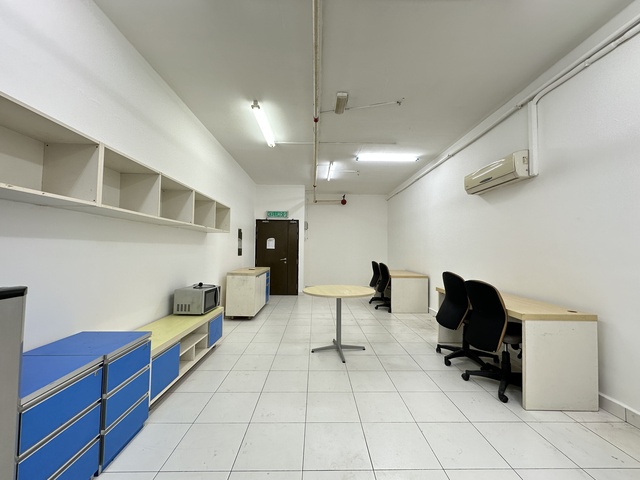
Avenue Crest
Section 22, Batu Tiga, Shah Alam
RM 1,050 /month
Listed on April 16, 2026
Taman Melawis (Taman Heng Luen)
Jalan Emas; Jalan Besi
RM 550,000
Listed on November 14, 2025

Taman Sentosa
Jalan Dato Abdul Hamid 16
RM 535,000
Listed on February 15, 2025
Taman Sri Andalas
Jalan Sri Damak
RM 1,800 /month
Listed on March 25, 2024
Persiaran Anggerik Aranda
Persiaran Anggerik Aranda
RM 1,200,000
Listed on October 14, 2025
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
RM 279,980
Listed on March 9, 2026
Trifolia Apartment
Jalan Samarinda Taman Saga
RM 1,700 /month
Listed on August 2, 2026
Avenue Crest
Section 22, Batu Tiga, Shah Alam
RM 1,200 /month
Listed on December 2, 2025

Golden Villa Apartment
Jln Temenggung 37, Taman Sentosa Perdana
RM 230,000
Listed on April 16, 2024
Bandar Bukit Tinggi
Lorong Batu Nilam 14
RM 580,000
Listed on February 5, 2026
28 Boulevard (28 BLVD)
Jalan Perdana 3/10, Off Jalan Lingkaran Tengah 2 (MRR2)
RM 1,700 /month
Listed on July 31, 2026
Sunsuria Forum @ 7th Avenue
Jln Setia Dagang AL U13/AL, Seksyen U13, Setia Alam
RM 450,000
Listed on June 28, 2026
Ken Rimba
Jalan Lengkuas, Rimba Jaya
RM 649,980
Listed on December 14, 2025
Taman Bayu Perdana
Jalan Sambau
RM 580,000
Listed on August 4, 2026

Taman Sentosa
Jalan Temenggung 37
RM 760,000
Listed on November 20, 2024
Bandar Botanic
Persiaran Botanic
RM 1,199,980
Listed on September 23, 2025
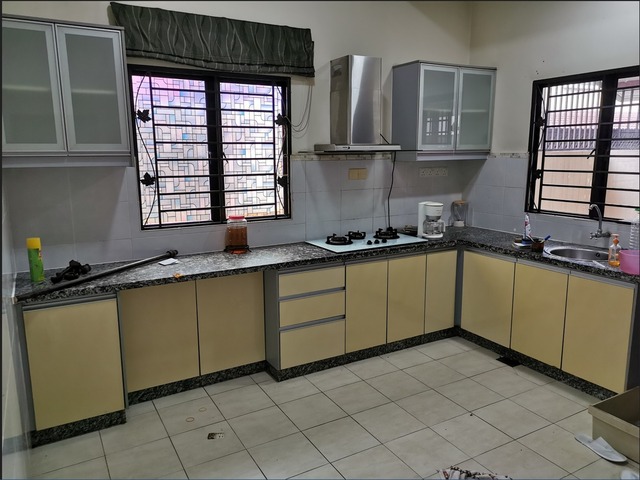
Kota Bayuemas
Jalan Bayu Impian
RM 1,800 /month
Listed on September 4, 2026
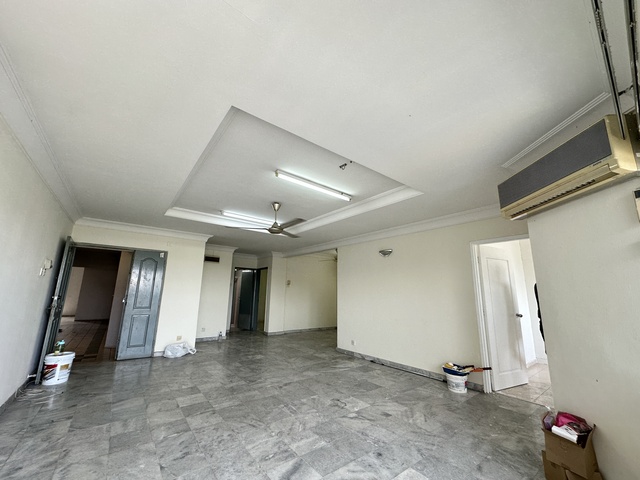
Endah Villa Condominium
Jalan 2/149B, Taman Sri Endah
RM 1,600 /month
Listed on August 24, 2026
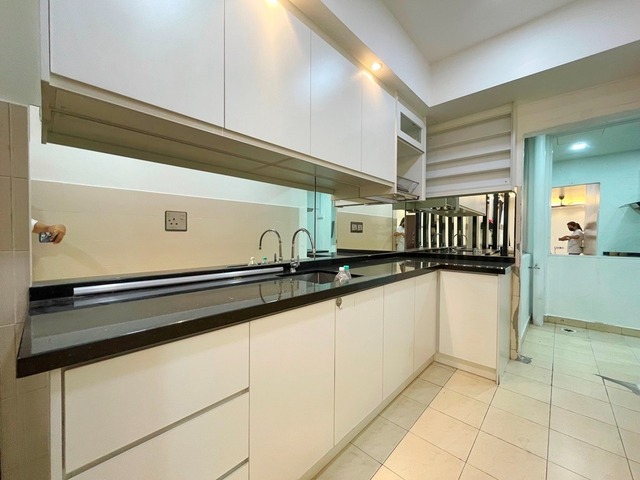
Pangsapuri Kasuarina
Bandar Botanik, Klang
RM 1,400 /month
Listed on April 23, 2026

Taman Sentosa Perdana
Lorong Temenggung 39
RM 575,000
Listed on October 21, 2024
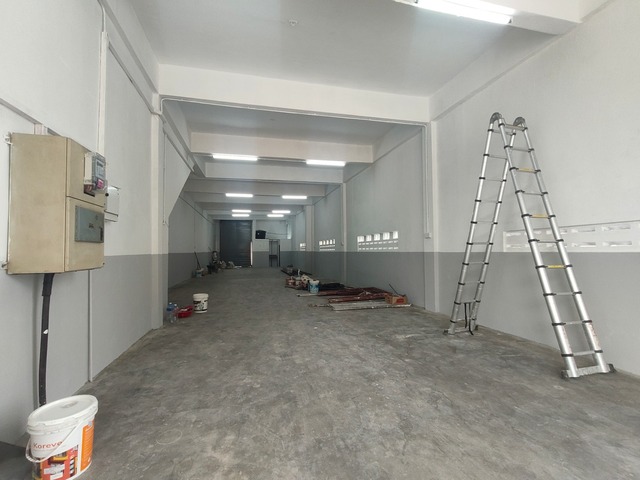
Taman Perindustrian Pandamaran
Pandamaran
RM 5,600 /month
Listed on August 14, 2026
Bandar Bukit Tinggi 1 Shop Apartment
Lorong Batu Nilam 1B
RM 199,998
Listed on March 31, 2026
Vista Bayu Apartment, Taman Bayu Perdana
Jalan Batu Unjur 9
RM 280,000
Listed on January 16, 2026
Taman Palm Grove
Leboh Siput
RM 619,980
Listed on October 30, 2025
Setia City Residences @ Setia City
Jalan Setia Dagang AH U13/AH
RM 749,998
Listed on December 2, 2025
Prima Bayu
Jalan Batu Unjur 9
RM 309,980
Listed on November 9, 2025

Apartment Hijau Ria
Jalan 2/1, Taman Kepong Indah
RM 288,000
Listed on February 25, 2025
Skyvilla, D Island Residence
Persiaran Utara
RM 1,450 /month
Listed on April 16, 2026

Bayu Tinggi
Jalan Bayu Tinggi Klang, Selangor
RM 1,450,000
Listed on April 22, 2025
BAYU PERDANA
Jalan Batu Unjur 1
RM 800 /month
Listed on April 5, 2026
Bandar Botanic
Jalan Jenaris
RM 1,180,000
Listed on March 12, 2026
Taman Orkid Desa
Jalan 15a/142, Taman Orkid Desa
RM 700 /month
Listed on September 4, 2026
Taman Telok
Jalan Dendang
RM 1,200 /month
Listed on April 4, 2026

Trefoil
Jalan Setia Dagang AH U13/AH, Setia City
RM 222,000
Listed on April 16, 2026

Pangsapuri Palma
Jalan Palma Raja 3/KS6, Bandar Botanic, Klang, 41200, Selangor
RM 155,000
Listed on August 29, 2024
Parkhill Residence
Jalan Teknologi 1
RM 540,000
Listed on March 30, 2026
Bandar Bukit Tinggi
Lorong Batu Nilam 11
RM 749,980
Listed on September 2, 2026
Bandar Bukit Tinggi
Lorong Batu Nilam 15
RM 1,600 /month
Listed on April 20, 2026

Taman Jaya Utama
Jalan Utama 4
RM 320,000
Listed on July 29, 2025
Pangsapuri Intan
Jalan Bukit Permai, Taman Bukit Permai
RM 238,000
Listed on June 24, 2025
Bandar Botanic
Jalan Cassia
RM 520,000
Listed on March 16, 2026
SS2 Petaling Jaya
Jalan SS2
RM 17,000 /month
Listed on September 14, 2026

Taman Sejati 5
Lorong Bendahara
RM 495,000
Listed on June 10, 2025

Bandar Puteri Klang
Jalan Pending
RM 649,980
Listed on November 22, 2024
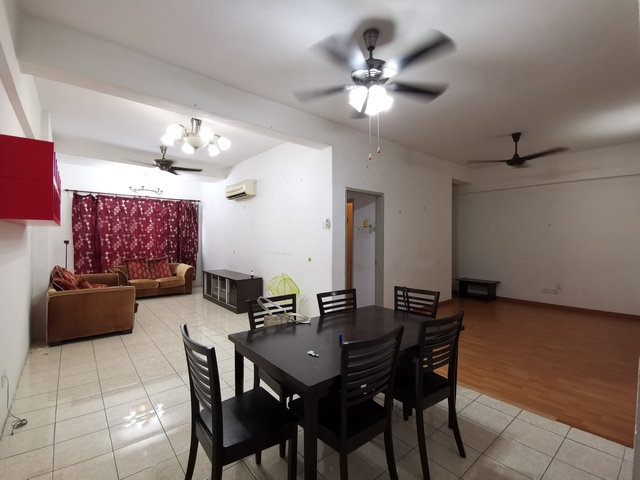
Millenium Place @ Millenium Square
Jalan 14/1, Seksyen 14
RM 499,980
Listed on December 29, 2025
Laman Impian Bandar Botanic
Bandar Botanic Klang
RM 370,000
Listed on September 4, 2026

Riana South
Persiaran Alam Damai, 56000, Kuala Lumpur
RM 680,000
Listed on May 27, 2025

Taman Bayu Perdana
Jalan Batu Unjur
RM 499,000
Listed on February 25, 2025
Trifolis Apartment
Jalan Batu Nilam 36/KS6
RM 1,450 /month
Listed on August 2, 2026
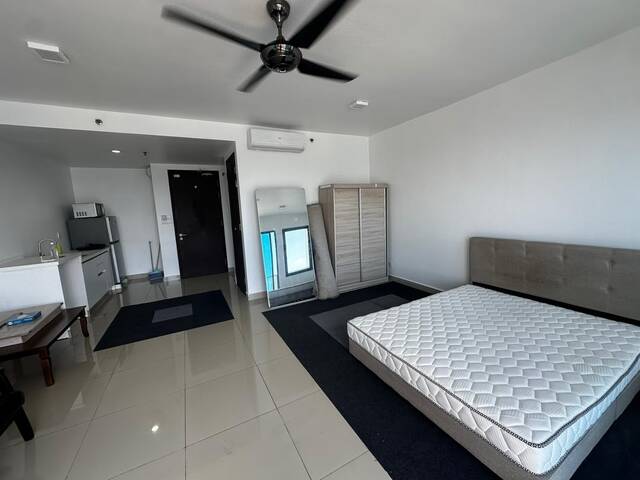
Trefoil Service Residence, Setia City
Jalan Setia Dagang AH U13/AH, Setia City
RM 1,200 /month
Listed on August 13, 2026
Impiria Residensi, Bandar Bukit Tinggi 2
Lorong Batu Nilam 16A/KS06
RM 3,300 /month
Listed on August 13, 2026
Bandar Parklands
Lorong Delima 4
RM 2,400 /month
Listed on July 31, 2026

Bandar Puteri Klang
Jalan Sanggul
RM 649,800
Listed on June 23, 2023
Bandar Parklands
Lorong Delima 4
RM 699,980
Listed on July 30, 2026
Laman Impian Bandar Botanic Klang
Bandar Botanic
RM 1,500 /month
Listed on August 26, 2026

Trifolis Apartment
Jalan Batu Nilam 36/KS6, 41200, Selangor
RM 335,000
Listed on April 15, 2025
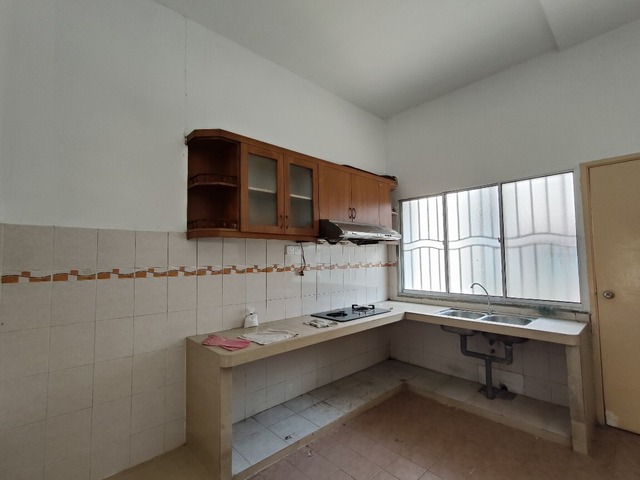
Bandar Puteri Klang
Jalan Kerongsang
RM 485,000
Listed on November 13, 2025
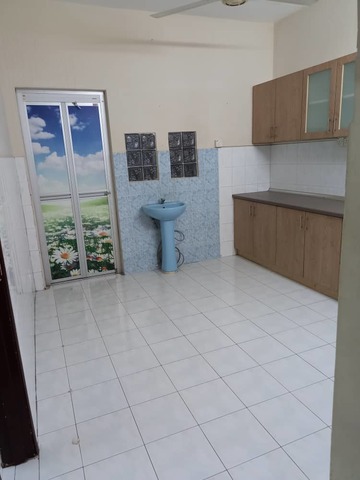
Bandar Bukit Tinggi
Lorong Batu Nilam 11
RM 598,000
Listed on April 22, 2024

Jalan Setia Utama U13/37M
Jalan Setia Utama U13/37M
RM 1,200,000
Listed on April 8, 2025

Bandar Puteri Klang
Jalan Pending
RM 579,980
Listed on February 20, 2025
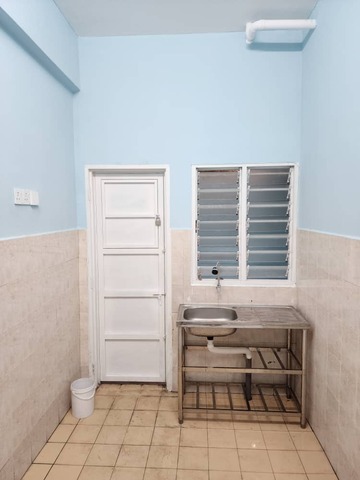
Taman Millenium, Sentosa
Jalan Hulubalang 37a
RM 129,980
Listed on December 5, 2025
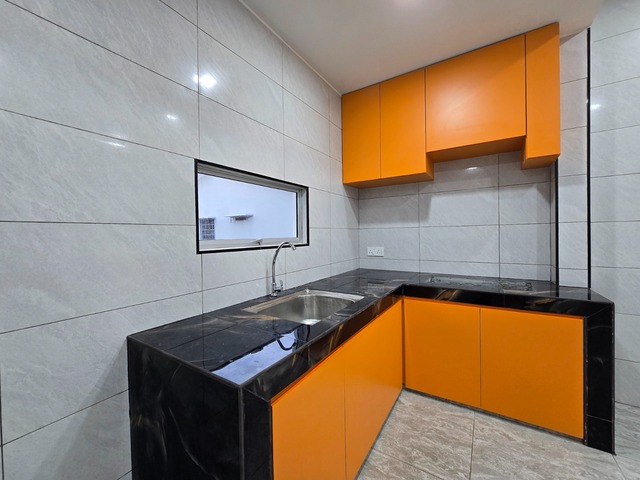
Taman Menara Maju, Klang
LORONG MANICKAVASAGAM
RM 438,000
Listed on August 14, 2026
La Vista
Jalan Tempua 2, Bandar Puchong Jaya
RM 449,980
Listed on June 24, 2025
Laman Impian Bandar Botanic Klang
Bandar Botanic Klang
RM 1,600 /month
Listed on August 26, 2026
Gravit8 @ Klang South
Kota Bayuemas
RM 1,300 /month
Listed on August 21, 2026
TRIO by Setia
Bukit Tinggi Klang
RM 2,000 /month
Listed on August 2, 2026
Golden Villa Apartment
Jln Temenggung 37, Taman Sentosa Perdana
RM 185,000
Listed on December 5, 2025

Taman Sentosa
Jalan Dato Abdul Hamid 18
RM 520,000
Listed on November 22, 2024

Residensi Alami
Jalan Tinju 13/50, 40100, Selangor
RM 450,000
Listed on April 28, 2025
Pangsapuri Kasuarina
Bandar Botanik, Klang
RM 265,000
Listed on August 18, 2026

Kota Bayuemas
Jalan Bayu Impian 15
RM 2,099,000
Listed on January 24, 2024
Taman Sri Jaromas
Jalan 3/4 Zinnia
RM 580,000
Listed on May 9, 2026

Eco Majestic
Lingkaran Eco Majestic
RM 1,200,000
Listed on June 4, 2025
TRIO by Setia
Bukit Tinggi Klang
RM 2,500 /month
Listed on July 16, 2026
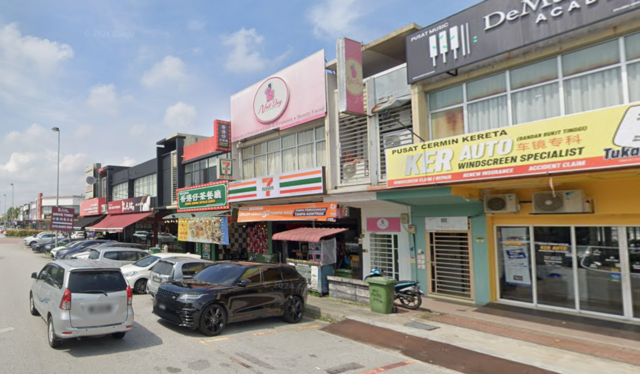
BANDAR BOTANIC, KLANG
Jalan Mahogani 1
RM 6,500 /month
Listed on July 8, 2026
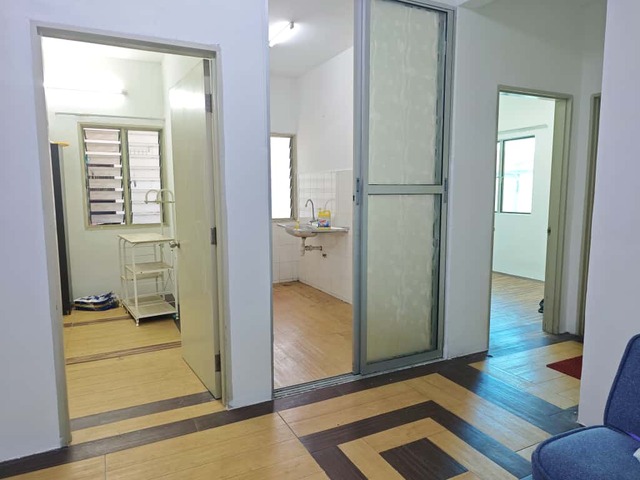
Pangsapuri Akasia, Bandar Botanic
Persiaran Kasuarina
RM 230,000
Listed on March 12, 2026
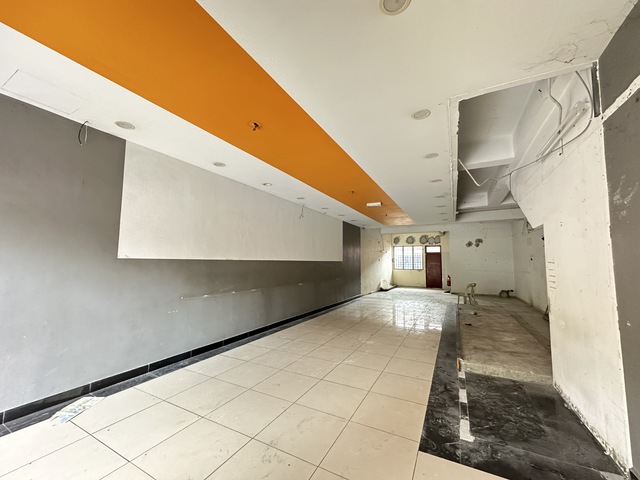
Telok Panglima Garang
Jalan Pahlawan 1
RM 2,300 /month
Listed on December 14, 2025
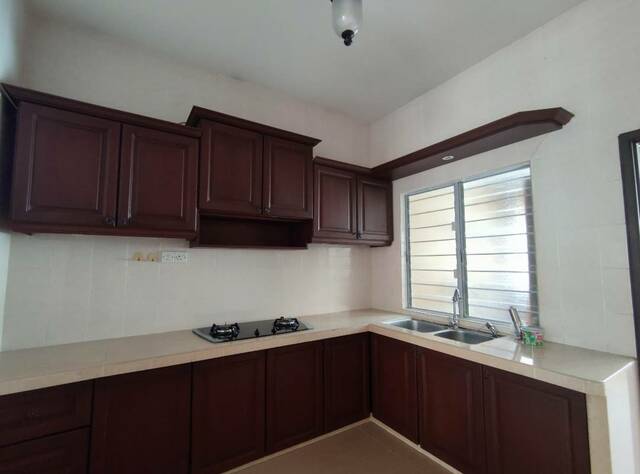
Bandar Botanic
Jalan Kiara
RM 679,000
Listed on January 9, 2026

Vista Indah Putra
Jalan Batu Unjur 8, 42000, Selangor
RM 270,000
Listed on November 20, 2024

Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur, 41200, Selangor
RM 258,000
Listed on May 20, 2025
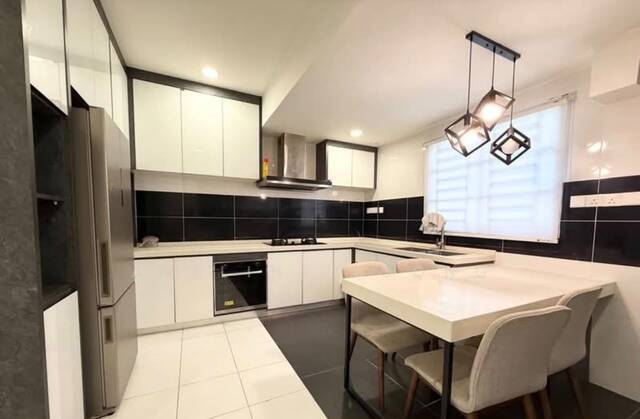
Bandar Botanic
Jalan Akasia
RM 3,000 /month
Listed on August 21, 2026
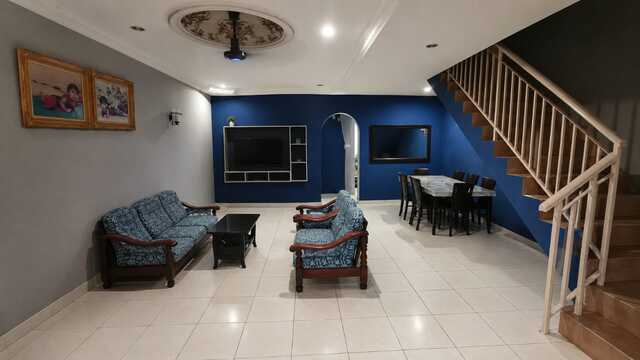
Taman Suria Pendamar
Jalan Selat Selatan 17/KS, Taman Suria Pendamar
RM 399,990
Listed on July 14, 2026
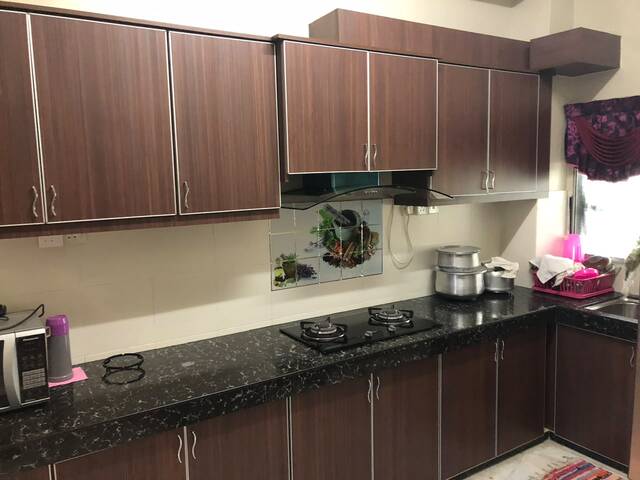
Taman Klang Indah
Jalan Samarinda
RM 1,600 /month
Listed on August 2, 2026
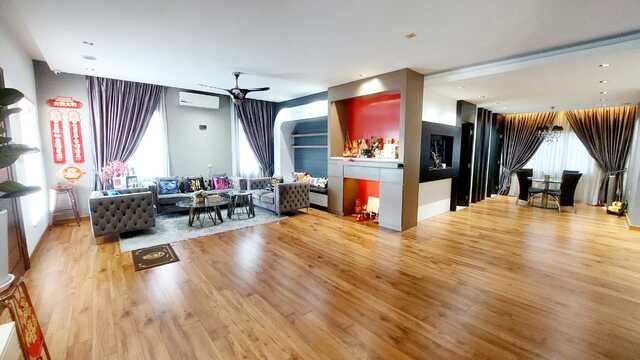
Taman Raja Nong
JALAN RAJA NONG
RM 900,000
Listed on August 21, 2026
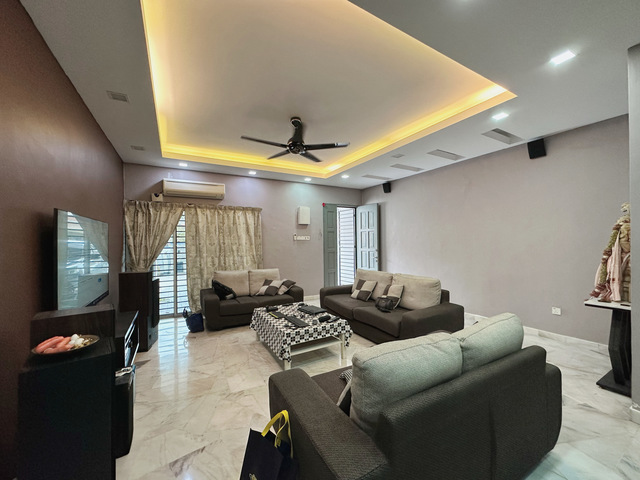
Taman Klang Indah
Lorong Samarinda 11F
RM 649,980
Listed on April 5, 2024

Taman Lembah Maju
Jalan Maju 2/7
RM 289,980
Listed on November 21, 2024
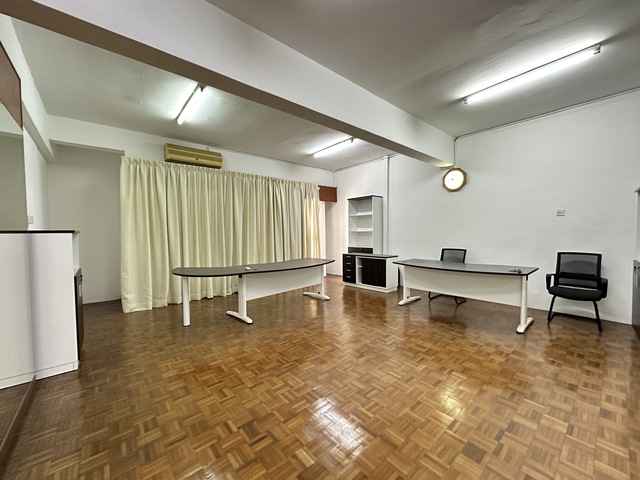
BAYU PERDANA
Jalan Batu Unjur 1
RM 1,800 /month
Listed on April 5, 2026
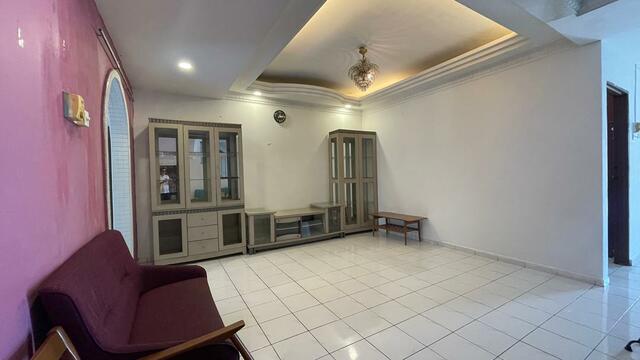
Bandar Bukit Tinggi
Lorong Batu Nilam 6
RM 1,900 /month
Listed on April 29, 2026
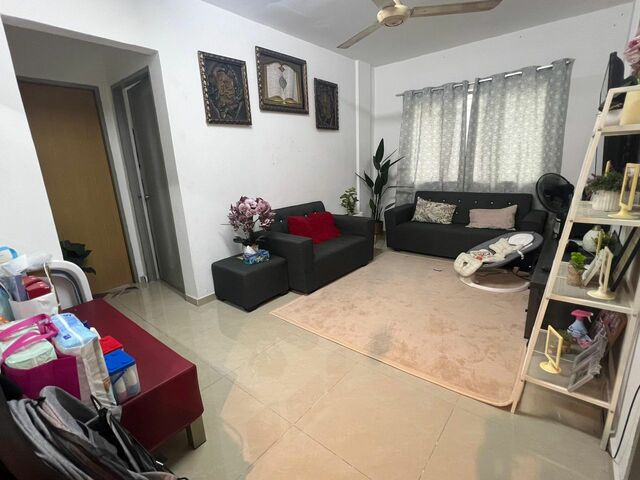
Bandar Bukit Tinggi 1 Apartment
Jalan Batu Nilam 15
RM 199,980
Listed on April 21, 2026
Bandar Puteri Klang
Jalan Gelang
RM 598,000
Listed on January 12, 2026
Taman Bayu Perdana
Jalan Batu Unjur
RM 500,000
Listed on July 1, 2025

Bandar Parklands
Lorong Kristal 5
RM 1,080,000
Listed on September 11, 2026
Kiara East
Jalan 3/18A Taman Mastiara
RM 478,000
Listed on February 27, 2026
Vista Bayu Apartment, Taman Bayu Perdana
Jalan Batu Unjur 9
RM 1,750 /month
Listed on December 5, 2025
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
RM 1,300 /month
Listed on August 21, 2026
Gravit8 @ Klang South
Jalan Bayu Laut
RM 1,800 /month
Listed on August 14, 2026

Taman Sentosa
Jalan Dato Yusof Shahbudin 1
RM 468,000
Listed on December 6, 2024

Desa Idaman, Taman Puchong Prima
Taman Puchong Prima Puchong
RM 449,800
Listed on October 13, 2025
Canary Garden @Bandar Bestari
Bandar Bestari KSL
RM 1,680,000
Listed on August 11, 2026
TAMAN PERWIRA, TPG
JALAN WIRA 2,TAMAN PERWIRA, TPG
RM 4,500 /month
Listed on July 27, 2026
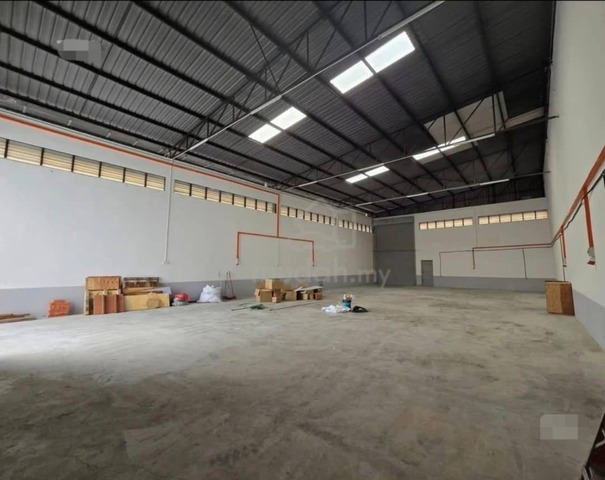
Taman Perindustrian Pandamaran
Sobena Jaya Pandamaran
RM 14,000 /month
Listed on August 14, 2026
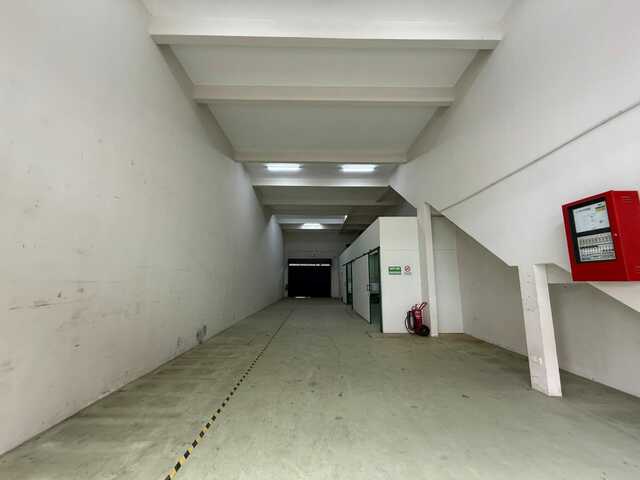
Kesas 32 Industrial Park
Jalan Sungai Jeluh 32/201
RM 7,700 /month
Listed on April 5, 2026
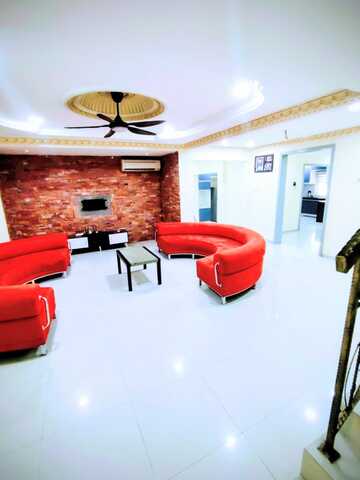
Bandar Putera
Jalan Kebun Nenas 2
RM 2,500 /month
Listed on August 1, 2026
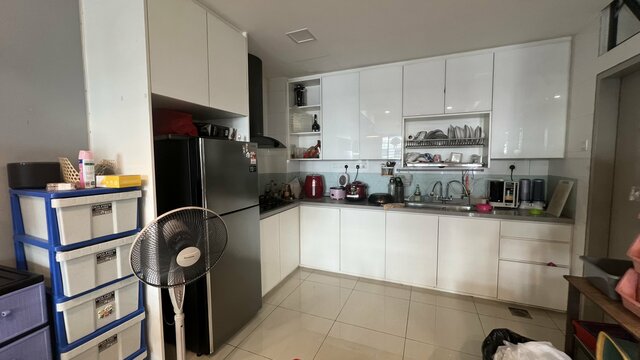
Andira Park
Lebuh Bukit Puchong
RM 800,000
Listed on November 10, 2025
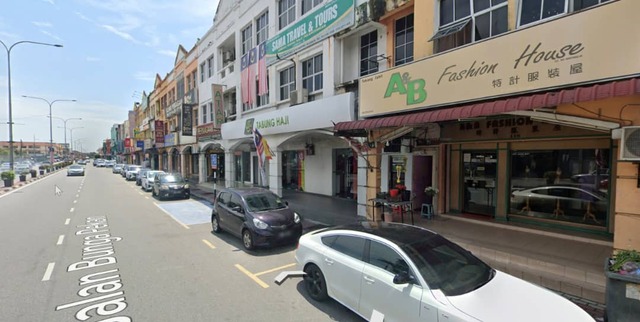
Jalan Bunga Pekan Banting
Jalan Bunga Pekan Banting
RM 3,800 /month
Listed on August 18, 2026
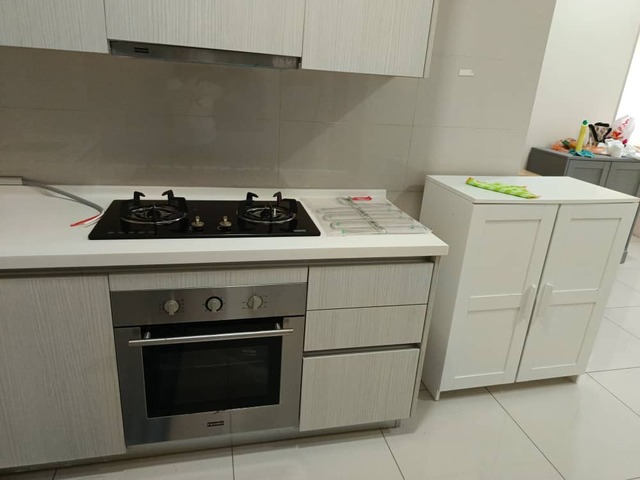
Green Residence
Jalan Sayang 1, Taman Rasa Sayang
RM 2,000 /month
Listed on April 20, 2026
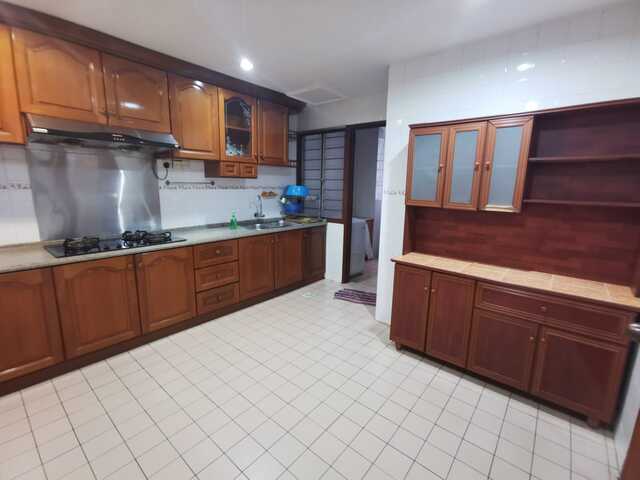
Dynasty Condominium
Jalan Batu Tiga Lama
RM 1,800 /month
Listed on August 19, 2026
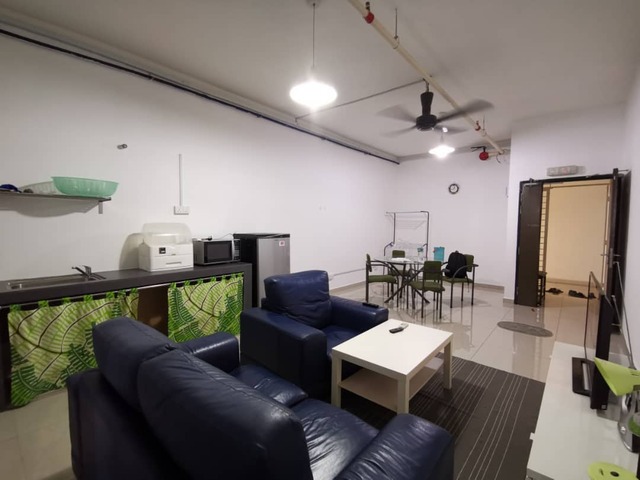
Avenue Crest
Section 22, Batu Tiga
RM 1,300 /month
Listed on April 6, 2026

Teluk Pulai
Jalan Teluk Pulai
RM 835,000
Listed on April 8, 2025
Avenue Crest
Section 22, Batu Tiga, Shah Alam
RM 210,000
Listed on March 30, 2026
Bandar Parklands
Lorong Delima 4
RM 749,980
Listed on September 4, 2026
Bandar Puteri Klang
Jalan Kerongsang
RM 580,000
Listed on March 30, 2026
Taman Perwira
Jalan Wira 4
RM 270,000
Listed on September 4, 2026

Livia @ Bandar Rimbayu
Jalan Fauna 3
RM 950,000
Listed on October 28, 2024
Residensi Heliks (Helix2 @ PJ South)
Jalan PJS 5/30, Taman Medan, Kampung Ghandi
RM 2,450 /month
Listed on September 10, 2026
Taman Sri Putra
Jalan Jelawat
RM 359,900
Listed on July 27, 2026
Vista Lavender Apartment
Bandar Kinrara
RM 1,800 /month
Listed on August 26, 2026
Taman Telok
Jalan Dendang
RM 439,980
Listed on February 3, 2026
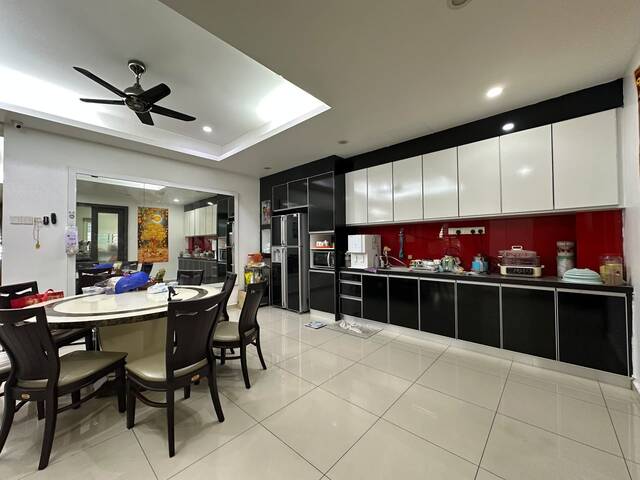
Bandar Parklands
Lorong Delima 16 Bukit Tinggi 3
RM 1,598,000
Listed on September 10, 2026

Putra Heights
Jalan Putra Bistari
RM 778,000
Listed on April 24, 2025
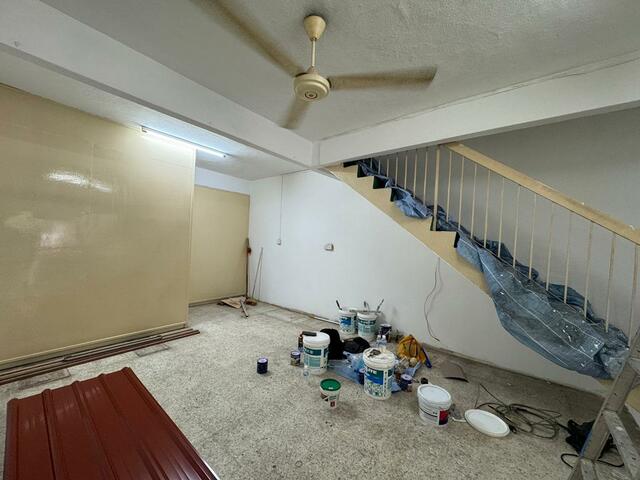
Taman Selat Damai
Off Jalan Jeti Pandamaran
RM 1,399 /month
Listed on April 6, 2026
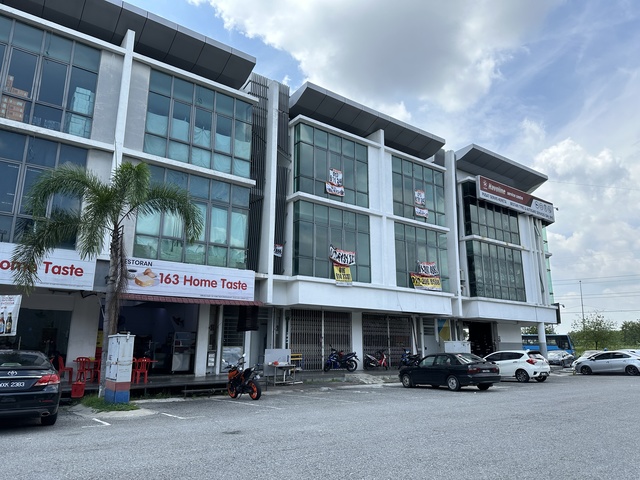
Bandar Bestari
Klang, Selangor
RM 1,800 /month
Listed on May 23, 2024

Taman Sutera
43000 Kajang
RM 5,500 /month
Listed on September 22, 2025
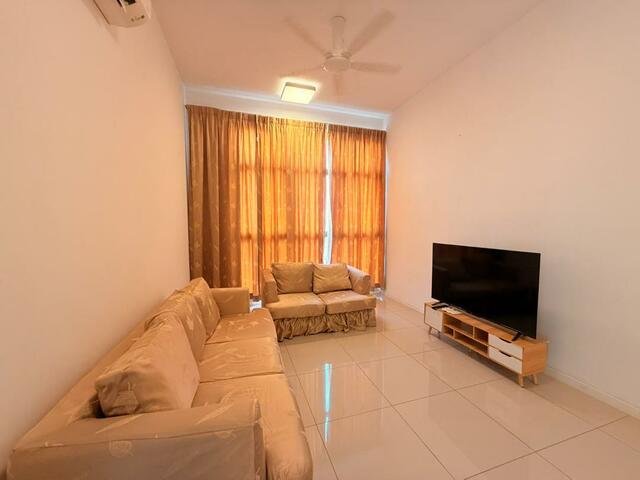
Waltz Residences @ Paradigm Garden City
Jalan Awan Besar
RM 790,000
Listed on November 27, 2025

GEO Bukit Rimau
Jalan Sungai Burung
RM 2,500 /month
Listed on March 19, 2025
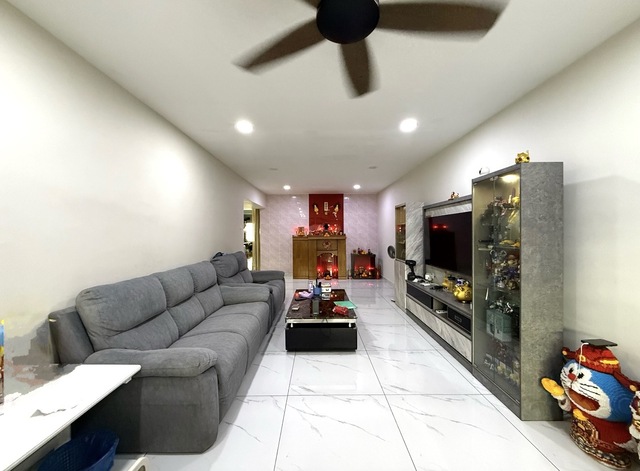
Taman Eng Ann, Klang
Eng Ann Klang
RM 609,980
Listed on July 31, 2026
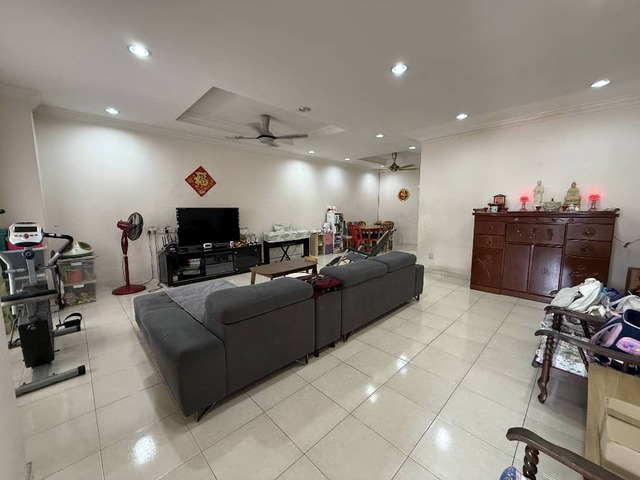
Teluk Pulai
Tepi Sungai
RM 705,000
Listed on September 22, 2025

Impiria Residensi
Lorong Batu Nilam 16A/KS06, Bandar Bukit Tinggi 2
RM 620,000
Listed on June 10, 2025
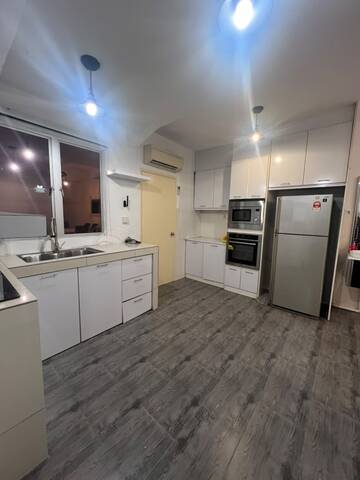
Bandar Botanic
Akasia
RM 2,800 /month
Listed on July 3, 2026
La Vista
Jalan Tempua 2, Bandar Puchong Jaya
RM 450,000
Listed on June 19, 2025
Setia Kota Bayuemas
Bayuemas Klang
RM 838,000
Listed on July 29, 2026
The Havre
Lebuhraya Bukit Jalil
RM 499,980
Listed on August 29, 2025

AraTre' Residences
Jalan PJU 1a/4a, Ara Damansara, 47301, Selangor
RM 775,000
Listed on March 4, 2025
NCT Smart Industrial Park
Kuala Langat
RM 33,500 /month
Listed on August 24, 2026
Bandar Puteri Klang
Jalan Kerongsang 7
RM 768,000
Listed on March 31, 2026
Taman Sentosa
Jalan Dato Yusof Shahbudin 30
RM 950 /month
Listed on August 26, 2026

Kekwa Apartment @ Putra Perdana
Bulatan Putra Perdana, Taman Putra Perdana, 47100, Selangor
RM 160,000
Listed on March 6, 2025
Bayu Villa Apartment, Bayu Perdana
Jalan Batu Unjur
RM 350,000
Listed on August 17, 2026
Merak Kayangan Court
Jalan Kapas
RM 7,500 /month
Listed on September 17, 2025

Taman Melawis (Taman Heng Luen)
Jalan Loyang; Jalan Emas; Jalan Besi
RM 499,980
Listed on October 29, 2024

Taman Sentosa
Jalan Dato Abdul Hamid 16A
RM 408,000
Listed on September 23, 2024

Saujana Damansara
Desa Riang, 47830, Selangor
RM 150,000
Listed on June 27, 2024
Bandar Putera
Jalan Kebun Nenas
RM 849,900
Listed on April 16, 2026
Taman Mesra
Jalan Bentara Samarinda
RM 779,980
Listed on July 31, 2026
Telok Gadong Besar
Lorong Bawal Tambak
RM 1,050,000
Listed on August 4, 2026
Gravit8 @ Klang South
Jalan Bayu Laut Bayuemas
RM 429,000
Listed on April 30, 2026
Robin @ Bandar Rimbayu
Jalan Fauna 3
RM 610,000
Listed on August 18, 2026
Central Residence, Sungai Besi
Jalan Sungai Besi
RM 390,000
Listed on June 19, 2025
Bandar Puteri Klang
Jalan Sanggul
RM 580,000
Listed on May 23, 2024
Taman Perindustrian Meru
Jalan Korporat
RM 11,350,000
Listed on August 1, 2026

Taman Sungai Besi Indah
Jalan Sb Indah 1/5
RM 398,000
Listed on June 17, 2025
Orchis Apartment, Bandar Parklands
Bandar Parklands
RM 290,000
Listed on August 24, 2026
Bandar Puteri Klang
Jalan Pending
RM 499,980
Listed on January 19, 2026
Bandar Puteri Klang
Lorong Gelang
RM 588,000
Listed on January 8, 2026
Bandar Puteri Klang
Jalan Pending
RM 635,000
Listed on October 19, 2025
ARANDA NOVA @ CAMERON SQUARE
A-5-5, THE RETREAT, CAMERON SQUARE@ARANDA NOVA
RM 396,000
Listed on August 18, 2026
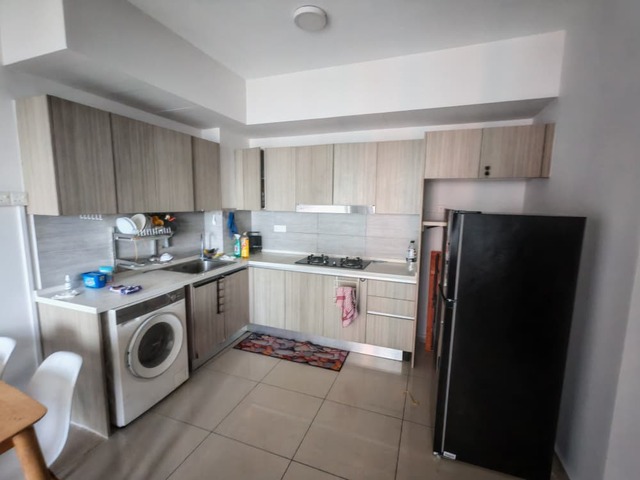
Gravit8 @ Klang South
Jalan Bayu Laut
RM 2,200 /month
Listed on September 2, 2026
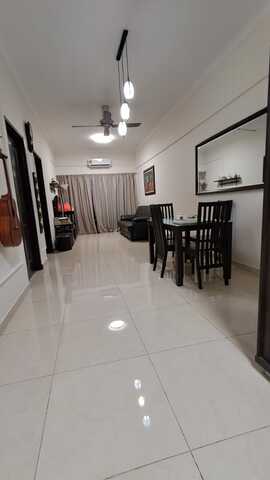
Prima Bayu
Jalan Batu Unjur 9
RM 339,980
Listed on April 22, 2026
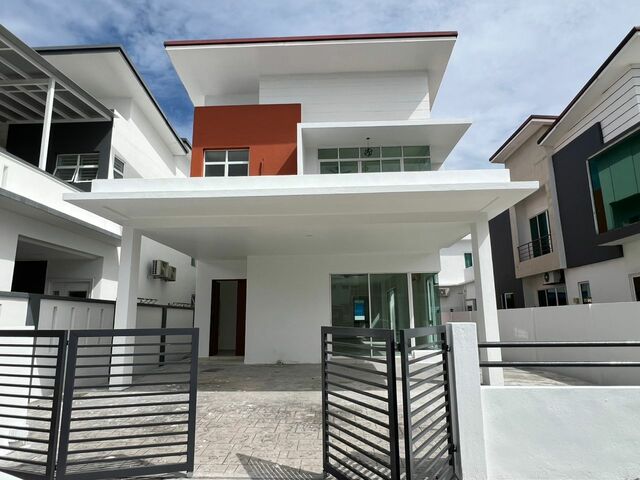
Taman Sri Jaromas
Jalan 3/14
RM 888,000
Listed on October 8, 2025
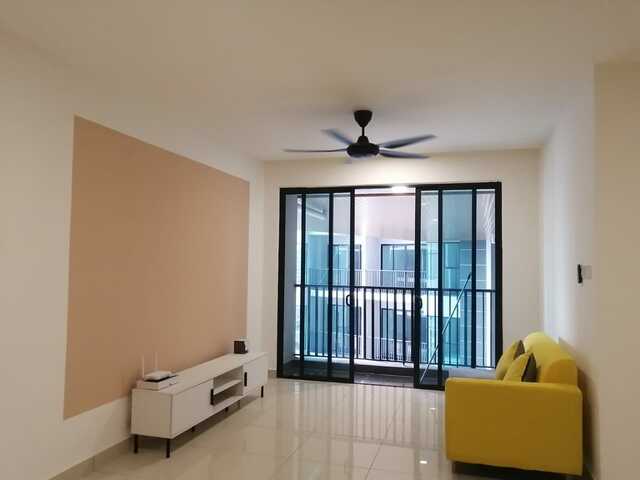
AraTre' Residences
Jalan PJU 1a/4a, Ara Damansara, 47301, Selangor
RM 780,000
Listed on March 24, 2025
Bangsar Hill Park
13, Lorong Maarof 1, Bangsar, 59000 Kuala Lumpur, Wilayah Persekutuan Kuala Lumpur
RM 6,250 /month
Listed on September 30, 2025
Ten Kinrara
Jalan BK 5a
RM 685,000
Listed on July 4, 2025
Laman Impian @ Bandar Botanic
Botanic Klang
RM 329,900
Listed on August 18, 2026
Taman Mesra Klang
Jalan Samarinda
RM 899,000
Listed on July 29, 2026
Taman Jaya Utama
Jalan Utama 6
RM 520,000
Listed on November 5, 2025
Bandar Parklands
Jalan Delima 4
RM 699,000
Listed on July 20, 2026
Prima Ria
Jalan Dutamas Raya
RM 419,980
Listed on November 3, 2025
Vista Bayu Apartment, Taman Bayu Perdana
Jalan Batu Unjur 9
RM 1,200 /month
Listed on April 15, 2026
Our newly launched projects
Discover the real estate properties in and around Selangor, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Located in Pulau Pinang
Regalway Industrial Hub (Commercial)
Starting from RM 3,828,000
Listed on January 23, 2026
 3 bedrooms unit
D' Hazelton
Farlim, Penang
Starting from RM 450,000
Listed on January 23, 2026
 1 - 2 bedrooms
G'Vinton
Jalan Sultan Ahmad Shah, Seksyen 13, Bandar Georgetown, D.T.L., Penang.
Starting from RM 560,000
Listed on January 23, 2026
 Exclusive area
d'Courtyards (2 storey terrace)
Bukit Mertajam, Penang, Malaysia
Starting from RM 688,000
Listed on October 3, 2024
 Near Recreational Park
The Retreat Condominium
Taman Seri Bukit Indah, 14000 Bukit Mertajam, Penang
Starting from RM 528,150
Listed on October 2, 2024
 Close to major highways
The Pier
The Pier, Jln Bayan Mutiara 1, 11900 Bayan Lepas, Penang
Starting from RM 781,800
Listed on October 2, 2024
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
The tenancy ended three weeks ago. Your tenant is still inside, and your calls go unanswered. Many landlords think the solution is simple: change the locks or cut the utilities. In Malaysia, both can put you on the wrong side of the law. What many landlords do not know is that you may have the right to claim double the rental value for every day a tenant stays beyond the tenancy period. This guide explains the legal steps to recover your property, what actions to avoid, the real timeline and costs, plus the tenancy clause that can help prevent this problem. Key Takeaways A landlord in Malaysia cannot remove a tenant personally. Possession must be recovered through the court under Section 7(2) of the Specific Relief Act 1950. Changing locks, cutting utilities, or removing belongings is illegal, even if stated in the tenancy agreement. Landlords may claim double rent for the holding-over period under Section 28(4)(a) of the Civil Law Act 1956, if done correctly through written notice. Writ of Possession recovers the property. Writ of Distress recovers unpaid rent (up to 12 months). They serve different purposes. Order 89 fast-track eviction does not apply to tenants who continue staying after the tenancy ends. Expect around 3 to 6 months for an uncontested case, and 12 months or longer if the tenant disputes it. Malaysia currently has no Residential Tenancy Act in force. Your stamped tenancy agreement remains your main legal protection. Table of contentsCan a landlord force a tenant to leave in Malaysia?What can a Malaysian landlord legally do, step by step?The Double Rent Rule Most Malaysian Landlords MissHow long does eviction take in Malaysia, and what does it cost?How to Prevent This from Happening AgainFrequently Asked Questions (FAQs) Can a landlord force a tenant to leave in Malaysia? No. The rule is stricter than most landlords expect. Section 7(2) of the Specific Relief Act 1950 requires a landlord to go to court when a tenancy has ended but the tenant remains in possession. You cannot take the property back yourself. The provision came into force on 31 January 1992, removing the old self-help remedy for this situation. Owning the property, unpaid rent, or a lockout clause does not change this. Section 7(2) overrides any contractual right to re-enter and change the locks, making such a clause unenforceable. There is another risk. Section 8 allows an occupier who you unlawfully dispossess to sue for possession. Change the locks yourself, and you could end up defending a court case while paying to put the tenant back in. What landlords cannot legally do ActionLawful?Your exposureChanging the locksNoUnlawful self-help, tenant may sue to recover possessionCutting water, electricity or gasNoUnlawful even with a clause permitting itRemoving the tenant's belongingsNoTrespass to goods, damages claimEntering without notice or consentNoBreach of quiet enjoymentPosting the tenant's details onlineNoPersonal data and defamation exposureServing a written notice to vacateYesRequired first step, keep proof of serviceFiling for possession in courtYesThe only lawful route to get the unit back One more misconception to clear up: the Tribunal for Consumer Claims does not handle residential tenancy disputes. A tenancy involves an interest in land, which falls outside the Tribunal’s jurisdiction. So, if your tenant refuses to leave, you cannot use the Tribunal as a cheap shortcut to recover possession. There is no small-claims route for getting your property back. You need to pursue the proper court process. What can a Malaysian landlord legally do, step by step? There are five steps, and the order matters. Jumping straight to legal action without preparing your documents can make the process slower and more expensive. Step 1: Build Your Case Before You Act Gather your stamped tenancy agreement, payment records, messages, and inventory list. Record the exact date the tenancy expired or ended. Check the stamping too. Under Section 52 of the Stamp Act 1949, an unstamped agreement cannot be admitted as evidence until you pay the required duty and penalty. Fixing this during a dispute can cost you valuable time. For the current e-Duti Setem process, see our guide to tenancy agreement fees and stamp duty. Step 2: Serve a Written Notice to Vacate Your notice should clearly state the parties involved, property address, relevant tenancy clause, outstanding amount if any, and deadline for vacant possession. Use a delivery method you can prove later. Send it by registered post to the tenant’s last known address, and use hand delivery or email if the tenancy agreement permits it. Keep every receipt and proof of delivery. Step 3: Claim Double Rent This is the step many landlords miss. Put the tenant on written notice that you are claiming double rent for the holding-over period. You can include this in the same letter. Step 4: Try One Proper Negotiation Not every dispute needs to reach court. If the tenant faces financial difficulty, offer a firm move-out date in exchange for waiving part of the arrears, but put every agreed term in writing. Compare that with months of litigation. A clean, documented exit can often save more time and money. Step 5: File for Possession and Enforce the Order If the tenant still refuses to leave, have your solicitor file a civil claim for vacant possession. The Magistrates’ Court handles claims up to RM100,000, while the Sessions Court handles claims up to RM1 million. Once the court grants possession and the tenant still refuses to leave, apply for a Writ of Possession. The court bailiff carries out the eviction, not the landlord. Even with a court order, do not change the locks or remove the tenant yourself. The Order 89 myth, correctedSeveral Malaysian guides tell landlords that Order 89 of the Rules of Court 2012 gives a 2 to 3 month fast-track. It does not apply to you. Order 89 is written for squatters and expressly excludes a tenant holding over after the termination of a tenancy. The Court of Appeal confirmed this in Cheow Chew Khoon v Abdul Johari [1995] 1 AMR 759. Budget for the ordinary action. A bad tenant costs more than a vacant unit. Screening, pricing and a properly drafted tenancy can keep you out of court in the first place. Before your next investment, make sure you choose a property with the right location, rental demand and tenant profile. Looking for a property with rental potential? Explore available homes with IQI. The Double Rent Rule Most Malaysian Landlords Miss Under Section 28(4)(a) of the Civil Law Act 1956, a tenant who stays after the tenancy ends can be charged double rent, at the landlord’s option, until they give up possession. That means you may claim twice the rent for every month the tenant continues to occupy the property, not just keep the deposit. The Federal Court confirmed the scope of this rule in Rohasassets Sdn Bhd v Weatherford (M) Sdn Bhd [2020] 1 MLJ 557. You do not need to prove the tenant acted badly or deliberately refused to leave. If you properly exercise the option, the court can allow the claim. What You Need to Do To claim double rent: The tenancy must have genuinely ended, through expiry or valid termination. You must not consent to the tenant staying. Accepting rent without objection could support an argument that a new periodic tenancy exists. You must demand that the tenant vacate. You must state your intention to claim double rent in your statement of claim, as held in Sebumi Magnetik Sdn Bhd v Twinsky Seafood Restaurant [2023] 5 MLJ 813. Example: How Double Rent Adds Up Say your rent is RM2,500 a month and the tenancy ends on 1 March. The tenant leaves seven months later, on 1 October. ClaimAmountOrdinary rent × 7 monthsRM17,500Double rent × 7 monthsRM35,000Additional amountRM17,500 One important point: double rent is based on the market rental value at the relevant time, not necessarily your old contractual rent. If market rents have increased, your potential claim could be higher. The Trap Nobody Flags: Your Two Remedies Can Conflict Landlords often use two separate remedies: a Writ of Distress to recover unpaid rent and a Writ of Possession to recover the property. But the timing matters. A distress claim depends on the landlord-tenant relationship, while double rent only arises after the tenancy has ended. So, ending the tenancy may strengthen your double rent claim while affecting your distress remedy. The right approach depends on the amount owed and whether the tenant has goods that can be seized. Speak to your solicitor before sending a termination or demand letter. Writ of DistressWrit of PossessionRecoversRent arrearsThe propertyLawDistress Act 1951, Order 75 ROC 2012Specific Relief Act 1950, civil suitLimitUp to 12 completed months of arrearsNo monetary capApplicationEx parteInter partesEnforced byCourt bailiff seizes movable goodsCourt bailiff removes occupierEvicts tenant?NoYes After a distress seizure, the tenant receives notice and has six days to settle the debt before the seized goods can proceed to auction. This can give landlords a practical route to recover outstanding rent without waiting for the full possession process. How long does eviction take in Malaysia, and what does it cost? StageTypical durationNotice to vacate and expiry14 days to 1 month, per your agreementFiling to first hearing1 to 3 months, depending on court loadOrder for possession, uncontestedAround 3 to 6 months from first noticeOrder for possession, contested12 months or moreWrit of Possession and bailiff executionAdditional weeks after the order Legal costs can add up quickly. A straightforward, uncontested eviction may cost around RM5,000 to RM15,000 in solicitor’s fees, plus a few hundred ringgit in court filing fees. Contested cases can cost more. The Cost Landlords Often Forget It is not the legal bill. It is the rent you lose while waiting. Juwai IQI data from more than 1,000 rental transactions across three central Kuala Lumpur postcodes found rents had stabilised at RM4,500 to RM5,000 since H2 2024. Co-Founder and Group CEO Kashif Ansari noted that rents in this segment had previously peaked at RM6,454 in H1 2024, a 58% year-on-year increase driven by luxury lettings, according to Free Malaysia Today on 22 April 2026. At RM4,750 a month, six months of delayed recovery means RM28,500 in lost rental income. Your loan instalment, maintenance fees, quit rent and assessment do not stop while the case runs. That is why a properly made double rent claim can make a significant difference. It is also why spending six weeks finding and screening the right tenant can cost less than rushing into a tenancy that ends in court. Not sure what your property should earn? Use our rental yield guide to pressure-test the numbers and read our rental income tax guide for what LHDN expects you to declare. How to Prevent This from Happening Again The best way to avoid an eviction dispute is to catch the warning signs before handing over the keys. Before You Hand Over the Keys Verify income, not just identity. Ask for three months of payslips or bank statements and confirm employment. Call the previous landlord. Ask about payment history, property care and how the tenant left. Collect the full deposit before handover. Do not treat the deposit as optional. Document the property. Photograph the unit and inventory, with date stamps, before handing over the keys. Stamp the tenancy agreement. Use e-Duti Setem on MyTax and check the current requirements and penalties before filing. An unstamped agreement may need to be regularised before it can be used as evidence in court. Four Clauses Every Landlord Should Get Right Termination clause: Set a clear notice period and cure period. Holding-over clause: Reserve the right to claim double rent under Section 28(4)(a) of the Civil Law Act 1956. Default clause: Clearly define what counts as a breach, such as three consecutive months of unpaid rent. Costs clause: Set out how enforcement and legal costs will be handled. A clause you never use costs little. A clause you needed but never included can cost months. For a broader overview, see our landlord and tenant rights and responsibilities guide. What About the Residential Tenancy Act? It is still not law. The Bill has been discussed since 2018, and KPKT described it as being in its final stages in August 2026. However, there is no parliamentary tabling date stated here. Until the Bill is passed, gazetted and brought into force, landlords continue to rely on the stamped tenancy agreement, Contracts Act 1950, Specific Relief Act 1950, Civil Law Act 1956 and Distress Act 1951. For now, your tenancy agreement is your first line of protection. Draft it accordingly. Frequently Asked Questions (FAQs) Can a landlord change the locks if the tenant refuses to leave in Malaysia? No. A landlord cannot change the locks to force out a tenant in Malaysia. Under Section 7(2) of the Specific Relief Act 1950, possession must be recovered through the court, not self-help. Can a landlord cut water or electricity to force a tenant out? No. A landlord cannot cut off water or electricity to force a tenant out. Any tenancy clause allowing this is unenforceable, and the landlord may be liable for doing so. How long can a tenant stay after the tenancy agreement expires? There is no fixed grace period. Once the tenancy expires, the tenant has no right to remain, but the landlord must obtain and enforce a court order to recover possession. Can I charge double rent if my tenant refuses to move out? Yes. Under Section 28(4)(a) of the Civil Law Act 1956, a landlord can claim double rent after the tenancy ends if the tenant stays without consent, is asked to vacate, and the landlord claims double rent in the court action. The Federal Court confirmed in Rohasassets v Weatherford [2020] 1 MLJ 557 that defiance by the tenant does not need to be proven. What is the difference between a Writ of Distress and a Writ of Possession? A Writ of Distress lets the bailiff seize and auction a tenant’s movable goods to recover up to 12 months of rent arrears. It does not evict the tenant. A Writ of Possession is used to recover the property and remove the tenant through the bailiff after a court order for possession. How much does it cost to evict a tenant in Malaysia? Solicitor's fees for a straightforward uncontested eviction suit typically run from around RM5,000 to RM15,000, with court filing fees of a few hundred ringgit. The larger cost is usually lost rent across the recovery period, plus any repair costs. This article is general information about Malaysian property practice and is not legal advice. Tenancy disputes turn on the specific wording of your agreement and the facts of your case. Speak to a qualified Malaysian solicitor before serving any notice or commencing proceedings. Finding a tenant is easy. Finding the right one is what matters. Before you hand over the keys, get the rent right, screen tenants properly, and have the paperwork handled from the start. Speak to an IQI agent about letting your property, with no pressure and no obligation. [custom_blog_form] Continue reading: 5 Things You Should Know About Tenancy Agreement in Malaysia Real Estate 101: A Guide to Tenancy Agreements in Malaysia Do I Need to Pay Tax on Rental Income? A Property Owner's Guide Damansara Rental Yield Guide for Property Investors Starting an Airbnb in Malaysia (2026): A Side-Hustler's Real-Life Guide Sources: Specific Relief Act 1950 (sections 7 and 8); Civil Law Act 1956 (section 28(4)(a)); Distress Act 1951 (section 5); Stamp Act 1949 (sections 47A and 52); Rules of Court 2012 (Orders 75 and 89); Subordinate Courts Act 1948; Rohasassets Sdn Bhd v Weatherford (M) Sdn Bhd [2020] 1 MLJ 557; Sebumi Magnetik Sdn Bhd v Twinsky Seafood Restaurant [2023] 5 MLJ 813; Cheow Chew Khoon v Abdul Johari [1995] 1 AMR 759; Free Malaysia Today, 22 April 2026; LHDN e-Duti Setem, MyTax; KPKT.
Kuala Lumpur, 15 September 2026 Juwai IQI has launched a Property Management Division that will use artificial intelligence to manage commercial properties across the 35 countries where the group operates. The division will be led by PMgr Arevind Pillai, a Property Manager registered with the Board of Valuers, Appraisers, Estate Agents and Property Managers (BOVAEP). He joins as Head of Juwai IQI Property Management with more than two decades of experience managing property and facilities portfolios for some of Asia's largest developers, asset managers and real estate consultancies. What the New Division Will Do The division covers the commercial property sector at launch, across a diverse portfolio of assets. It combines technology-driven operations, data-driven decision-making and industry best practice. The aim is higher operational efficiency, better asset performance and stronger long-term value for owners and investors. We will make the Division stand out by leveraging AI-powered tools to monitor, analyse, and optimise all critical building systems, enabling predictive maintenance, improved reliability, and enhanced operational efficiency. Kashif Ansari, Co-Founder and Group CEO, Juwai IQI From Reactive Repairs to Predictive Maintenance The division's model centres on continuous monitoring of critical building systems rather than scheduled inspection and after-the-fact repair. Four categories of infrastructure are covered at launch: air conditioning, typically the largest energy load in a commercial building, electrical systems, fire protection, and other essential building infrastructure. The difference lies in what triggers action. FactorReactive managementAI-monitored managementTrigger for actionEquipment fails or a tenant complainsData shows performance driftingMonitoringScheduled inspections, manual checksCore systems monitored around the clockTypical outcomeUnplanned downtime, emergency calloutsFaults addressed before they escalateBudget visibilityCosts appear after the eventOperating costs visible and planned ahead Two Decades in Asian Facilities Management Arevind Pillai joins from JLL, where he was Country Account Lead overseeing the HSBC Malaysia portfolio. He has also held senior positions at Knight Frank, CBRE GWS, Sime Darby Property, Kuwait Finance House, and Edgenta UEMS. He says too many teams in the industry fail to use their data, and that it remains common for managers to wait until something breaks before they act. We will watch the core systems around the clock and catch small faults long before they turn into a crisis. Our clients will also get real transparency and more control over their operating budgets. PMgr Arevind Pillai, Head of Property Management, Juwai IQI Extending the Relationship Beyond the Sale Juwai IQI already works with property owners, developers and asset managers on marketing and sales. The new division extends that relationship into the operating life of the asset. Commercial property is an intensely competitive industry. The most successful operators will be the ones with lower running costs, less downtime, and happier tenants. Daniel Ho, Co-Founder and Group Managing Director, Juwai IQI Running costs feed straight into asset performance. Lower costs and less downtime support net operating income, which underpins valuations as Malaysian property prices continue to rise. Occupiers feel the same efficiencies through their service charges and management fees. Juwai IQI provides expert insights into the property, economic and investment trends shaping markets locally and globally. Click below to get more expert property insights from our blog! MORE INSIGHTS
Version: CN, MY As of 3 September 2026, Bank Negara Malaysia (BNM) has maintained the Overnight Policy Rate (OPR) at 2.75%. The OPR has remained unchanged at this level since 9 July 2025, when BNM reduced the rate by 25 basis points from 3.00% to 2.75%. This means the OPR has now stayed at 2.75% for around 14 months. At its September meeting, BNM said the current monetary policy stance remains consistent with the goals of continued price stability and sustainable economic growth. Malaysia's economy also remains relatively resilient. GDP expanded by 5.7% in the first half of 2026, with BNM expecting full-year growth to reach around 5%. At the same time, inflation remains contained. During the first seven months of 2026: Headline inflation averaged 1.8% Core inflation averaged 2.0% These conditions give BNM room to keep the OPR unchanged while continuing to monitor inflation, domestic demand, and external risks. The next and final Monetary Policy Committee (MPC) meeting for 2026 is scheduled for 5 November 2026. What You Should Know About OPR in 20261. What is the Overnight Policy Rate (OPR)?2. What Does OPR Mean to Home Buyers and Businesses?3. How Does OPR Affect Your Housing Loan?4. Will the OPR Stay at 2.75%?5. Is This a Good Time To Buy a Home?Frequently Asked Questions (FAQs) 1. What is the Overnight Policy Rate (OPR)? Before we dive deeper, let's first understand what the OPR actually means. The Overnight Policy Rate (OPR) is an interest rate set by Bank Negara Malaysia (BNM) that influences the rates at which financial institutions lend funds to one another overnight. Banks experience varying levels of deposits, withdrawals, and lending activities every day, so their available cash reserves can fluctuate. A bank facing a cash shortage may borrow from another bank with excess funds to meet its short-term liquidity needs. The OPR provides a benchmark for these transactions and also plays an important role in influencing borrowing costs across Malaysia's financial system. a. Why Is the OPR System in Place? The OPR is one of BNM's main tools for managing the economy. By adjusting or maintaining the OPR, BNM can influence borrowing costs, spending, investment and inflation. For example, a lower OPR can make borrowing more affordable and encourage spending and investment. A higher OPR can help reduce excessive demand and inflation by making financing more expensive. However, strong economic growth does not automatically mean BNM needs to increase the OPR. What matters is whether stronger demand begins to create problems such as persistent inflation, excessive household borrowing, rapidly rising asset prices, or financial instability. For now, Malaysia's inflation remains relatively contained despite GDP growth of 5.7% in the first half of 2026. This is one reason BNM has been able to maintain the OPR at 2.75%. 2. What Does OPR Mean to Home Buyers and Businesses? For homebuyers and businesses, the September OPR decision mainly means financing conditions remain relatively stable. There is no new rate cut, but there is also no increase in borrowing costs caused by an OPR hike. a. When the OPR increases: Borrowing costs generally become higher. Floating-rate housing loan repayments may increase. Businesses may face higher financing costs. Loan affordability can become tighter for some borrowers. b. When the OPR decreases: Borrowing costs generally become lower. Monthly repayments on affected floating-rate loans may decline. Financing becomes more affordable. Lower borrowing costs can support household spending, property purchases and business investment. c. When the OPR remains unchanged, like the current 2.75%: Borrowers generally face more stable financing conditions. Existing floating-rate borrowers are less likely to see an OPR-driven change in repayments. Homebuyers have greater certainty when planning their monthly commitments. The current environment is also supported by Malaysia's resilient economy, stable labour market and ongoing investment activity. However, BNM continues to monitor risks such as higher global commodity prices, geopolitical tensions, and inflationary pressures. 3. How Does OPR Affect Your Housing Loan? For homeowners and property buyers, changes in the OPR can eventually affect the cost of servicing a floating-rate housing loan. a. Your monthly installment may change When borrowing rates rise, homeowners with floating-rate loans may need to pay higher monthly installments. When borrowing rates decrease, the opposite may happen, reducing monthly repayment commitments. With the OPR currently maintained at 2.75%, borrowers are not facing a fresh OPR-driven increase following the September 2026 meeting. b. Your repayment period may be affected Depending on the bank and the terms of your housing loan, a change in interest rates may affect either your monthly repayment amount, effective repayment period, or both. This is particularly relevant for floating-rate housing loans, where borrowing costs can move when benchmark rates change. To illustrate how a 0.25 percentage-point difference in loan interest rates can affect monthly repayments: Loan AmountAt 3.00% p.a.At 2.75% p.a.Estimated Monthly SavingsRM500,000RM1,924RM1,855RM69RM600,000RM2,309RM2,226RM83RM700,000RM2,694RM2,597RM97 The illustration assumes a 35-year loan term and is provided for comparison purposes only. The OPR is not the same as your actual housing loan interest rate. Actual rates, repayments and loan terms vary between banks and borrowers. For context, Malaysia's lowest-ever OPR was 1.75%, introduced in July 2020 during the COVID-19 pandemic. It remained at that level until May 2022. 4. Will the OPR Stay at 2.75%? For now, there appears to be limited pressure for BNM to change the OPR immediately. Malaysia recorded stronger economic growth of 5.7% in the first half of 2026, while headline and core inflation remained relatively contained at 1.8% and 2.0%, respectively, during the first seven months. Several economists and research houses therefore expect BNM to keep the OPR at 2.75% for the remainder of 2026, including at the final MPC meeting in November. Some economists believe the current rate could even remain in place into 2027 if inflation stays manageable and domestic demand grows at a sustainable pace. However, this is not guaranteed. Pressure for an OPR increase could become stronger if: inflation rises persistently; wage and household spending pressures accelerate; household borrowing increases rapidly; property prices rise excessively; or the ringgit comes under sustained pressure. On the other hand, a major slowdown in global trade or economic growth could change the outlook in the opposite direction. BNM has made it clear that future decisions will continue to depend on the balance between economic growth and inflation. 5. Is This a Good Time To Buy a Home? The current 2.75% OPR provides a relatively stable financing environment for homebuyers, but that does not automatically mean everyone should rush to purchase a property. Unlike July 2025, buyers are not receiving a fresh rate cut today. The advantage now is greater certainty because the OPR has remained unchanged for around 14 months. Malaysia's economy is also growing at a healthy pace, while inflation remains contained. This gives homebuyers a more stable environment when planning long-term financial commitments. For buyers purchasing a property for their own stay or as a long-term investment, the current environment can be favorable if your income is stable and the monthly repayment remains comfortably within your budget. However, the OPR should never be the only reason to buy. You should also consider your: monthly income and existing commitments; emergency savings; property location and future demand; down payment and upfront costs; and ability to continue servicing the loan if interest rates eventually increase. Overall, an OPR of 2.75% provides Malaysian homebuyers with greater financing stability, but the best time to buy is still when the property fits both your needs and your long-term financial capacity. Frequently Asked Questions (FAQs) a. What is Malaysia’s latest OPR in 2026? As of 3 September 2026, Bank Negara Malaysia has maintained the Overnight Policy Rate (OPR) at 2.75%. The rate has remained unchanged since 9 July 2025, when it was reduced from 3.00%. b. When is the next OPR announcement in Malaysia? The next and final Bank Negara Malaysia Monetary Policy Committee meeting for 2026 is scheduled for 5 November 2026. BNM will decide whether to maintain, increase, or reduce the OPR based on inflation, economic growth, and other financial conditions. c. Why did Bank Negara maintain the OPR at 2.75%? BNM considers the current rate appropriate for supporting sustainable economic growth while maintaining price stability. Malaysia’s GDP grew 5.7% in the first half of 2026, while headline and core inflation remained relatively contained at 1.8% and 2.0%, respectively, during the first seven months. d. Will the OPR stay at 2.75% for the rest of 2026? Several economists and research houses expect the OPR to remain at 2.75% for the remainder of 2026, including at the November MPC meeting. However, this is not guaranteed, as BNM will continue monitoring inflation, domestic demand, global economic conditions, and financial risks. e. How does the OPR affect housing loan repayments? The OPR can influence banks’ lending rates, particularly for floating-rate housing loans. If borrowing rates rise, monthly repayments may increase, while lower rates can reduce repayments. Since the OPR is currently unchanged, borrowers are generally not facing a new OPR-driven increase in monthly installments. f. Does an unchanged OPR mean all home loan interest rates will stay the same? Not necessarily. The OPR is an important benchmark, but each bank determines its own lending rates based on funding costs, borrower risk, loan packages, and other factors. Fixed-rate loans are also generally unaffected by short-term OPR movements, while floating-rate loans are more sensitive to changes in benchmark rates. g. Is a 2.75% OPR good for property buyers in Malaysia? A 2.75% OPR provides a relatively stable financing environment, helping buyers plan their monthly commitments with greater certainty. However, buyers should still consider their income, existing debts, down payment, emergency savings, property location, and ability to handle higher repayments if interest rates increase in the future. It's high time we started investing, so if you're interested in connecting with property industry experts, drop us your details and we will connect you as soon as possible! [custom_blog_form] Continue reading: Penang 2030: Why Malaysia’s Silicon Valley of the East Is Becoming a Strategic Investment Hub MM2H UAE: Is Living in Malaysia Better Than Dubai in 2026? Can a Non-Bumi Buy a Bumi Lot in Malaysia? 2026 Guide
14 Sep, 2026
Best Housing Loan Rates to Secure in September 2026
Finding the best house loan interest rates in Malaysia can be challenging, particularly with the numerous options available. Critical terms such as home loan, housing loan, and loan tenure are essential for making informed decisions. This guide will help you navigate the various loan types, their interest rates, and other key factors to consider when searching for your dream home. In September 2026, several financial institutions in Malaysia offered competitive home loans and other financing options. Here's a quick overview: 1. Best Housing Loan Rates in September 2026 Bank NameHouse Loan NameInterest / Profit RateFinancing TypeTenureLock-In PeriodMBSBProperty Refinancing-i and Remortgage-ifrom 2.75% p.a.Full Term islamic financingUp to YearNoneHong LeongHousing Guarantee Schemefrom 2.75% p.a.Term loanUp to 35 yearsNoneMaybank IslamicHouzKEYfrom 2.88% p.a.Term Islamic financingUp to 35 years1 YearBank IslamBaiti Home Financing-ifrom 3.55% p.a.Term Islamic financingUp to 35 yearsNoneBank of ChinaHousing Loanfrom 3.88% p.a.Term loanUp to 35 years3 YearsSource: Ringgitplus These banks offer a range of housing and home loans that cater to different needs, whether you're looking for a flexible or a term loan. Understanding Housing Loan Rates: 1. Best Housing Loan Rates in September 20262. Understanding the Effective Lending Rate (ELR)3. Understanding House Loan Interest Rates4. How Should You Compare Lending Rates Across Banks as Borrowers?5. How to Plan and Compare Your House Loan Interest Rates?Critical Terms in Home Financing 1. MBSB Property Refinancing-i and Remortgage-i MBSB Property Refinancing-i and Remortgage-i are Islamic refinancing and remortgage facilities for homeowners who want to refinance their property or take cash out, using their home as collateral. It offers a floating profit rate of 2.75% p.a., a financing margin of up to 90%, and no processing fee. The Product Disclosure Sheet also states that the facility is based on Tawarruq, and the monthly installment may change if the SBR/OPR changes. a. Requirements RequirementDescriptionMinimum Age18 to 65 years oldWho Can ApplyAny nationalityEmployment TypeSalaried employees and self-employed applicants are eligibleFinancing TypeFull-term Islamic financingProfit TypeFloating profit rateProfit RateFrom 2.75% p.a.Profit Rate CeilingCapped at 11% p.a.Margin of FinanceUp to 90%Security RequiredThe property will be used as security for the financingTenureUp to a year b. Fees & Charges Fees & ChargesDescriptionProcessing FeeNo processing feeCompensation Charge1% per annum Ta’widh compensation charge will be imposed on the outstanding installment amountRedemption Letter FeeRM50 per requestLetter for EPF Withdrawal FeeRM50 per requestCredit TakafulRequired from MBSB Bank’s panel Takaful provider or another approved Takaful providerAdditional SecurityTerm Deposit-i may be requested depending on credit assessment c. Benefits BenefitDescriptionLow Starting Profit RateOffers a starting profit rate from 2.75% p.a., which is one of the lowest among the listed bank loan optionsHigh Financing MarginAllows financing of up to 90%, which can help homeowners access more value from their propertyIslamic Financing StructureBased on the Shariah concept of Tawarruq, suitable for borrowers looking for Islamic refinancingNo Processing FeeHelps reduce upfront application costSuitable for Refinancing or RemortgageUseful for homeowners who want to restructure their existing property loan or access cash from their property valueOpen to More ApplicantsAvailable to any nationality, including salaried employees and self-employed applicants For more information, please visit the MBSB Bank website. MBSB Property Refinancing-i and Remortgage-i Product Disclosure Sheet 2. Hong Leong Housing Guarantee Scheme The Hong Leong Housing Guarantee Scheme is a government-guaranteed home loan under SJKP for eligible first-time Malaysian home buyers, including salaried employees and non-fixed-income earners. It offers financing of up to 100%, with interest rates from 2.75% p.a. and tenure up to 35 years. The Product Disclosure Sheet states that this facility is calculated on a variable-rate basis, and that the property will be used as security for the bank. a. Requirements RequirementDescriptionMinimum Age18 years oldWho Can ApplyMalaysians onlyBuyer TypeFirst-time home buyersEmployment TypeSalaried employees and self-employed applicantsIncome TypeSuitable for fixed-income and non-fixed-income earners, including gig workers, traders, farmers, and fishermenProperty PurposeProperty must be for own occupationEligible Property TypeNew, sub-sale, auctioned, completed or under-construction residential propertiesNot EligibleLand purchase or construction financingLoan TypeTerm loanInterest TypeFloating interest rateInterest RateFrom 2.75% p.a. for borrowing up to RM500,000Margin of FinanceSuitable for fixed-income and non-fixed-income earners, including gig workers, traders, farmers and fishermenMaximum Financing AmountUp to RM500,000, inclusive of MRTA/MRTT, LTHO, solicitor’s fees and valuation feesTenureUp to 35 yearsCredit ConditionTotal monthly loan repayment should not exceed 65% of gross monthly incomeCredit RecordCCRIS should not show arrears of more than 2 months within any 12-month period, with no adverse credit record within the last 24 monthsIncome Documents for Non-Fixed Income EarnersBank statements, business license, fisherman’s registration card, or confirmation letter from authorized bodies such as JKKK, Penghulu, Category A government servants or elected representatives b. Fees & Charges Fees & ChargesDescriptionProcessing FeeWaived, subject to changeEarly Settlement FeeNot applicable because there is no lock-in periodLate Payment Fee1% p.a. on the outstanding amount in arrearsEscalating Late ChargesAdditional charges may apply for repeated or prolonged defaultWithdrawal FeeNot applicable because this is a term loanRedemption Letter FeeRM50 per requestLetter for EPF Withdrawal FeeRM20 per requestInsurance or Takaful CoverageRequired for residential properties under houseowner policy or takaful coverage, according to the PDSGovernment TaxesAll fees are subject to prevailing government taxes where applicable c. Benefits BenefitDescriptionLow Starting Interest RateOffers interest rates from 2.75% p.a., making it one of the lowest options in the provided listUp to 100% FinancingHelps eligible buyers reduce the need for a large upfront depositSuitable for Non-Fixed Income EarnersDesigned for applicants who may not have formal payslips, such as gig workers, small traders, farmers and fishermenGovernment Guarantee SupportBacked by SJKP, which helps eligible applicants access financing even if they may not qualify through normal loan channelsLong Loan TenureTenure of up to 35 years can help reduce monthly repayment pressureTwo-Generation FinancingAllows a child to join as a borrower to extend the loan tenure, subject to approvalNo Lock-In PeriodBorrowers can settle the loan early without early redemption or settlement feeFinancing Can Include Related CostsMRTA/MRTT, LTHO, solicitor’s fees and valuation fees can be included within the RM500,000 financing ceilingFirst-Home Buyer FriendlySuitable for Malaysians buying their first home for own stayMultiple Repayment ChannelsRepayment can be made through standing instruction, HLB Connect, IBG transfer, ATM transfer, deposit machine or branch counter For more information, please visit the Hong Leong Bank website. Hong Leong Housing Guarantee Scheme Product Disclosure Sheet 3. Maybank Islamic HouzKEY Maybank Islamic HouzKEY is an Islamic homeownership solution designed to help Malaysian buyers own a home with a lower upfront cost and greater cash-flow flexibility. It offers up to 100% financing, no down payment, and a profit rate from 2.88% p.a., with a tenure of up to 35 years or until age 70, whichever comes earlier. The Product Disclosure Sheet states that HouzKEY is based on the Shariah concept of Ijarah Muntahiyah Bi Tamlik, a lease contract that ends with ownership transferred via sale. a. Requirements RequirementDescriptionMinimum Age18 to 70 years oldWho Can ApplyMalaysian citizens onlyBuyer TypeSuitable for first and second home Malaysian buyersHome Financing LimitApplicant must not have more than one home financing, including HouzKEY, at the point of applicationEmployment TypeSalaried employees and self-employed applicantsGuarantorsUp to 3 guarantors are allowedGuarantor RequirementGuarantors must be immediate family members, such as spouse, parents, siblings, or childrenGuarantor AgeGuarantors must be between 18 to 70 years oldFinancing TypeTerm Islamic financingProfit TypeFloating profit rateProfit RateFrom 2.88% p.a.Eligible Property PriceRM250,000 to RM2,000,000Margin of FinanceUp to 100%TenureInitial tenure of 5 years, with flexibility to continue up to another 30 yearsMaximum TenureUp to 35 years, or up to age 70, whichever is earlierEligible LocationsSelected projects in Kuala Lumpur, Selangor, Johor and PenangEligible Property TypeSelected properties from Maybank’s partnering developers, including new launches, under-construction and completed properties b. Fees & Charges Fees & ChargesDescriptionProcessing FeeNo feeDown PaymentNo down payment requiredSecurity Deposit3 months refundable security deposit is required upon signing the HouzKEY Agreements and SPAEarly Settlement FeeNo feeCompensation Charge1% p.a. on the outstanding amountLate Payment Charges1% p.a. on the monthly payment amount in arrears or any other approved amount by BNMLegal Fees for SPALegal fee based on the Solicitor’s Remuneration Order and disbursement, if not absorbed by the developerStamp Duty for SPANominal stamp duty of RM10 per copy, with four copies to be stampedLegal Fees for Home Financing AgreementLegal fee based on the Solicitor’s Remuneration Order and disbursementStamp Duty for Home Financing AgreementBased on Stamp Act requirement for the original copy, with RM10 nominal stamp duty for each duplicate copyLegal Fees for Deed of TrustRM300Legal Fees for Power of AttorneyRM300Legal Fees for Purchase UndertakingRM150Notice of SettlementRM50Property Maintenance CostsUtilities, fire takaful, quit rent, assessment fee, maintenance fee and other related property payments are borne by the buyer during the tenure, where applicableTakaful CoverageFire Takaful is encouraged, while Family Takaful or Life Insurance is optional but recommended c. Benefits BenefitDescription100% FinancingAllows eligible buyers to finance the full property price without a down paymentLower Upfront CostBuyers only need to prepare a 3-month refundable security deposit, subject to terms and conditionsNo Payment During ConstructionBuyers do not need to make payment during the construction period until the key or vacant possession is handed overLow Starting Profit RateOffers a profit rate from 2.88% p.a., subject to Maybank’s approval and assessmentFlexible TenureStarts with a 5-year initial tenure and can be extended up to another 30 yearsCash Flow FriendlyMonthly payment during the initial tenure is structured as profit payment only, helping reduce monthly payment pressureUp to 3 Guarantors AllowedApplicants can strengthen their application by including up to 3 immediate family members as guarantorsSuitable for New or Under-Construction HomesAvailable for selected new launches, under-construction and completed properties from participating developersOption to Continue After Initial TenureBuyers may continue with HouzKEY after the initial tenure without paying a new down payment, subject to the bank’s termsOption to Buy, Refinance or SellAfter fulfilling the required period, buyers may buy the property, refinance with Maybank Islamic or other banks, or sell the property to settle the outstanding amount Visit Maybank website for more information Maybank Islamic HouzKEY Product Disclosure Sheet 4. Bank Islam Baiti Home Financing-i Bank Islam Baiti Home Financing-i is an Islamic home financing facility for Malaysians who want to buy a residential property, whether under construction or completed. It is based on the Tawarruq Shariah concept, with a floating effective profit rate of up to 3.55% p.a., a financing margin of up to 90%, no processing fee, and no lock-in period. The Product Disclosure Sheet also states that the financing is for residential property purchase, with the Effective Profit Rate calculated on a variable or floating rate basis a. Requirements RequirementDescriptionMinimum Annual IncomeRM24,000Minimum Age18 to 70 years oldWho Can ApplyMalaysians onlyEmployment RequirementApplicant should be employed or own a business for at least 3 yearsCredit RequirementApplicant should not be bankrupt or involved in legal actionPayment Track RecordMinimum 1 year of good payment track recordFinancing TypeTerm Islamic financingShariah ConceptTawarruqProfit TypeFloating profit rateProfit RateFrom 3.80% p.a. for property value above RM300,000Rate for Property RM300,000 and BelowFrom 4.10% p.a.Margin of FinanceUp to 90%TenureUp to 35 yearsApproval TimeAround 30 days, subject to Bank Islam’s approvalEligible PropertyResidential property, including under-construction or completed propertyCollateralThe financed property will be used as collateralGuarantorMay be required on a case-by-case basis, depending on credit assessmentRequired TakafulMRTT or MLTT is compulsoryOptional TakafulHouseowner or Householder Takaful Plan, if applicable b: Fees & Charges Fees & ChargesDescriptionProcessing FeeWaivedEarly Settlement FeeNo lock-in period. Bank Islam shall grant Ibra’ on deferred profit after full settlementCompensation Charge1% p.a. on overdue installments before maturity until full paymentCharge After MaturityBased on the prevailing daily overnight Islamic Interbank Money Market Rate on the outstanding balanceRedemption Letter FeeRM50 per requestLetter for EPF Withdrawal FeeRM20 per request for manual application, RM10 per request for online applicationStamp DutyBased on Stamp Duty Act 1949Disbursement FeeIncludes registration of charge and other related chargesValuation FeeApplicable for completed property or own construction by appointed contractorWakalah FeeRM25 for Appointment of the Bank as Purchase Agent and RM25 for Appointment of the Bank as Sales AgentLegal FeesLegal fees and incidental expenses related to security documentationCustodian FeeRM80 annually for safekeeping of security documents after the facility is fully settledCopy of Security DocumentsRM50 per requestCancellation FeeCustomer must pay costs incurred by the bank for preparation and registration of security documents, if the facility is canceledTakaful ContributionBased on the contribution amount required by the Takaful operatorMRTT or MLTTCompulsory coverage for the financing facilityHouseowner or Householder TakafulApplicable if required c. Benefits BenefitDescriptionCompetitive Profit RateOffers a profit rate from 3.80% p.a. for property value above RM300,000High Financing MarginAllows financing of up to 90% of the property valueLong Financing TenureTenure of up to 35 years can help make monthly installments more manageableNo Processing FeeReduces upfront application cost for borrowersNo Lock-In PeriodBorrowers can settle the financing early without being tied to a lock-in periodNo Early Settlement PenaltyBank Islam grants Ibra’ on deferred profit after full settlementIslamic Financing StructureSuitable for buyers looking for Shariah-compliant home financing based on TawarruqSuitable for New and Completed HomesCan be used for residential properties that are under construction or already completedStep Up Payment SchemeAvailable for eligible first-time home buyers, allowing them to pay only the profit portion during the Step Up periodProfit Rate ProtectionThe Bank’s Sale Price is based on the Ceiling Profit Rate, while the Effective Profit Rate is floatingTakaful ProtectionMRTT or MLTT helps protect the borrower and family in the event of death or total permanent disability You may visit the Bank Islam website for more information. Bank Islam Baiti Home Financing-i Product Disclosure Sheet 5. Bank of China Housing Loan Bank of China Housing Loan is a conventional term loan for buyers who want to finance a completed or under-construction residential property in Malaysia, or refinance an existing housing loan. It offers a floating interest rate from 3.88% p.a., with financing margin of up to 90% and tenure of up to 35 years. The Product Disclosure Sheet states that the Housing Loan is a secured loan, and the residential property will be used as security to the bank. a. Requirements RequirementDescriptionMinimum Annual IncomeRM60,000Minimum Monthly IncomeRM5,000Minimum Age18 to 70 years oldWho Can ApplyMalaysians, permanent residents and foreigners working in MalaysiaForeigner RequirementForeigners must have valid passport, visa, work permit or employment passEmployment TypeSalaried employees and self-employed applicantsLoan TypeTerm loanInterest TypeFloating interest rateInterest RateFrom 3.88% p.a.Loan AmountMinimum loan amount from RM300,000Eligible Borrowing RangeMore than RM300,000Margin of FinanceUp to 90% of the SPA price or market valueTenureUp to 35 yearsLock-In Period3 yearsEligible PropertyResidential property, including completed or under-construction propertyRefinancing OptionCan be used to refinance an existing housing loanSecurity RequiredThe residential property will be used as security for the loan b. Fees & Charges Fees & ChargesDescriptionProcessing FeeNo processing feeStamp DutyPayable according to the Stamp Act 1949Late Payment Fee1% p.a. on the amount in arrears, causing the total outstanding amount to increaseEarly Settlement Fee2.25% on the prepayment amount if prepayment or full settlement is made within the first 3 years from the first loan release dateSetup FeeOne-time setup fee may apply: RM50 for loan up to RM30,000, RM100 for RM30,001 to RM100,000, and RM200 for RM100,000 and aboveMonthly Maintenance FeeRM10 per month applies only to Flexi Housing Loan or Flexi Term LoanFire InsuranceMandatory. The property must be adequately insured against risk for its full value or replacement cost, whichever is higherHouseowner InsuranceOptionalMRTAOptional but encouragedMLTAOptional but encouragedLegal or Insurer ChoiceBorrower may use the bank’s panel lawyers or insurers, or appoint their own lawyer or insurer c. Benefits BenefitDescriptionCompetitive Interest RateOffers interest rate from 3.88% p.a., subject to Bank of China’s approvalLong Loan TenureTenure of up to 35 years can help make monthly instalments more manageableHigh Financing MarginFinancing margin of up to 90% helps buyers reduce upfront capital neededSuitable for Purchase or RefinancingCan be used to finance residential property purchase or refinance an existing housing loanAvailable for Under-Construction PropertyBuyers can use this loan for completed or under-construction residential propertiesOpen to More Applicant GroupsAvailable to Malaysians, permanent residents and foreigners working in MalaysiaNo Processing FeeHelps reduce the initial cost of applying for the housing loanOptional MRTA or MLTABorrowers are encouraged to take MRTA or MLTA for protection in the event of death or total permanent disabilityFlexi Option AvailableThe PDS mentions Flexi Housing Loan options, which allow deposit and withdrawal flexibility with interest savings through a linked current accountChoice of Lawyers or InsurersBorrowers can choose the bank’s panel lawyers or insurers, or appoint their own, subject to bank requirements Visit Bank of China for more information Bank of China Housing Loan Product Disclosure Sheet 2. Understanding the Effective Lending Rate (ELR) Source: Bank Negara Malaysia The Effective Lending Rate (ELR) is a critical component when evaluating home loans. It represents the total cost of borrowing, expressed as an annual percentage rate. The ELR includes the reference rate and the spread, which collectively impact your monthly repayments. Reference Rate: The base rate, such as the Standardised Base Rate (SBR), is influenced by Bank Negara Malaysia's policies. Spread: Additional charges include credit and liquidity risk premiums, operating costs, and the bank’s profit margin. The ELR is crucial because it affects the total repayment amount and helps borrowers effectively compare different loan products. What is the Reference Rate? Source: Bank Negara Malaysia The reference rate is a benchmark interest rate used by Malaysian banks to determine changes in borrowers' repayments on floating-rate loans over the loan tenure. This rate can vary across institutions, but it serves as a foundation for setting the lending rate. Is the Reference Rate Equal to the Standardised Base Rate (SBR)? No, the reference rate differs from the Standardised Base Rate (SBR). The SBR is a specific reference rate that standardizes the base rate across all banks. Introduced on 1 August 2022, the SBR is directly linked to the Overnight Policy Rate (OPR) set by Bank Negara Malaysia. This standardization aims to simplify comparing loan rates across banks. Is the Reference Rate Equal to the Overnight Policy Rate (OPR)? The reference rate may include the OPR, especially when the SBR is used. The OPR is the interest rate at which banks lend to each other overnight and is set by the central bank. Changes in the OPR directly affect the SBR and the reference rate used for loans. What is Spread? The spread is an additional percentage added to the reference rate to arrive at the ELR. It covers various costs and risks incurred by the bank, including: Credit Risk Premium: Compensation for the risk that a borrower might default. Liquidity Risk Premium: Compensation for the risk associated with the bank’s liquidity. Operating Costs: The day-to-day expenses of running the bank. Profit Margin: The bank’s earnings from the loan. The spread is generally fixed for the duration of the loan unless there is a significant change in the borrower’s credit risk profile. 3. Understanding House Loan Interest Rates Understanding the mechanics of interest rates and their impact on repayments is essential for making informed decisions about Malaysian home loans. What are House Loan Interest Rates? House loan interest rates are the percentage of the loan principal that banks charge. These rates determine the cost of borrowing and are influenced by various factors, including the central bank’s policies and the individual bank's cost structures. How to Calculate House Loan Interest Rate? Source: Bank Negara Malaysia Calculating your home loan interest rate is crucial for understanding the total amount you will pay over time. Use a home loan calculator to determine your monthly instalments and total repayment. Here’s an example: Example Calculation: Bank’s Base Rate (BR): 2.00% Spread: 1.50% ELR: BR + Spread = 2.00% + 1.50% = 3.50% For a loan of RM300,000 over 30 years, the monthly instalment would include interest and principal repayments. Understanding these calculations can help you save money and manage your loan tenure effectively: Annual Interest Amount: RM300,000 x 3.50% = RM10,500 Monthly Interest Amount: RM10,500 / 12 = RM875 Thus, the monthly repayment would include RM875 in interest plus the principal repayment. What Can Affect Your House Loan Interest Rate? Several factors can influence your house loan interest rate, including: Central Bank Policies: Changes to Bank Negara Malaysia's Overnight Policy Rate (OPR) can directly affect interest rates. Economic Conditions: Inflation and economic stability can influence interest rates. Borrower’s Credit Score: Higher credit scores often result in lower interest rates. Loan Tenure: Longer loan tenures can sometimes attract higher interest rates. 4. How Should You Compare Lending Rates Across Banks as Borrowers? Comparing lending rates across banks involves more than just looking at the ELR. Consider the following steps: Review the ELR and Spread: Compare the total borrowing cost. Understand Additional Fees: Be aware of any extra fees that might apply. Read the Product Disclosure Sheet (PDS): This document provides crucial details about the loan. 5. How to Plan and Compare Your House Loan Interest Rates? When planning a home loan, consider the property's value, the loan amount, and the loan tenure. Use a loan calculator to estimate your monthly instalments and ensure you understand all associated fees. Planning and comparing Malaysia house loan interest rates requires a strategic approach: Research Different Lenders: Identify potential lenders and their offerings. Interest Rates: Compare the interest rates offered by different banks. Additional Features: Evaluate foreclosure charges and other loan features. Some loans include extra funds withdrawal or linked current accounts for easier management. Read Reviews: Learn from the experiences of other borrowers. Seek Professional Advice: Consult with financial advisors if needed. Maximum Loan Tenure: Most banks offer up to 35 years. Prepayment Options: Check if the bank allows for additional payments without penalties. Insurance Requirements: Most housing loans require Mortgage Reducing Term Assurance (MRTA) or other types of insurance. Flexibility: Compare loans that offer flexible repayment options, like a flexi loan or semi-flexi loan (make sure to understand the terms and conditions). Critical Terms in Home Financing Understanding key terms related to home financing is crucial for navigating the market: Outstanding Principal Balance: The remaining amount you owe on your loan, excluding interest. Home Loan Balance: The total amount left to pay on your home loan. Basic Term Loan: A standard loan with fixed interest rates and repayment terms. Loan Period: The total time over which you will repay the loan. Mortgage Reducing Term Assurance: Insurance that decreases as your loan balance decreases. Choosing the right home loan in Malaysia requires careful consideration of several factors, including interest rates, loan tenure, and associated fees. By understanding the options available and using tools like a home loan calculator, you can make a more informed decision that aligns with your financial goals and helps you secure your dream home. Version: CN, BM Are you looking for a dream house after getting the best house loan interest rates? We can assist you! Please send us your details, and we will contact you shortly. [custom_blog_form] Continue Reading: Why My Housing Loan Got Rejected in Malaysia? (Reasons Explained) Malaysia vs Singapore Property: Why Investors Still Choose KL? Where Should You Retire in Malaysia? Best Affordable, Quiet and Safe Homes to Consider
Ready to get started?
Get in touch now.