

Negotiator ∙ United
Danny Ho
REN76263
Negotiator ∙ United
Danny Ho
REN76263
About Danny Ho
Leveraging market knowledge and negotiation skills to deliver exceptional results. Your real estate success is my priority. Ready to make your real estate dreams a reality? Let's chat. Your dream home awaits.
2 years at IQI
Contact Danny Ho
Danny Ho Social Links
No social links available.
My Listings
No listings available at the moment.
Our newly launched projects
Discover the real estate properties in and around Miri, Malaysia. Buy apartment units, landed houses, bungalows, commercial office space, shop lots, and sub-sales with 100% confidence at IQI Global.
 Large land area
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
Starting from € 3,157,124
Listed on January 23, 2026
 Varied built-up sizes
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
Starting from € 262,188
Listed on January 23, 2026
 Industrial project type
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
Starting from € 1,092,267
Listed on January 23, 2026
 Located in Bukit Mertajam
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
Starting from € 243,675
Listed on January 23, 2026
 Located in Bukit Mertajam
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
Starting from € 178,160
Listed on January 23, 2026
 Located in Nibong Tebal
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
Starting from € 119,790
Listed on January 23, 2026
Mortgage Calculator
Calculate your estimated month repayment and plan your monthly expenses well.
The mortgage calculator is intended for reference only. Actual amount may vary.
Monthly Payment
Send me the mortgage calculator result
Home Loan Eligibility Calculator
Calculate your potential loan amount and assess your home buying affordability.
Rental Yield
Calculate the potential rental yield and evaluate a property's investment performance.
Down Payment Saving Plan
Create a structured savings plan and determine how much to save monthly for your down payment plan.
Malaysian Property Transaction Fees Calculator
Estimate the total transaction fees and budget accurately for your Malaysian property purchase.
IQI blog & news
Articles specifically curated for your daily digest of local and global real estate news.
Buying a property is one of the most significant financial commitments Malaysians make in their lifetime. Whether you are a first-time homebuyer or an experienced investor, understanding the property purchase process, required documents, financing options, and hidden costs is crucial. This guide provides a detailed breakdown of everything you need to know before buying a property in Malaysia. A Comprehensive Guide to Buying Property in Malaysia1. Documents Needed to Buy a Property2. How to Apply for a Home Loan in Malaysia3. How Long Does It Take to Get Keys and Loan Approval?4. Hidden Fees and Costs Before Receiving Your Keys5. Housing Schemes in Malaysia6. Bank Promotions for Housing LoansFinal Thoughts 1. Documents Needed to Buy a Property To ensure a smooth property transaction, you will need the following documents: For Individuals: Identity Card (MyKad) Latest Salary Slips (3 to 6 months) Latest EPF Statement Income Tax Return (EA Form or Borang BE for the past 2 years) Bank Statements (3 to 6 months) Letter of Employment (if applicable) Sales and Purchase Agreement (SPA) (to be signed once the purchase is confirmed) For Self-Employed Individuals: Business Registration Certificate (SSM documents) Company’s Bank Statements (6 months) Income Tax Return (Borang B for the past 2 years) These documents are essential for securing a home loan and finalizing the property purchase. 2. How to Apply for a Home Loan in Malaysia Most Malaysians rely on bank loans to finance their property purchases. Here’s how you can apply for a home loan: Step 1: Assess Your Eligibility Banks typically finance up to 90% of the property price for the first two residential properties. Your Debt Service Ratio (DSR) should ideally be below 70% (total monthly commitments compared to net income). Step 2: Compare and Choose the Right Loan Fixed vs Floating Interest Rate: Fixed rates remain unchanged, while floating rates fluctuate with the OPR (Overnight Policy Rate). Islamic vs Conventional Loans: Islamic loans follow a profit-sharing model, whereas conventional loans charge interest. Flexi vs Non-Flexi Loans: Flexi loans allow prepayment to reduce interest. Step 3: Submit the Application Prepare and submit the required documents to your selected bank. For added convenience, some banks offer online home loan applications. Step 4: Loan Approval & Offer Letter Loan approval takes approximately 1 to 2 weeks. Once approved, you will receive a Letter of Offer detailing the loan terms and conditions. 3. How Long Does It Take to Get Keys and Loan Approval? The property purchasing process involves multiple stages: Loan Approval: 1 to 2 weeks Sign Sales & Purchase Agreement (SPA): 1 month Stamp Duty & Loan Agreement Processing: 1-2 months Property Completion & Key Handover: Subsale (Completed Property): 3 to 6 months Under Construction: 24 to 48 months (depending on project phase) 4. Hidden Fees and Costs Before Receiving Your Keys Many buyers overlook additional costs when purchasing a property. Here are some hidden fees to consider: Stamp Duty on SPA: First RM100,000: 1% RM100,001 – RM500,000: 2% RM500,001 – RM1,000,000: 3% Above RM1,000,000: 4% Stamp Duty on Loan Agreement: 0.5% of the loan amount Legal Fees & Disbursement Fees: Approximately 2% to 3% of property price Valuation Fees: If buying a subsale property, a valuation fee is required (approx. 0.25% of property price) MRTA/MRTT (Mortgage Insurance): Optional but recommended, cost depends on loan amount and tenure Utilities & Maintenance Fees: For high-rise properties, a sinking fund & maintenance fee is payable 5. Housing Schemes in Malaysia The Malaysian government has introduced various housing schemes to help first-time buyers and lower-income groups afford homes. Some popular schemes include: PR1MA (Perumahan Rakyat 1Malaysia) – Affordable homes for middle-income Malaysians Residensi Wilayah – Special scheme for Kuala Lumpur & Putrajaya residents RUMAWIP (Rumah Mampu Milik Wilayah Persekutuan) – Affordable housing in the Federal Territories BSN MyHome – 100% financing for low-income buyers Rent-to-Own (RTO) Scheme – Option to rent before purchasing These schemes aim to reduce the financial burden of homeownership. 6. Bank Promotions for Housing Loans Banks in Malaysia often offer special promotions to attract home loan applicants. Some standard promos include: Zero Moving Cost (ZMC) Packages – No legal & valuation fees Lower Interest Rates for First-Time Buyers Cashback Offers – Some banks provide rebates or cashback Special Islamic Home Financing Plans – Banks like Maybank, CIMB, and Bank Islam offer Syariah-compliant home financing It is advisable to compare different banks' offers to find the best housing loan package that suits your needs. Final Thoughts Buying a property in Malaysia requires careful planning, financial preparation, and thorough research. Understanding the required documents, loan application process, waiting time, hidden fees, available housing schemes, and bank promotions can help you make a well-informed decision. If you’re considering buying a property, take the time to compare home loan options, explore government incentives, and ensure that you’re financially ready for this significant investment. Happy house hunting! IQI Global serves as a worldwide real estate agency and provides an excellent platform for discovering top-notch properties in Malaysia within your preferred budget. IQI offers a comprehensive solution for all your real estate needs. So do not waste time and get to know more about real estate at IQI Global and buy the house of your dream! [custom_blog_form]
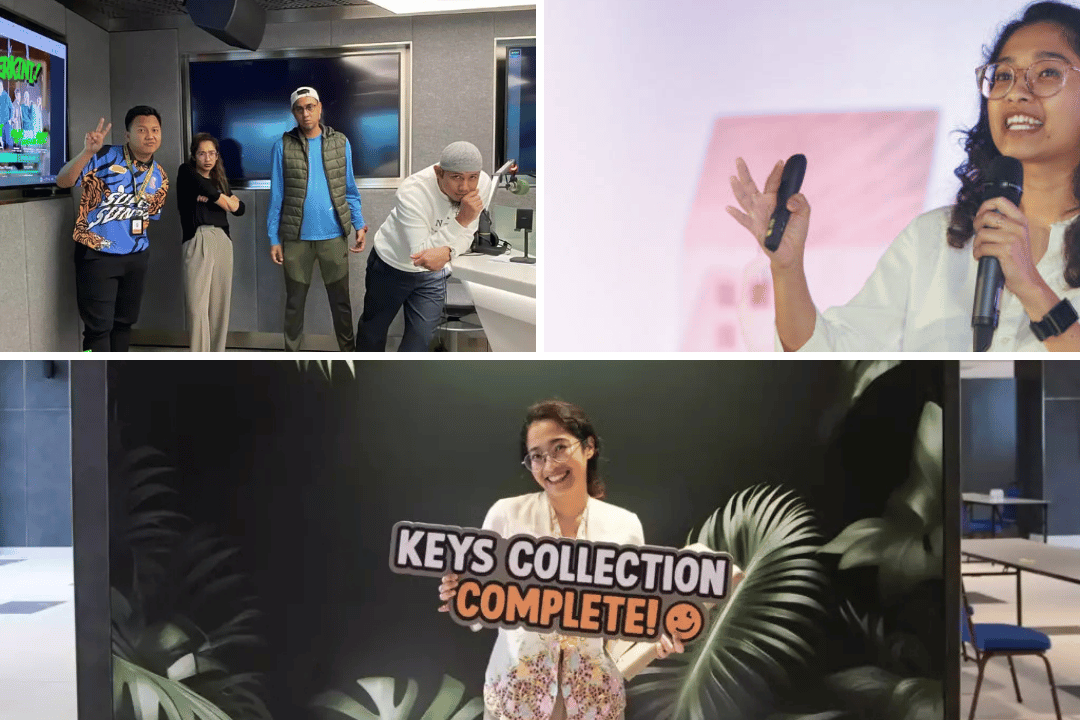
Version: BM Some career decisions are not made in meeting rooms. They are made quietly. Late at night.Between doubts.Between “what if” and “what now”. If you have ever searched “how to become a real estate agent in Malaysia”, chances are you are not just curious. You are considering change! Before you step into a real estate agent career in Malaysia, there is one story you should hear. View this post on Instagram A post shared by IQI (@iqiglobal) Table of contentsWhy Real Estate Remains an Open Opportunity in MalaysiaThe Challenges Many Faces in Career TransitionsFrom Journalism to Real Estate Success: The Story of MarieJualKondo (Natasha Gideon)What Natasha’s Journey Teaches About Career ReinventionWhat It Actually Takes to Succeed as a Real Estate Agent in MalaysiaHow to Start a Real Estate Career in Malaysia Why Real Estate Remains an Open Opportunity in Malaysia Unlike professions that demand specific degrees or years of industry certification, becoming a real estate agent in Malaysia follows a structured yet accessible pathway. You do not need a property-related academic background. You need: Registration under a licensed real estate agency Official Real Estate Negotiator status Required training Commitment Malaysia’s property market continues to generate transactions across residential, subsale and investment segments. As long as people buy, sell and upgrade homes, agents remain relevant. Real estate is not limited by corporate hierarchy. Income is performance-based. For many, that is both the attraction and the fear. The Challenges Many Faces in Career Transitions Changing careers is rarely comfortable. The biggest challenge is not learning something new. It is leaving something familiar. Fixed salaries provide stability. Commission-based careers provide possibility. But possibility comes with uncertainty. New agents often struggle with: Irregular income in early months Rejection from prospects Doubt from friends or family Self-doubt The first year is less about talent and more about resilience. Those who stay consistent build momentum. Those expecting quick results often leave too early. From Journalism to Real Estate Success: The Story of MarieJualKondo (Natasha Gideon) Before becoming a recognised real estate agent in Malaysia, MarieJualKondo or Natasha Gideon was a journalist covering the property industry. Through interviews with developers and negotiators, she observed how successful agents built their careers. Over time, she realised that long-term success in a real estate agent career in Malaysia was not about being the loudest — it was about discipline, follow-up and consistency. Eventually, she made a decision that many consider but few execute. She left a fixed salary to enter commission-based real estate. @natashagideon This page started in 2019 and I’ve been posting a lot since then. Here’s just a reminder of who I am and what I do #hartanahmalaysia #realestate #realestatejourney #teammjk #mariejualkondo ♬ original sound - MarieJualKondo The early months were challenging. There were viewings that did not convert and periods without commission. Instead of losing confidence, she focused on professionalism and structured follow-up. Within three weeks of handling one of her early subsale cases, she secured the deal! @natashagideon Thanks for having me @HITZ. What a blast with @Keanu Azman and my twin @ili ♬ original sound - songs n lyrics Nine years later, Natasha is now a team leader within IQI. Her journey was not built on luck, but on consistency, resilience and operating within a structured real estate platform. What Natasha’s Journey Teaches About Career Reinvention Her story reveals several truths about becoming a real estate agent in Malaysia. First, background does not determine success. She transitioned from journalism into property sales. Second, the early stage is emotionally demanding. Not because the industry is unfair, but because momentum takes time. Third, consistency compounds. Natasha did not rely solely on transactions. She began sharing educational property content under the name 'MarieJualKondo' long before digital branding became common among agents. I’m motivated by challenges. I’ve always understood the income potential that comes with being a REN and real estate negotiator, and I genuinely enjoy building my earnings! In a 9-to-5 job, even if you give 200 percent effort, your salary stays the same. But in real estate, when I put in 200 percent effort, my income can grow just as fast! Natasha Gideon There was no viral breakthrough. There was repetition, structured explanations and steady content creation. Over time, credibility accumulated, media recognition followed and leadership opportunities expanded. Career reinvention, especially in real estate, is rarely dramatic. It is disciplined and cumulative. What It Actually Takes to Succeed as a Real Estate Agent in Malaysia A sustainable real estate agent career in Malaysia depends on behavioural consistency. It rewards daily prospecting, systematic follow-ups, relationship management and emotional regulation during rejection. It does not reward impatience. Success during the first year often depends on three factors: surviving income fluctuations, committing to daily outreach activity and choosing structured mentorship. Operating under an established agency such as IQI provides compliance support, training systems, brand credibility and access to experienced leaders. While structure does not eliminate effort, it significantly reduces confusion and accelerates early learning. How to Start a Real Estate Career in Malaysia If you are serious about becoming a real estate agent in Malaysia, the pathway is clear: Join a licensed real estate agency Register as a Real Estate Negotiator Complete required training Operate under supervision The mechanics are straightforward. The mindset is the real decision. Is This the Right Path for You? Ask yourself honestly: Can you operate without guaranteed income initially? Are you willing to stay consistent even when results are delayed? Do you want growth without ceiling? Real estate in Malaysia remains one of the few industries where effort directly impacts income trajectory. Natasha once wrote about Malaysia’s property market. Today, she shapes it. The opportunity remains open. The real question is whether you are prepared to commit to it. At IQI, we provide the platform, training and mentorship to help you grow faster. Join Natasha’s team and build your real estate career in an environment designed for performance, progression and real results. [custom_blog_recruit_form] Continue Reading: What are the Benefits of Joining IQI Global as a Real Estate Agent? From Engineer to Top-Selling Real Estate Agent: How One Failure Can Bring You Closer to Years of Success Are You a -P or -J MBTI Personality Type? Unleash Your Hidden Talent as a Real Estate Agent Based On Your Type!
Malaysia is one of the few countries in Southeast Asia where foreigners can own property on a freehold title. But there is no single national rulebook. Each state sets its own minimum price, property types and approval process. This guide breaks it all down, state by state, for 2026. TL;DR: Foreign Property Ownership in Malaysia (2026)1. Yes, foreigners can buy property in Malaysia, including freehold, but need State Authority consent.2. Minimum prices are set by each state, usually from RM1,000,000 (KL, Putrajaya, Labuan, Johor strata, Penang Island strata).3. Selangor is generally RM2,000,000 in Zones 1 and 2. Melaka and Sarawak can start from RM500,000.4. Foreigners cannot buy Malay Reserved Land, low and medium-cost housing, or Bumiputera-quota units.5. Foreign buyers pay a flat 4% stamp duty on the transfer, plus legal fees and State consent fees.6. RPGT for foreigners is 30% if sold within 5 years and 10% from year 6 onwards. Can Foreigners Buy Property in Malaysia? Yes. Foreigners are generally allowed to purchase property in Malaysia. However, eligibility, minimum purchase prices and approval procedures vary by state. That is because land matters fall under state jurisdiction. The National Land Code 1965 requires foreign individuals and companies to obtain approval from the relevant State Authority before acquiring land or property. Property typeCan foreigners buy?Condominiums and serviced residencesYes, above the state minimum priceCommercial properties (shops, offices)Yes, subject to state requirementsIndustrial unitsYes, subject to state requirementsLanded homesSometimes, with tighter conditions and higher thresholdsAgricultural landGenerally restrictedMalay Reserved LandNoLow and medium-cost housingNoBumiputera-quota unitsNo Landed homes are the grey area. In Selangor, for example, foreigners can usually only buy landed homes that come with a strata title, such as units in gated and guarded communities. What Is the Minimum Price for Foreigners to Buy Property in Malaysia? (2026) Here are the indicative minimum purchase prices by state. Always check the latest figure with the State Authority before you commit, as thresholds are reviewed from time to time. StateStrata (condo, serviced residence)LandedKuala Lumpur, Putrajaya, LabuanFrom RM1,000,000From RM1,000,000SelangorRM2,000,000 in Zones 1 and 2. Zone 3 ranges from RM1,000,000 to RM2,000,000Penang IslandFrom RM1,000,000From RM3,000,000JohorFrom RM1,000,000From RM2,000,000MelakaMay start from RM500,000, depending on property categorySarawakMay start from RM500,000, depending on location and property category Figures are indicative as of 2026 and subject to change by each State Authority. Which State Is Cheapest for Foreign Buyers? Melaka and Sarawak have the lowest entry points, with some categories starting from RM500,000. Selangor is the most expensive, at RM2,000,000 in its prime zones. Johor stays popular with Singaporeans thanks to its RM1,000,000 strata threshold and the RTS Link to Singapore. How Do Foreigners Buy Property in Malaysia? 5 Steps The process is close to what locals go through, with one extra layer: State consent. Here is how it usually works. Step 1: Identify a Suitable Property Shortlist properties that are open to foreign ownership and meet the minimum price for that state. Avoid Bumiputera-quota units, which foreigners cannot buy. Step 2: Make an Offer and Pay the Earnest Deposit Sign a letter of offer or expression of interest and pay an earnest deposit, commonly around 2% to 3% of the price. Step 3: Sign the Sale and Purchase Agreement (SPA) The SPA is usually signed within the agreed timeframe. You top up the payment to complete the down payment, often 10% of the purchase price. Step 4: Obtain State Authority Approval Foreign buyers need consent from the relevant State Authority. Your lawyer normally handles this application as part of the transaction, including the forms, consent fee and supporting documents. Step 5: Arrange Financing and Complete the Purchase Foreigners can apply for a Malaysian home loan, but the financing margin is often lower than for locals. Once financing and approvals are in place, the balance is paid according to the SPA completion timeline. Tip: get your lawyer and banker on board early. State consent and loan approval can run in parallel and save weeks. What Taxes and Costs Do Foreigners Pay When Buying Property in Malaysia? The price tag is not the full bill. Budget for these extra costs on top of the purchase price. CostWhat foreign buyers should expectStamp duty (transfer)Flat 4% of the property value for foreign buyersLegal feesBased on the purchase price and the legal fee scaleState consent feeVaries by stateLoan stamp duty and legal feesOnly if you take a home loanRPGT (when you sell)30% within 5 years, 10% from year 6 onwards Worked Example: A RM1.2 Million Condo in Kuala Lumpur Earnest deposit (3%): RM36,000 Top-up to 10% at SPA: RM84,000 Stamp duty on transfer (4%): RM48,000 Balance via loan or cash: RM1,080,000 That means you need roughly RM168,000 in cash before legal fees, just to get to SPA and transfer. Plan for it early. Want the full breakdown? Use our property transaction fees calculator to estimate legal fees and stamp duty. Is There a Visa That Supports Foreign Property Buyers? Owning property in Malaysia does not give you residency on its own. But the Malaysia My Second Home (MM2H) programme pairs well with property investment. MM2H offers a renewable visa of 5 to 20 years, depending on the tier. Applicants must meet financial criteria such as fixed deposits and income requirements, and property purchases can count towards the programme. As of 2024, the revamped MM2H generated RM455.8 million through fixed deposits and property purchases, with 782 approvals granted. Example: A Singaporean Buyer in Johor Bahru Picture a Singaporean buyer looking at a condo in Johor Bahru. They pick a unit above Johor's RM1,000,000 strata threshold, outside the Bumiputera quota. Their lawyer files for State consent while the bank processes the loan. The result: a weekend home that can also earn rental income, thanks to JB's proximity to Singapore. The lesson is simple. Know the state rules first, and the rest of the process falls into place. https://youtu.be/GYvewvT7lJ8?si=hYjSnu49bIO8cvtm Key Takeaways1. Foreigners can buy property in Malaysia, with State Authority consent.2. Minimum prices differ by state, from RM500,000 (Melaka, Sarawak) to RM2,000,000 (Selangor Zones 1 and 2) and RM3,000,000 (Penang Island landed).3. Malay Reserved Land, low and medium-cost homes and Bumiputera units are off-limits.4. Budget for a 4% stamp duty, legal fees and State consent fees on top of the price.5. RPGT for foreigners is 30% within 5 years, so plan to hold long term. Frequently Asked Questions Thinking of buying in Malaysia? Chat with our professional team, a group dedicated to ensuring your purchase journey goes smoothly. Can foreigners buy land in Malaysia? Yes, but with State Authority approval. Foreigners cannot buy Malay Reserved Land or, in most states, agricultural land. What is the minimum price for foreigners to buy property in Kuala Lumpur? RM1,000,000 in Kuala Lumpur, Putrajaya and Labuan. Can foreigners buy landed property in Malaysia? Sometimes. Landed homes face tighter conditions and higher thresholds, such as RM2,000,000 in Johor and RM3,000,000 on Penang Island. Selangor generally only allows landed strata-titled homes. Can foreigners get a home loan in Malaysia? Yes. Malaysian banks lend to foreigners, but the financing margin is usually lower than for locals. How much stamp duty do foreigners pay in Malaysia? Foreign buyers pay a flat 4% stamp duty on the property transfer. Does buying property in Malaysia give me residency? No. Property ownership does not grant residency. Programmes like MM2H offer long-term visas separately. Conclusion Malaysia is open to foreign buyers, but the rules change at every state border. Check the minimum price, avoid restricted categories and budget for stamp duty and fees. As regulations and thresholds can change, confirm the latest requirements with a qualified property professional or lawyer before proceeding. Do you wish to talk to experts before making that big purchase? Chat with our professional team, a group dedicated to ensuring your purchase journey goes smoothly! [custom_blog_form]
Malaysia’s Budget 2027 could help reduce unsold affordable homes while setting the foundation for the country’s new 10-year National Housing Policy. With Malaysia targeting one million affordable homes by 2035, Juwai IQI believes the focus should not simply be on building more homes, but building the right homes in the right locations and at prices Malaysians can afford. How Could Better Planning Prevent RM1.8 Billion in Unsold Homes? If better housing planning prevents just 1,000 affordable homes averaging RM195,000 from remaining unsold each year, the impact could reach approximately RM1.76 billion over nine years. Potential impactEstimateHomes prevented from remaining unsold1,000 per yearAverage home priceRM195,000Housing value per yearRM195 million9-year potential valueRM1.76 billion Better use of household income, population, employment, transport and housing supply data could help determine what homes to build, where to build them and at what price. Not every unsold property is considered property overhang. Read our guide on property overhang vs unsold property in Malaysia to understand the difference. Note: RM1.76 billion is the estimated value of homes that could potentially be prevented from remaining unsold over nine years, not Malaysia’s current total property overhang. Building Homes Malaysians Actually Need Kashif said Budget 2027 could help turn Malaysia’s housing targets into practical action. Budget 2027 can support better data-led planning, more flexible financing and modern construction technologies so that the homes we build better reflect what Malaysian households actually need. Kashif Ansari, Co-Founder and Group CEO, Juwai IQI More Ways to Finance a Home Housing affordability is not only about property prices. Malaysians also need access to financing. Around 27,000 Malaysians received guarantees through the Housing Credit Guarantee Scheme (SJKP) last year to help purchase their first homes. Juwai IQI believes Budget 2027 could build on this with alternatives such as rent-to-own, shared ownership and long-term fixed-rate mortgages, particularly for gig workers, freelancers and self-employed Malaysians. Upfront buying costs are another concern. Juwai IQI has also called for the government to continue supporting first-time buyers through the Budget 2027 first-home stamp duty exemption. Build Smarter, Not Just More Malaysia does not simply need more homes. We need the right homes, at the right prices and in the right locations. Kashif Ansari, Co-Founder and Group CEO, Juwai IQI echnology could also help Malaysia deliver affordable homes more efficiently. Industrialised Building System (IBS) can shorten construction periods, while newer methods such as Prefabricated Prefinished Volumetric Construction (PPVC) could further improve construction speed and productivity. Budget 2027 could encourage developers to adopt technologies that reduce waste, improve efficiency and help control construction costs. One Million Affordable Homes by 2035 Malaysia aims to deliver one million affordable homes by 2035, or around 100,000 homes per year. The target is ambitious, but the bigger challenge is making sure those homes are built where people need them, priced within their means and supported by realistic financing options. As the first federal budget under the new 10-year National Housing Policy, Budget 2027 could help set that direction. For Juwai IQI, success should not only be measured by how many homes Malaysia builds, but by how many Malaysians can actually afford, finance and live in them. This article is based on reporting by DagangNews and BusinessToday in October 2026, with insights from Juwai IQI Co-Founder and Group CEO Kashif Ansari on Budget 2027, affordable housing supply, home financing and measures to reduce unsold homes in Malaysia. Juwai IQI provides expert insights into the property, economic and investment trends shaping markets locally and globally. Click below to get more expert property insights from our blog! MORE INSIGHTS
Ready to get started?
Get in touch now.