

Snr Negotiator ∙ Ace
Katherine Lai Keet Yee
REN37933
关于 Katherine Lai Keet Yee
致力于在房地产市场提供卓越服务和专业知识的专业房地产经纪人。
6 在 IQI 的年数
55 交易
Katherine Lai Keet Yee 社交媒体链接
暂无社交媒体链接。
我的房源
目前没有可用的房源。
我们新推出的项目
探索 Kuala Lumpur, Malaysia 及其周边的房地产物业。在 IQI Global 以 100% 的信心购买公寓单位、有地房屋、平房、商业办公空间、店屋和转售物业。
 大面积土地
Northern TechValley @BKE
Mukim 14, Kubang Semang, 14400 Seberang Perai, Penang, Malaysia
从起跳 ¥ 23,855,277
Listed on January 23, 2026
 位于Bukit Minyak
Taman IKS Bukit Minyak
Jalan IKS Bukit Minyak Utama, Taman IKS Bukit Minyak, 14100 Simpang Ampat, Penang, Malaysia.
从起跳 ¥ 1,981,094
Listed on January 23, 2026
 工业项目类型
Regalway Industrial Hub (Industrial)
Regalway Industrial Hub, Off Jalan Bukit Panchor, Bukit Panchor, 14100 Simpang Ampat, Penang, Malaysia.
从起跳 ¥ 8,253,186
Listed on January 23, 2026
 位于武吉美拉
Taman Jasa Ria (Garden Villa)
Jalan Permatang Pasir, Taman Jasa Ria, 14000 Bukit Mertajam, Penang, Malaysia
从起跳 ¥ 1,841,209
Listed on January 23, 2026
 位于武吉美拉
Taman Jasa Intan (Garden Superlink)
Jalan Jasa Intan, Taman Jasa Intan, 14000 Bukit Mertajam, Penang, Malaysia
从起跳 ¥ 1,346,183
Listed on January 23, 2026
 大面积土地
Taman Fajar Permai (Sunrise Terrace)
Jalan Fajar, Taman Fajar Permai, 14300 Nibong Tebal, Penang, Malaysia.
从起跳 ¥ 905,135
Listed on January 23, 2026
房屋贷款计算器
计算您估计的每月还款额并妥善规划您的每月开支。
The mortgage calculator is intended for reference only. Actual amount may vary.
每月分期付款金额
请发送我的房贷计算结果
IQI 博客和新闻
专门为您精选的本地和全球房地产新闻每日摘要文章。
Global Property Growth Becomes Increasingly Uneven Global luxury property markets are entering a more selective phase, with price growth varying significantly across major cities. According to Knight Frank's Prime Global Cities Index Q2 2026, average annual price growth across 46 cities reached just 2.6%, while 15 cities recorded price declines. Tokyo led the index with 50.7% annual growth, supported by limited supply and currency conditions. Central Tokyo condominium prices also surged 34.7%, reflecting strong demand for scarce premium properties. Meanwhile, Dubai ranked third with 10.9% growth, although Q3 sales values declined 47% year-on-year, indicating cooling market activity. Manila ranked second with 14.6% prime property growth, but Metro Manila's residential vacancy rate was projected to reach 25.6%, highlighting the contrast between luxury and broader housing markets. Investment Opportunities Depend on Local Fundamentals In Malaysia, residential prices increased just 0.9% in Q2 2026, while Budget 2027 introduced stamp duty exemptions for eligible first-time buyers purchasing homes up to RM500,000. Bali continues to attract lifestyle property investors, although tighter land-use regulations and ownership restrictions make proper legal structures increasingly important. Meanwhile, Portugal's house prices rose 16.5% year-on-year in Q2 2026, despite a 6.4% decline in transactions, reflecting strong domestic demand and limited housing supply. In prime central London, prices recorded their first quarterly increase in four years, rising 0.3% in the three months to September, although annual values remained below previous peaks. These contrasting trends reinforce the importance of evaluating individual markets rather than relying on global averages. Outlook With global prime property prices growing at an average of just 2.6%, investors can no longer depend solely on market-wide appreciation. Moving forward, property quality, entry pricing, rental demand and local market conditions will play a greater role in determining investment returns. Selective, fundamentals-driven investments are likely to offer stronger long-term opportunities than broad market exposure. The contents of this article were contributed by Taco Heidinga, Global Real Estate Strategist, Juwai IQI; Country Head, IQI Bali & Lombok; Founder, Homes in Asia. Download to see insights from other country marketsDownload
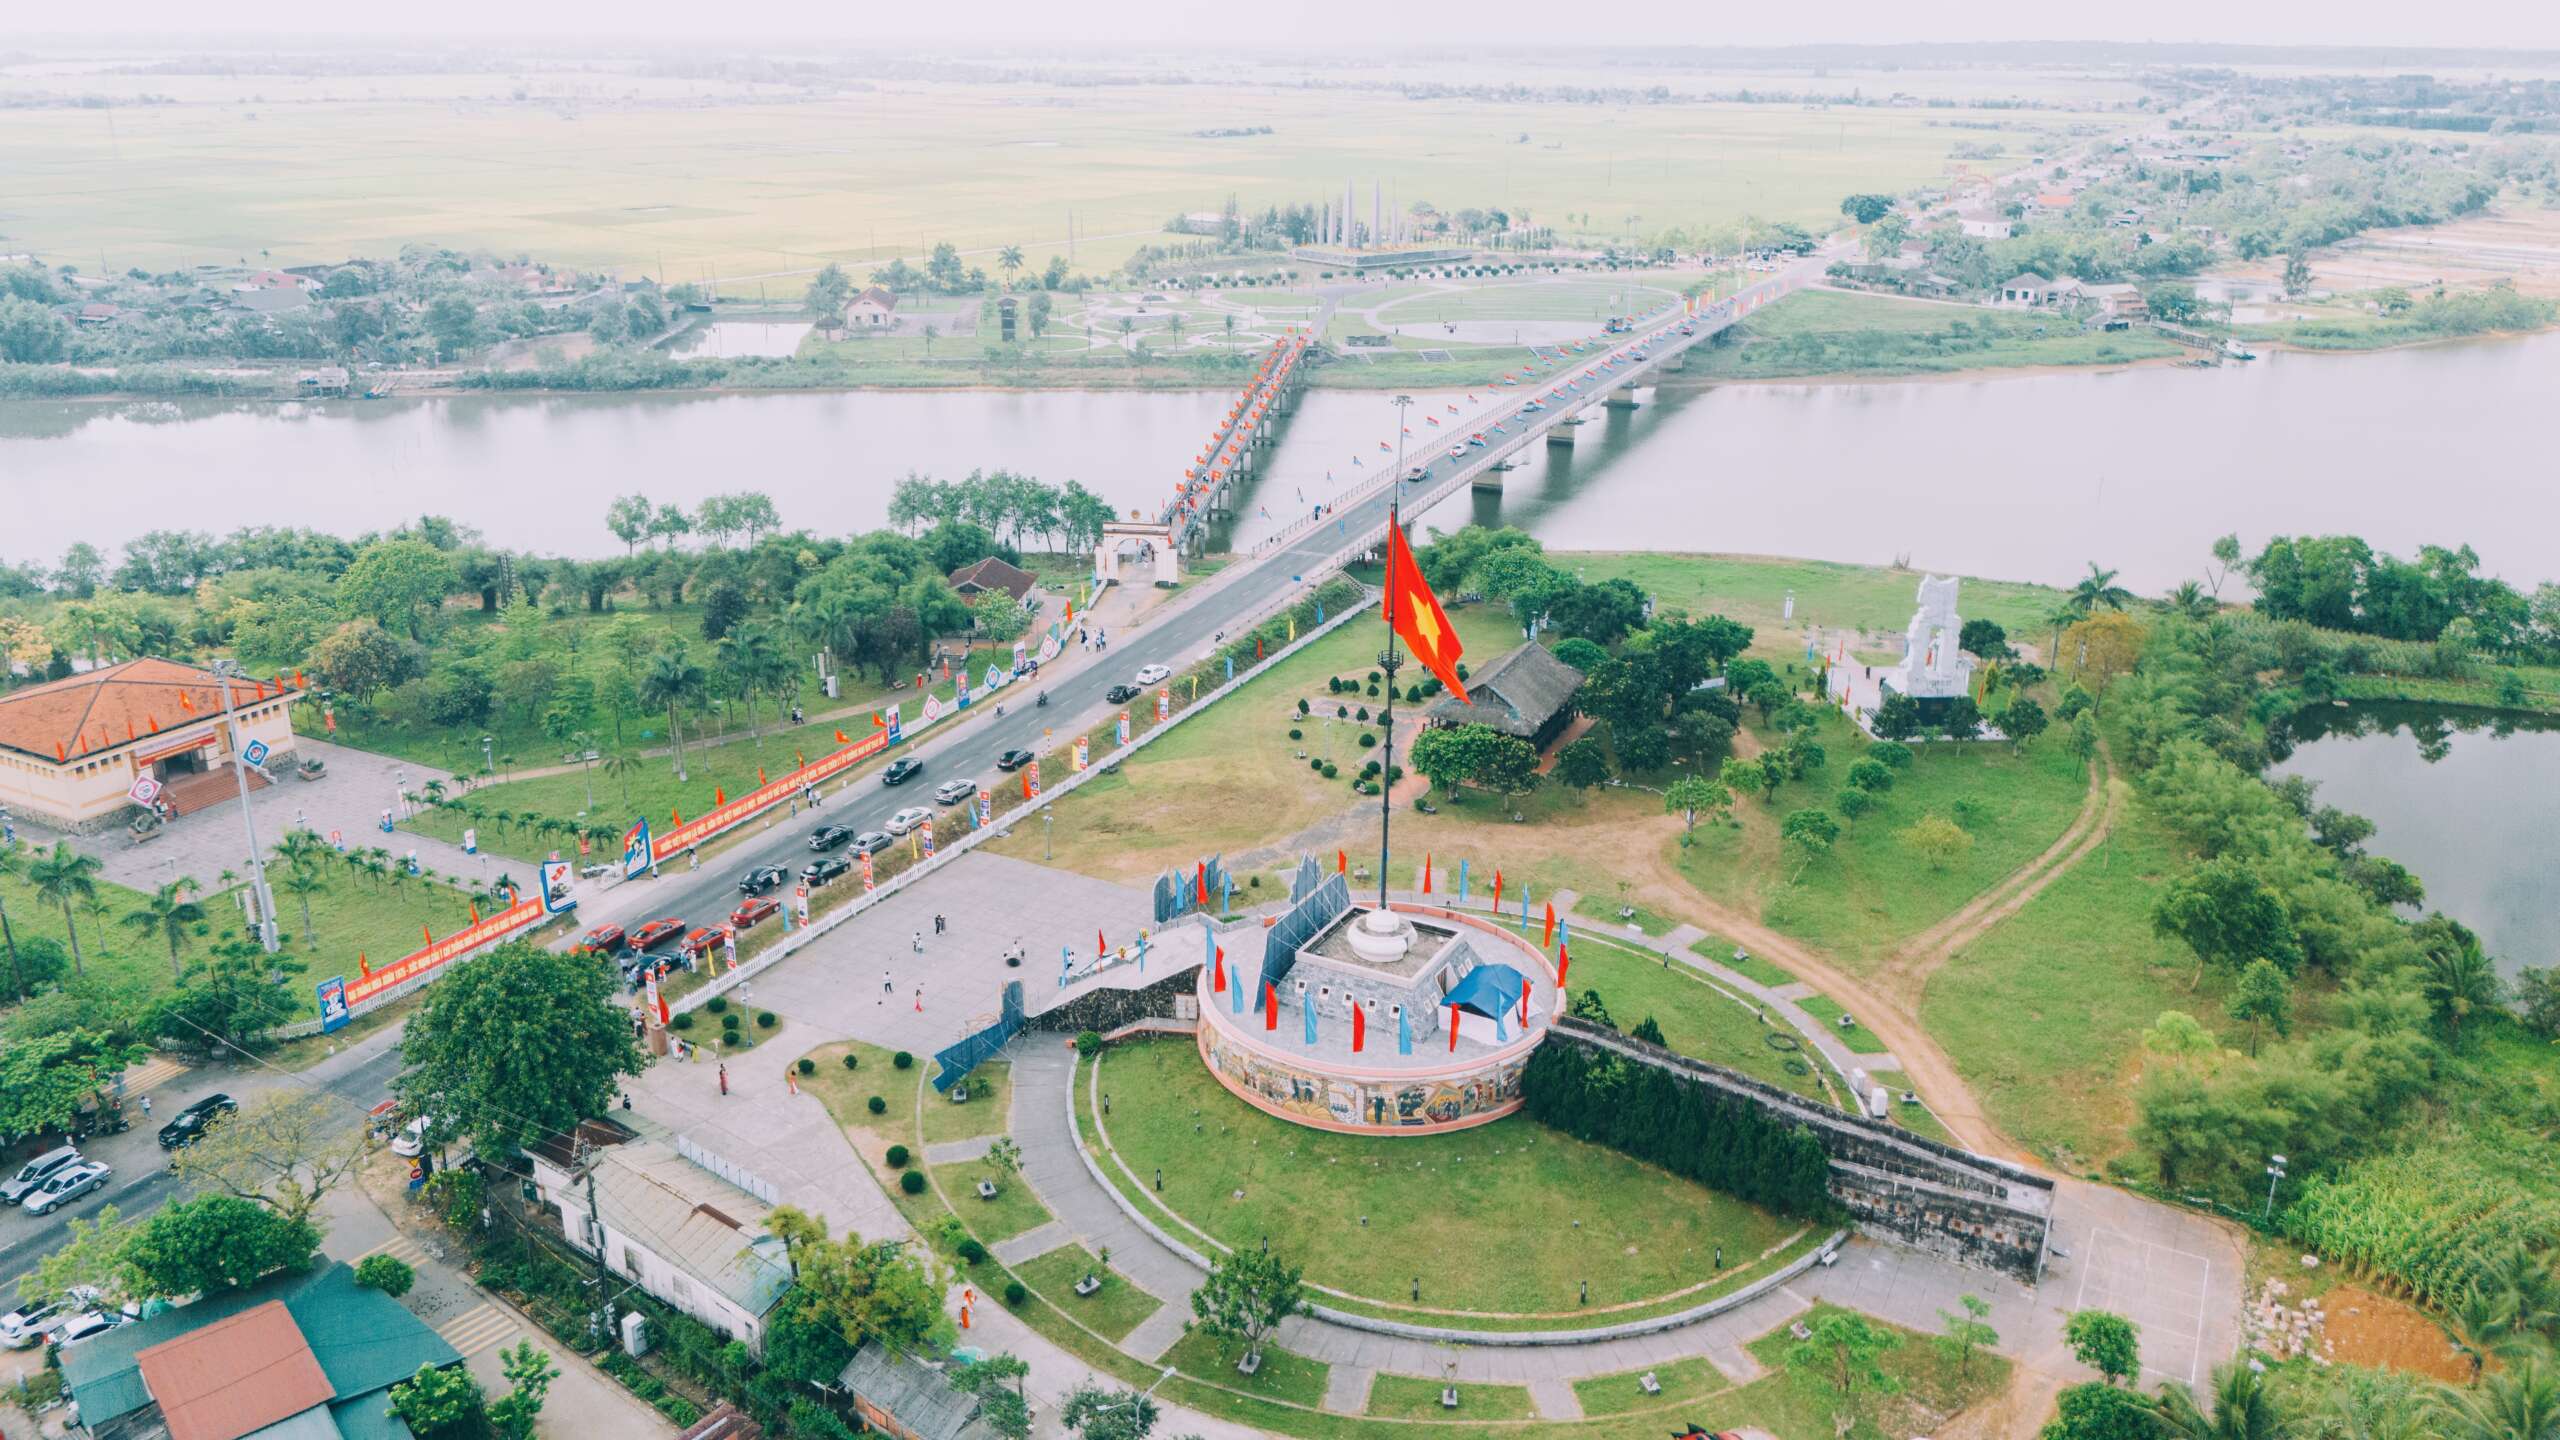
Property Regulations Enter a New Review Phase Vietnam's property market is attracting attention as proposed regulatory changes and evolving buyer conditions create new considerations for domestic and international investors. A proposed update to the country's property ownership framework is currently under review, potentially influencing future purchase decisions. The draft proposals address several important areas, including property ownership scope, buyer eligibility, confirmation procedures and ownership terms. However, these changes have not yet been enacted, meaning investors should continue referring to existing regulations until official updates are confirmed. Understanding legal requirements remains particularly important for foreign purchasers, as eligibility and ownership structures may differ according to property type and applicable restrictions. Cash Buyers Gain More Negotiating Flexibility Market conditions are also creating potential opportunities for purchasers with stronger financial positions. According to the November 2026 newsletter, cash buyers in selected Vietnamese property markets may secure negotiated discounts of approximately 8% to 12%. This compares with approximately 2% to 3% for buyers relying on financing, reflecting the advantages of greater transaction certainty and financial flexibility. Meanwhile, Vietnam's economic fundamentals remain supportive. The country recorded approximately 9.95% GDP growth in Q3 2026, alongside USD50.36 billion in registered foreign direct investment through 30 September 2026. FDI disbursement reached approximately USD21.07 billion during the first nine months of 2026, reflecting continued foreign investment activity. These indicators provide broader economic context, although individual property performance remains dependent on location, demand and legal compliance. Outlook Vietnam's property market presents opportunities for financially prepared buyers, particularly where negotiated pricing improves purchase value. However, legal clarity, ownership eligibility, financing conditions and asset quality remain essential. Investors should closely monitor official regulatory developments before making decisions based on proposed ownership changes. The contents of this article were contributed by Dustin Trung Nguyen, Head of IQI Vietnam. Download to see insights from other country marketsDownload
Bangkok's Condominium Market Shows Stronger Activity Thailand's residential property market is experiencing changing supply conditions, with Bangkok's condominium sector showing notable differences between locations. In Q2 2026, Bangkok and five surrounding provinces recorded approximately 85,249 condominium units in housing supply. Low-rise housing represented a larger segment, with approximately 128,834 units. Meanwhile, regional condominium sales activity displayed strong momentum in selected areas. Sukhumvit condominium sales increased approximately 338.6%, highlighting considerable growth in transaction activity. The Bang Ya–Bang Bua Thong–Bang Kruai–Sai Noi corridor also recorded approximately 59% sales growth, reflecting demand beyond Bangkok's established central locations. However, strong sales growth in individual areas does not necessarily indicate uniform market recovery. Location and Inventory Shape Investment Decisions Thailand's broader residential sector continues to demonstrate mixed market conditions. The national condominium market recorded approximately 214,083 transactions in Q2 2026, while overall condominium supply increased 19.5% year-on-year. Total transaction activity remained weaker, declining approximately 6.6% annually. This contrast between rising supply and softer overall transactions reinforces the need for careful property selection. Monthly condominium absorption rates also varied significantly between locations. Sukhumvit recorded an absorption rate of approximately 5.2% per month, compared with 3.3% in the Bang Ya–Bang Bua Thong–Bang Kruai–Sai Noi corridor. For property buyers and investors, transport access, employment centres, shopping facilities, healthcare services and overall neighbourhood convenience remain important demand drivers. Outlook Thailand's residential property market offers opportunities in locations supported by genuine end-user demand. However, inventory levels, project positioning, transport connectivity and absorption rates will remain critical considerations as developers and buyers navigate changing supply conditions. The contents of this article were contributed by Somsak Chutisilp, Head of IQI Thailand. Download to see insights from other country marketsDownload
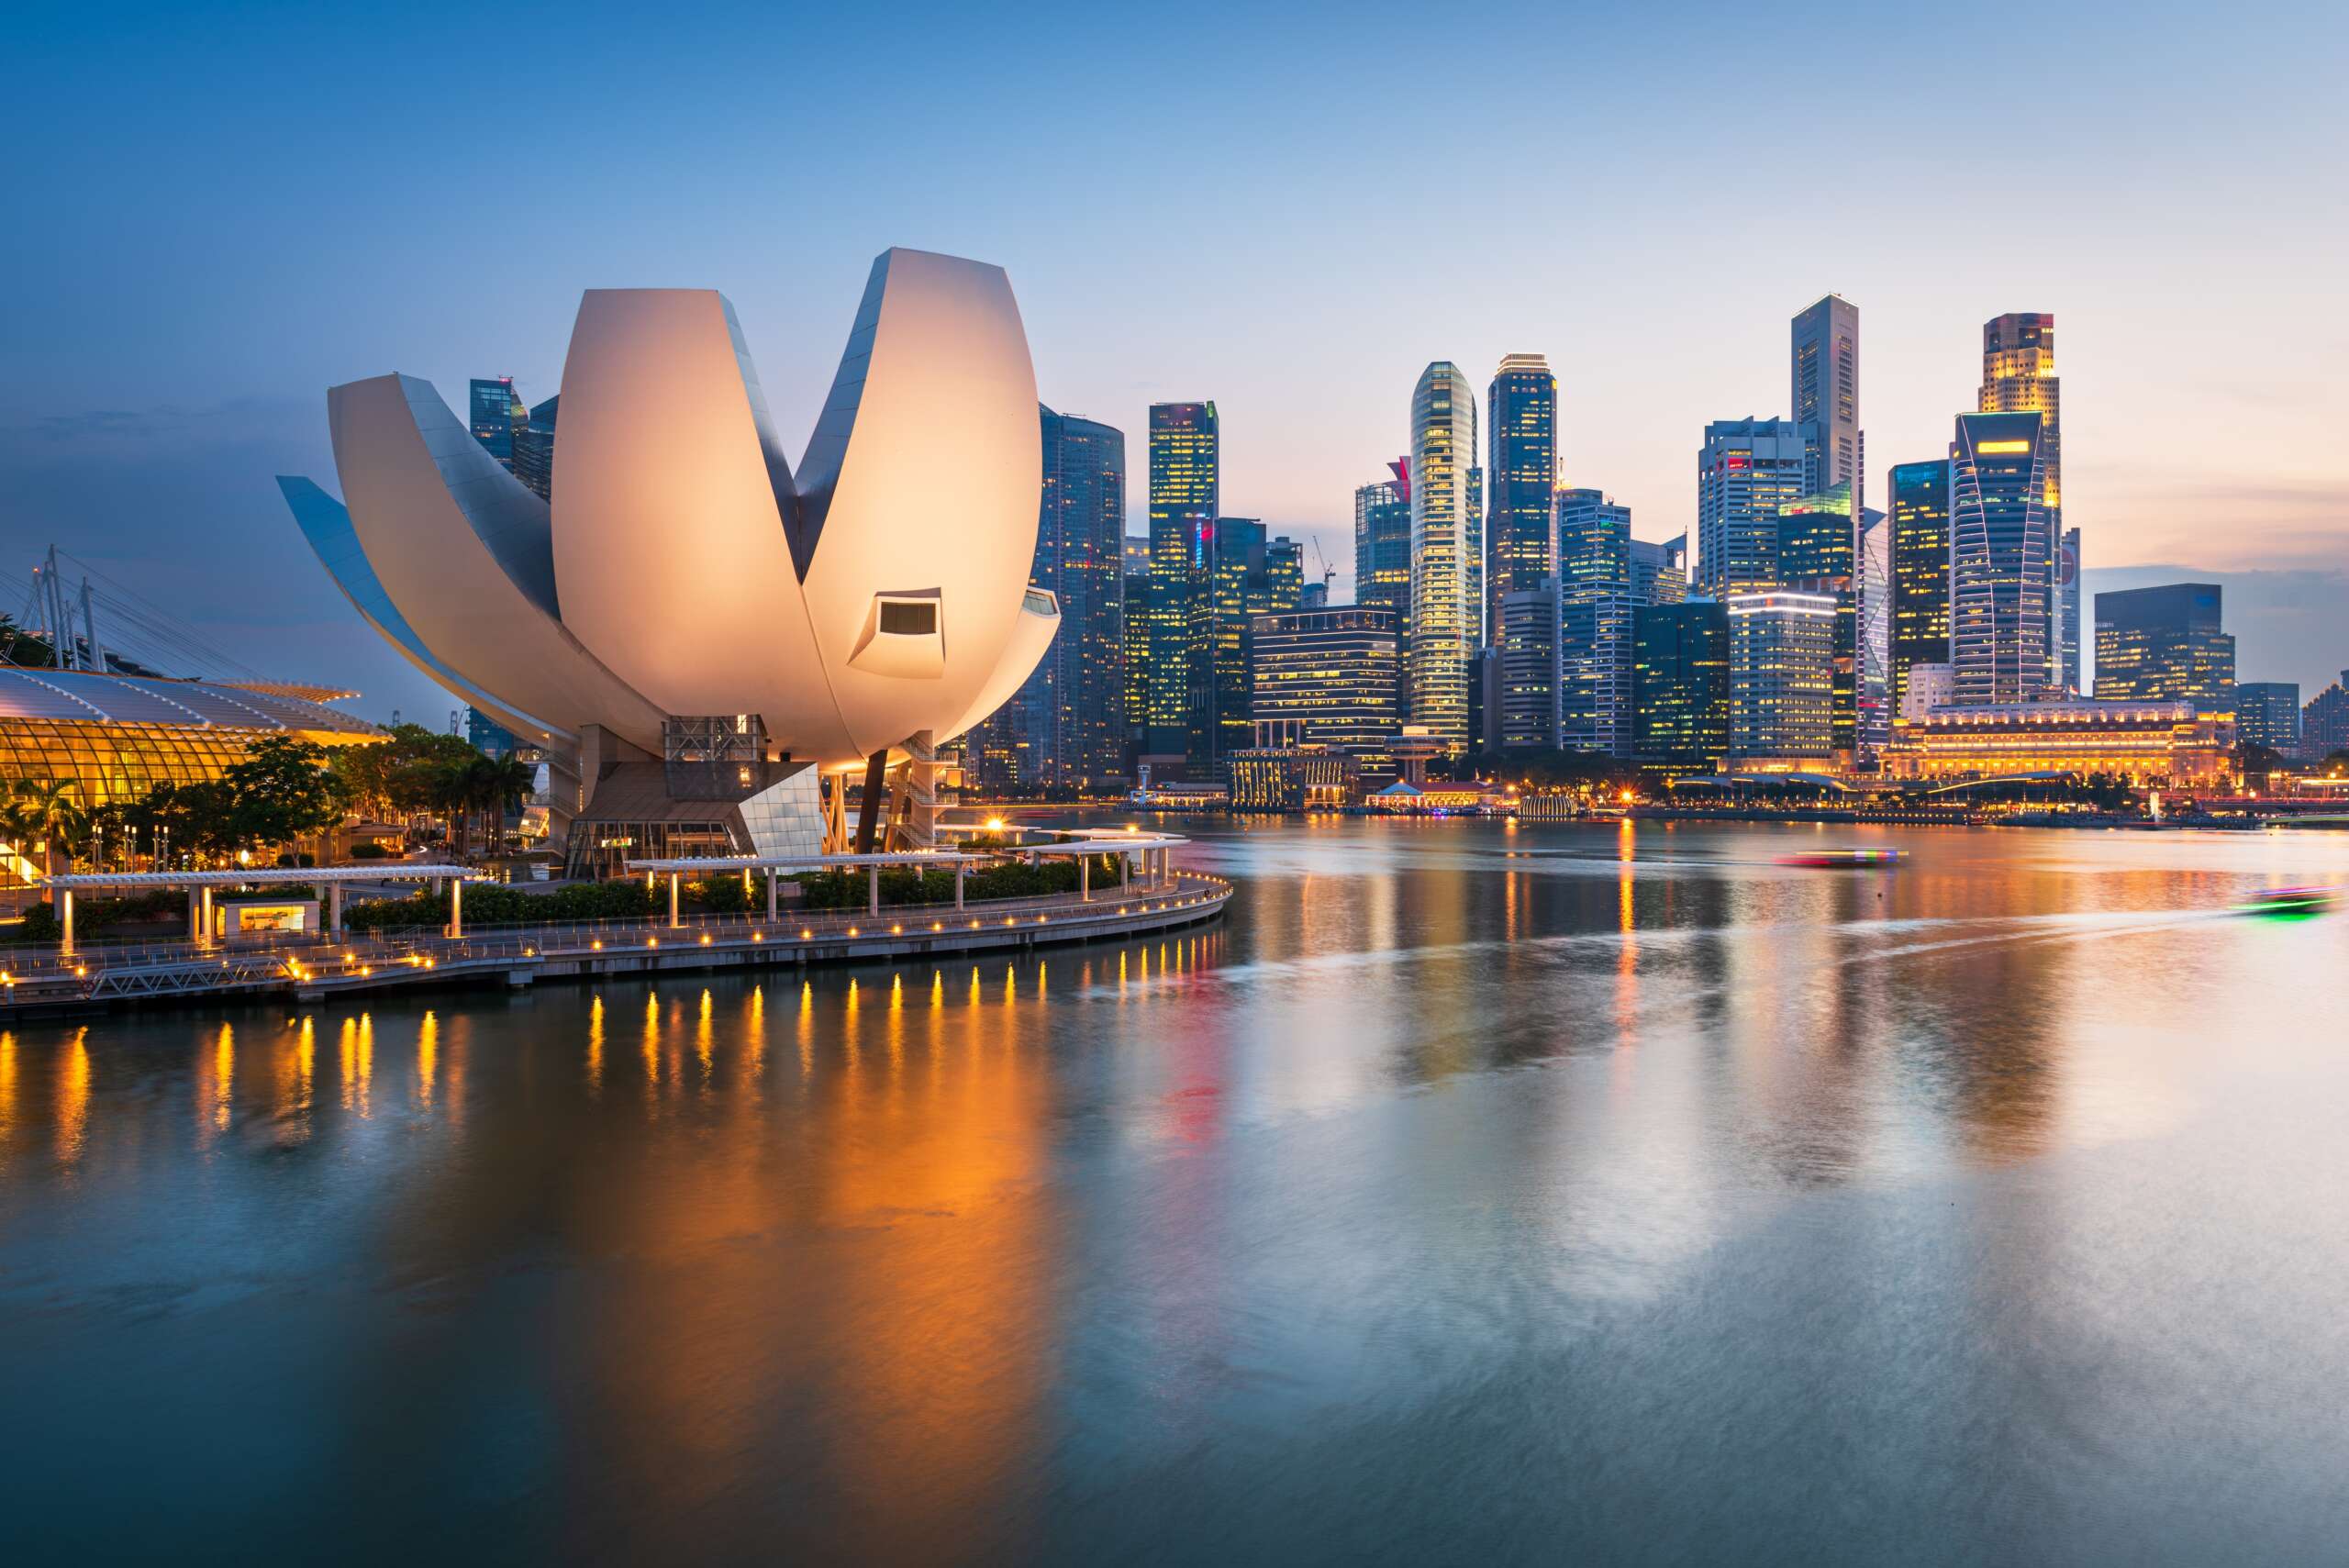
New Residential Launches Support Market Momentum Singapore's private residential property market experienced renewed activity in August 2026, supported by several major project launches. Developers launched approximately 1,893 new private homes for sale during the month, excluding executive condominiums. This represented a substantial increase in available new units compared with July, when only 153 homes were launched. Buyer activity strengthened alongside the increase in new launches. Developers sold approximately 791 private residential units in August, up from 214 units in July. The improved sales figures suggest that well-positioned new projects continue to attract interest, particularly when pricing and location align with buyer expectations. Regional Differences Shape Buyer Demand Singapore's residential market continues to demonstrate different demand patterns across its three main regions. The Rest of Central Region (RCR) accounted for approximately 47.1% of new private residential sales in August 2026, reflecting its strong contribution to market activity. The Outside Central Region (OCR) represented approximately 37.9%, while the Core Central Region (CCR)accounted for around 15.0%. Homes in the RCR priced between SGD2 million and SGD3 million attracted notable buyer interest, highlighting demand for properties offering a balance between location and affordability. Meanwhile, new residential developments in established neighbourhoods, including District 10, continue to attract attention from buyers seeking desirable locations. These trends suggest that demand is increasingly influenced by the combination of project pricing, accessibility, neighbourhood appeal and available housing supply. Outlook Singapore's private housing market is benefiting from renewed new-launch activity, although demand remains selective across different regions and price segments. Developer pricing, location quality and buyer affordability will continue to shape purchasing decisions as additional residential projects enter the market. The contents of this article were contributed by Raymond Khoo, Vice President, Orange Tee & Tie. Download to see insights from other country marketsDownload
准备开始了吗?
立即联系我们。